Iranian oil is disappearing from the market just as its biggest buyer returns for more. China’s recovering crude demand is colliding with the loss of a supplier that sustained its independent refiners through the crisis, forcing them to compete for increasingly expensive alternatives. The consequences reach beyond China: every replacement barrel tightens supplies for other buyers, while Tehran faces a growing incentive to disrupt the Strait of Hormuz, which is now carrying an unexpectedly strong 13 million barrels a day (just 5 million below pre-crisis level), while its own oil remains trapped.
Iranian crude has long been an underestimated part of the global oil balance. After Bashar al-Assad’s government fell in December 2024, breaking the political relationship that sustained Iranian shipments to Syria, China became Iran’s only crude buyer – in 2025, it received an average of 1.4 million b/d. The war initiated by the US and Israel in late February initially made Iran even more important to Chinese buyers: while Tehran blocked other tankers from crossing Hormuz, its own cargoes passed freely, lifting Chinese intake of Iranian oil to around 1.76 million b/d in April.
That competitive edge ended with the US blockade announced on April 13. Loaded tankers could no longer leave the Gulf, while empty vessels could not enter. Loadings at Kharg Island, Iran’s main export terminal, collapsed from 1.8 million b/d in March to 260,000 b/d in May. A June 17 memorandum allowing Iranian cargoes to pass for 60 days offered temporary relief: loadings recovered to 740,000 b/d in June and 890,000 b/d in July. But the reprieve expired in August, shipments slumped again to 250,000 b/d, and no Iranian loadings were observed in the Gulf in September. Related: US Distillate Stocks Continue to Fall As Crude Inventories Build
The more important part of the story, however, was unfolding outside the Strait. Iran had accumulated a vast floating stockpile that allowed deliveries to China to continue even when fresh cargoes could not leave the Gulf. In mid-April, that cushion stood at about 160 million barrels, spread across waters around South, Southeast and East Asia. Drawing on those stocks, China still imported 1.37 million b/d of Iranian oil in May, just 10% below February’s level. But the buffer was shrinking; floating storage fell to 106 million barrels by mid-June before the temporary reopening replenished it to 128 million by mid-July.
That replenishment of available floaters has since stopped. China still received 980,000 b/d of Iranian crude in August, but only 475,000 b/d in September, with arrivals ceasing from September 26 (all of the last arriving cargoes had been loaded in June).
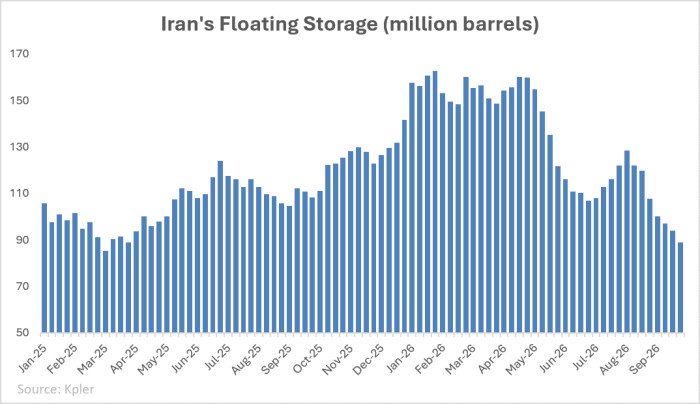
Iran still has around 86 million barrels on the water, the lowest volume since January 2025. Yet 23 million barrels (more than a quarter) are trapped inside the Gulf. The total has barely changed since Chinese arrivals have wound down to an almost complete halt over the past two weeks, with evident loadings in the Kharg island stopping completely. With onshore storage gradually filling up (Kpler data suggests Iranian storage tanks are now 60% full, storing around 70 million barrels), Iran will face the inevitable choice of cutting production. Whilst roughly 2.2 million b/d of production is relatively safe due to demand from its refineries, Tehran’s pre-war crude output of 3.2 million b/d seems to be no longer achievable.
For China’s ‘teapots’ (the smaller independent refineries concentrated in Shandong province), this removes a cornerstone of their crude supply. Accounting for roughly a fifth of Chinese crude imports, these refiners have built their purchasing strategies around discounted sanctioned barrels, particularly from Iran and Russia. Now they must search for barrels farther away, from the Middle East, West Africa and South America. In mid-September, ten Chinese independent refiners reportedly sent traders to Singapore to secure available supplies from the mentioned regions.
The shift is visible at Shandong’s ports. Qingdao, connected by pipeline to 12 independent refineries, relied on Iran for 40% of its 690,000 b/d incoming flows in 2025. In recent months, it has increased purchases of Brazil’s Tupi and Buzios grades and even started receiving Guyana’s Golden Arrow in July, while still relying on Saudi and Russian supplies. Nevertheless, intake has fallen to a record low of around 150,000 b/d over the past three months.
At Dongying, on Shandong’s northern Bohai coast, situated near 32 independent refineries, Russia and Iran supplied virtually all of last year’s 330,000 b/d intake, accounting for two-thirds and one-third respectively. Iranian deliveries started to decrease in summer months, with just two cargoes arriving in August and just one in September. Total intake fell to a mere 220,000 b/d in September as crude-deprived refiners were compelled to cut refinery throughputs.
These refiners are being left with less oil and more expensive alternatives. Guyanese crude is particularly costly when long voyages coincide with an unprecedented shortage of very large crude carriers and record freight rates. To encourage independent refiners to increase runs, the Chinese government issued an additional 28.05 million tonnes of crude import quotas in late September, taking the annual allocation for non-state imports to a record high of 257 million tonnes. These quotas determine how much crude refiners are authorised to import, so the increase gives them room to buy more, but does little to make barrels available or more affordable.
Competition for Russian oil is intensifying, too. Chinese buying has reportedly pushed ESPO differentials to an all-time high premium of $28/bbl vs ICE Brent, while Urals is also trading $7-8/bbl above the same benchmark. Independents must also compete with state-owned buyers, which currently account for roughly half of China’s seaborne crude imports, compared with 45% in February.
China’s recovery is still at an early stage. Seaborne crude imports rose from 7.24 million b/d in August to 7.5 million b/d in September, but remain far below February’s 11.5 million b/d. During April–July, imports had fallen to roughly half that pre-crisis level, depressed by the Beijing-mandated refinery product export ban, lower refinery runs and a gradual shift towards SPRs usage. China’s strategic reserves (both state- and private-owned) remain at 1.12 billion barrels, down from 1.25 billion in April, but rebuilding imports while Iranian supplies disappear will put greater pressure on barrels available elsewhere.
For Tehran, the imbalance is becoming harder to tolerate. Peace negotiations continue without a breakthrough, its crude remains blocked, and its export revenues are squeezed. Meanwhile, oil from neighbouring producers is moving through Hormuz at a surprisingly strong 13 million b/d. That recovery is both a relief for buyers and a vulnerability. As long as Iran cannot export, it has little economic incentive to preserve the arrangement allowing its neighbours’ barrels through. Mounting financial pressure could eventually push Tehran to disrupt those flows, even more than it did ever before.
The market therefore faces two connected risks: China must replace Iranian oil as its demand recovers, and Iran may lose patience with a Strait that is reopening for everyone else. The disappearance of Iranian barrels is already tightening supply. A renewed disruption to Hormuz would make the cost of replacing them much higher.
By Natalia Katona for Oilprice.com