 @realdonaldjtrump
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
President Donald Trump has described his proposed $5,000 “Trump dividend” two different ways in two days, and the gap between them could be worth thousands of dollars to families with kids.
On Oct. 2, Trump wrote on Truth Social (1) that the dividend “will be distributed to every U.S. Citizen” if Republicans win the midterms. He added the pledge to a post announcing one-time payments for more than 20 million Medicare enrollees (more on those below). When he unveiled the plan at the GOP’s midterm convention in Dallas on Sept. 9, he promised it (2) to “every adult citizen.”
Top Picks
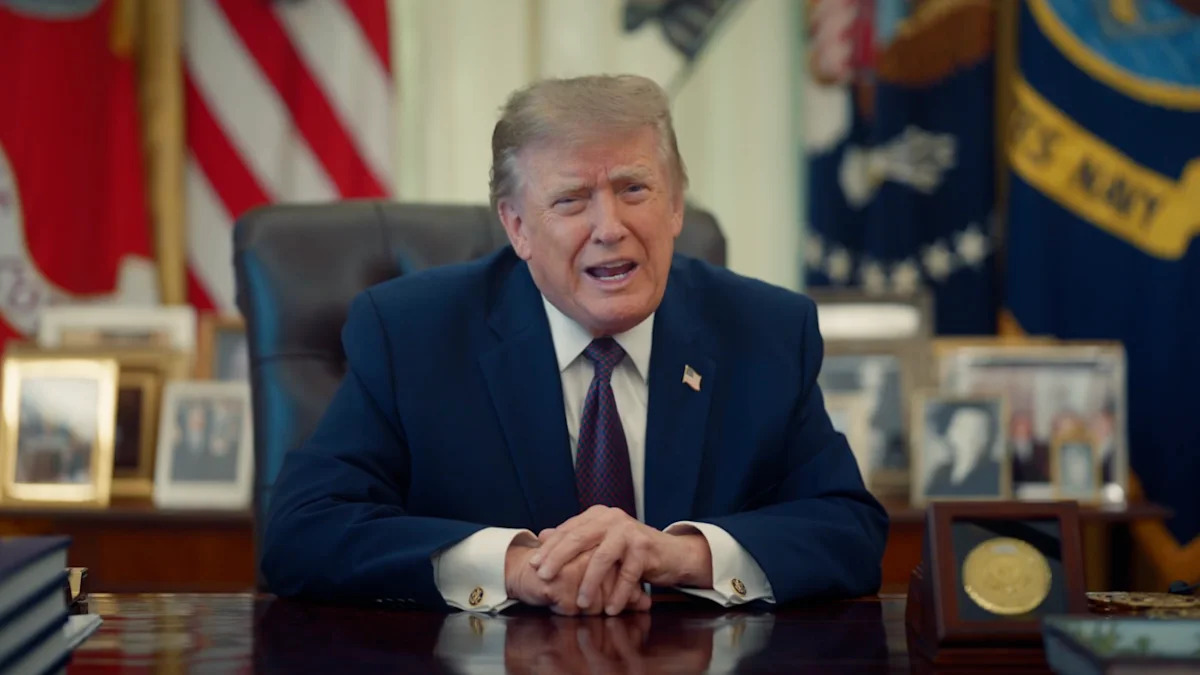
The next day, he was back to adults. “If Republicans win the House of Representatives and the Senate, I’m going to give all adult citizens in the United States of America $5,000,” Trump said in a video posted Oct. 3 (3).
Asked which version stands, the White House didn’t answer directly. Spokesperson Davis Ingle told Moneywise in a statement that Trump “has consistently proven his doubters wrong” and “will keep delivering real results,” and referred Moneywise to the president’s own comments. Those comments have pointed both ways. In Doonbeg, Ireland, on Sept. 13, Trump said the money would go to “all adults in the country,” then added (4) that “the 5,000 is going to everybody.”
Read literally, “every U.S. Citizen” would include children, which would change the math for millions of families.
The payment still hinges on Republicans keeping both the House and the Senate on Nov. 3. Even then, Congress would have to pass a bill to fund it, which House Speaker Mike Johnson has acknowledged. No bill has been introduced.
In the same video, Trump warned that “if the Democrats win, you will have an economic depression, much like 1929.” He also promised that “if the Republicans win, you will each have $5,000 in your pocket.”
Budget analysts have warned the dividend itself could feed inflation. Maya MacGuineas, president of the nonpartisan Committee for a Responsible Federal Budget (CRFB), called the dividend (5) a “half-baked political scheme” that would add to the national debt and push up inflation and borrowing costs. Economist Peter Schiff, a longtime critic of Trump’s spending plans, has made a similar inflation warning.
Trump said the dividend would cost “approximately $1 trillion,” pointing to “a record-setting $21 trillion that’s being invested in our country in just the last 15 months.” He called paying for it “a very easy thing to do.” The $21 trillion figure refers mostly to private investment commitments rather than federal revenue, and the White House’s own tally falls well short of it, Moneywise has previously reported. ABC News reported (6) that the private investment commitments the White House has cited as a funding source haven’t materialized.
The price tag is also higher than Trump’s estimate. The Census Bureau estimates (7) there are about 245 million adult U.S. citizens, and CRFB puts the cost of paying each of them $5,000 at about $1.2 trillion in a single year, or more than 3.5% of GDP.
Trump also pointed to the $1,776 “warrior dividend” paid to service members in December 2025. “I gave all members of the military $1,776,” he said in the video. According to the Defense Department (8), which the administration now calls the Department of War, that payment went to about 1.45 million active-duty members at pay grade O-6 and below and reservists on orders of 31 days or more. Congress had already funded it through the One Big Beautiful Bill Act as a one-time supplement to the military housing allowance.
Who would qualify, and who wouldn’t
Under the adults-only wording, a hypothetical family of two parents and two kids would get $10,000. If children count, that’s $20,000.
The Treasury Department estimates (9) about 73 million children are eligible for its Trump Accounts program. That program uses Social Security numbers rather than citizenship to decide who qualifies, so it’s a rough stand-in for the number of citizen children. Adding 73 million kids at $5,000 each would raise the cost by about $365 billion, to nearly $1.6 trillion, by Moneywise’s math.
Paying children based on citizenship wouldn’t be new. The $1,000 federal seed deposit for Trump Accounts goes only to kids who are U.S. citizens with a valid Social Security number, according to the IRS (10).
Vice President JD Vance told Fox News (11) the money is meant for “the American middle class” and “American workers,” suggesting income limits are possible. PBS NewsHour noted (12) that the “adult citizen in the United States of America” wording could also leave out Americans living abroad.
Trump has said the money would have to be spent in the U.S., though he hasn’t explained how that would be enforced, Time reported (13).
Sen. Bernie Moreno, R-Ohio, wrote on X (14) that he’d have a bill ready to pass the dividend “immediately after the November 3rd election.” That bill, or another like it, would set the eligibility rules, but Moreno’s office told the Dayton Daily News (15) it had no additional details to share.
Will the checks show up?
Republicans head into Nov. 3 trailing on the generic ballot. An Emerson College Polling survey (16) of likely voters conducted Sept. 21-22 found 53% plan to back a Democratic congressional candidate, compared with 42% for a Republican. Trump’s approval rating stood at 39%.
Voters like the idea more than they trust the promise. In a Sept. 11-14 Economist/YouGov poll (17), 48% favored sending $5,000 to every adult citizen and 40% opposed it. But only 21% said Trump would definitely or probably follow through if Republicans keep Congress, while 57% said he wouldn’t. Even among Republicans, just 45% expected him to deliver. An AP-NORC poll (18) published Oct. 1 found only 17% of adults say Trump keeps his promises.
The White House has pitched the dividend as Americans’ share of the country’s economic gains, and its September release pointed to private investment commitments as a possible funding source. Trump told ABC News the payment is “almost a reward for the people having to put up with Biden’s policy.” Vance has cited tariff revenue. CRFB says new tariff revenue is coming in at less than $200 billion a year and is already counted in federal deficit projections, so it can’t cover the cost. In February, the Supreme Court also ruled (19) that Trump couldn’t use an emergency-powers law to impose his sweeping tariffs.
Republicans are split. Rep. Tim Walberg, R-Mich., told the Associated Press (20) that “if it can be done, the American taxpayer deserves the benefit of having more in their pocket than the government.” Rep. Thomas Massie, R-Ky., who lost his primary to a Trump-backed challenger, wrote on X (21) that he was “insulted by the notion that my vote this November could be bought for 5k.”
Republicans already control both the House and the Senate. Asked on Fox News (22) why the payment has to wait until after the election, Trump said, “Because the Democrats can’t do it.”
Senate Minority Leader Chuck Schumer wrote on social media that Trump is “resorting to trying to bribe the American people for their votes,” and others have called the offer vote-buying. But UCLA election law professor Rick Hasen wrote (23) that “Trump would have a strong First Amendment defense,” citing a 1982 Supreme Court ruling that protected a candidate’s campaign promise.
Trump’s record on these promises is mixed. The warrior dividend is the only one of his floated payouts that has actually landed, and Congress had already funded it, while the $2,000 tariff dividend he promised in November 2025 never went out.
One payment is already going out. The Oct. 2 post that mentioned the dividend also announced one-time payments to Medicare Part B enrollees, which Trump described as “nearly $100.” A White House fact sheet (24) puts the amount at $90 per person for more than 20 million enrollees, paid from the Medicare Improvement Fund. Most will get it by direct deposit in early October, and the rest will get a check in the mail.
Enrollees whose premiums are already paid by Medicaid don’t qualify, and neither do higher earners who pay the income-related monthly adjustment amount (IRMAA). The $90 covers less than half of the standard 2026 Part B premium of $202.90 a month (25). It’s separate from the proposed dividend.
Some kids can claim a different $1,000 now
Whatever happens with the dividend, many families already have a Trump Account set up for their kids. Treasury said Oct. 1 (26) it had finished automatically opening accounts for more than 60 million children, so every eligible child under 18 with a valid Social Security number now has one “ready to be claimed.” Before that, parents had to sign their kids up themselves, and as of July 30, the IRS had processed sign-ups for fewer than 1 in 10 eligible children, according to the Treasury regulations.
Having an account isn’t the same as getting the money. The $1,000 federal seed deposit goes only to children born from Jan. 1, 2025, through Dec. 31, 2028, and automatic enrollment doesn’t trigger it. Parents still need to claim the account through the official Trump Accounts app to receive the $1,000. Children born before 2025 can still have an account, but they don’t get the seed money (27).
Families can contribute up to $5,000 a year per child. Employers can chip in up to $2,500 a year per worker, and that counts toward the $5,000 limit, according to IRS guidance (28).
Unlike the dividend, the $1,000 seed is already law. If you’d rather not wait on Washington, here are three ways to put your money to work now.
Put your spare change to work
Trump borrowed the word “dividend” from investing, where it means a slice of a company’s profits paid back to shareholders, typically every quarter.
Owning dividend-paying stocks lets you collect passive income without selling your shares. John D. Rockefeller, one of the richest Americans in history, is often quoted as saying (29), “Do you know the only thing that gives me pleasure? It’s to see my dividends coming in.”
While stock prices can rise and fall, companies with a strong track record of paying and growing dividends offer investors a steady cash flow. Over time, those increases could compound into a powerful income stream.
If you’d rather not pick individual stocks, dividend-focused exchange-traded funds (ETFs) hold a basket of dividend payers across industries, and many reinvest payouts automatically.
The beauty of ETF investing is its accessibility — anyone, regardless of wealth, can take advantage of it. Even small amounts can grow over time with tools like Acorns, a popular app that automatically invests your spare change.
Signing up for Acorns takes just minutes: All you have to do is link your cards, and Acorns will round up each purchase to the nearest dollar, investing the difference — your spare change — into a diversified portfolio.
With Acorns, you can invest in a dividend ETF with as little as $5 — and, if you sign up today with a recurring investment, Acorns will add a $20 bonus to help you begin your investment journey.
Earn rental income without becoming a landlord
Real estate is another popular way to generate recurring income. When you own a rental property and tenants pay rent, you earn a steady monthly cash flow. It’s also a popular hedge against inflation, as property values and rents tend to rise alongside the cost of living.
Warren Buffett has made a similar case. In 2022, he said that if someone offered him “1% of all the apartment houses in the country” for $25 billion, he would “write you a check (30).”
But being a landlord means screening tenants, collecting rent and paying for repairs out of pocket, and that’s after saving for a down payment and qualifying for a mortgage.
You don’t need to buy a property outright, or deal with leaky faucets, to invest in real estate today. Real estate investment platforms like mogul offer an easier way to get exposure to this income-generating asset class.
As a platform offering fractional ownership in blue-chip rental properties, mogul gives investors monthly rental income, real-time appreciation and tax benefits — without the need for a hefty down payment or late-night tenant calls.
Founded by former Goldman Sachs real estate investors, the team handpicks the top 1% of single-family rental homes nationwide for you. In other words, you gain access to institutional-quality offerings for a fraction of the usual cost.
Each property undergoes a rigorous vetting process, requiring a minimum 12% return even in downside scenarios. Across the board, the platform features an average annual IRR of 18.8%. Their cash-on-cash yields, meanwhile, average between 10% and 12% annually. Offerings often sell out in under three hours, with investments typically ranging between $15,000 and $40,000 per property.
Sign up for an account and browse available properties here to start investing today.
Let your cash hatch its own income
You don’t need a massive investment portfolio to start building wealth. Even your spare cash can earn income instead of sitting idle in a low-yield account, whether it’s an emergency fund or money you’re setting aside in case a $5,000 check ever arrives.
High-yield accounts won’t make you rich overnight, but they do offer a low-risk way to earn interest on money you may need to reach at any time.
A high-yield account like a Wealthfront Cash Account can be a great place to grow your uninvested cash, offering both competitive interest rates and easy access to your money when you need it.
A Wealthfront Cash Account currently offers a base rate APY of 3.55% through program banks. With a new client boost and direct deposit incentive, referred clients can earn up to a 4.55% APY. That’s 10 times the national deposit savings rate, according to the FDIC’s August report (31).
With no minimum balances or account fees, as well as 24/7 withdrawals and free domestic wire transfers, your funds remain accessible at all times. Plus, you get access to up to $8 million FDIC Insurance eligibility through program banks.
Trump has tied the $5,000 to the Nov. 3 results, so no dividend check is coming before then, and Congress would still have to act after. For now, the federal money you can count on is the one-time $90 Medicare payment and, for kids born from 2025 through 2028, the $1,000 Trump Accounts seed, which arrives only after you claim it.
What To Read Next
Get Warren Buffett’s best investing lessons, free. Join 250,000 readers getting Moneywise’s sharpest money reporting every week. Subscribe and we’ll send you our guide to the ideas that built Buffett’s fortune as a welcome gift.
Article Sources
We rely only on vetted sources and credible third-party reporting. For details, see our ethics and guidelines.
Truth Social (1), (3); The White House (2), (24); Fox Business (4); Center for Responsible Federal Budget (5); ABC News (6); U.S. Census Bureau (7); War (8); The Federal Register (9); Internal Revenue Service (10), (28); YouTube (11); PBS (12); Time (13); X (14), (21); Dayton Daily News (15); Emerson College Polling (16); YouGov (17); AP-NORC Center for Public Affairs Research (18); Supreme Court of the United States (19); U.S. News & World Report (20); Fox News (22); Election Law Blog (23); Centers for Medicare & Medicaid Services (25); U.S. Department of the Treasury (26); CBS News (27); Forbes (29); CNBC (30); Federal Deposit Insurance Corporation (31)
This article provides information only and should not be construed as advice. It is provided without warranty of any kind.