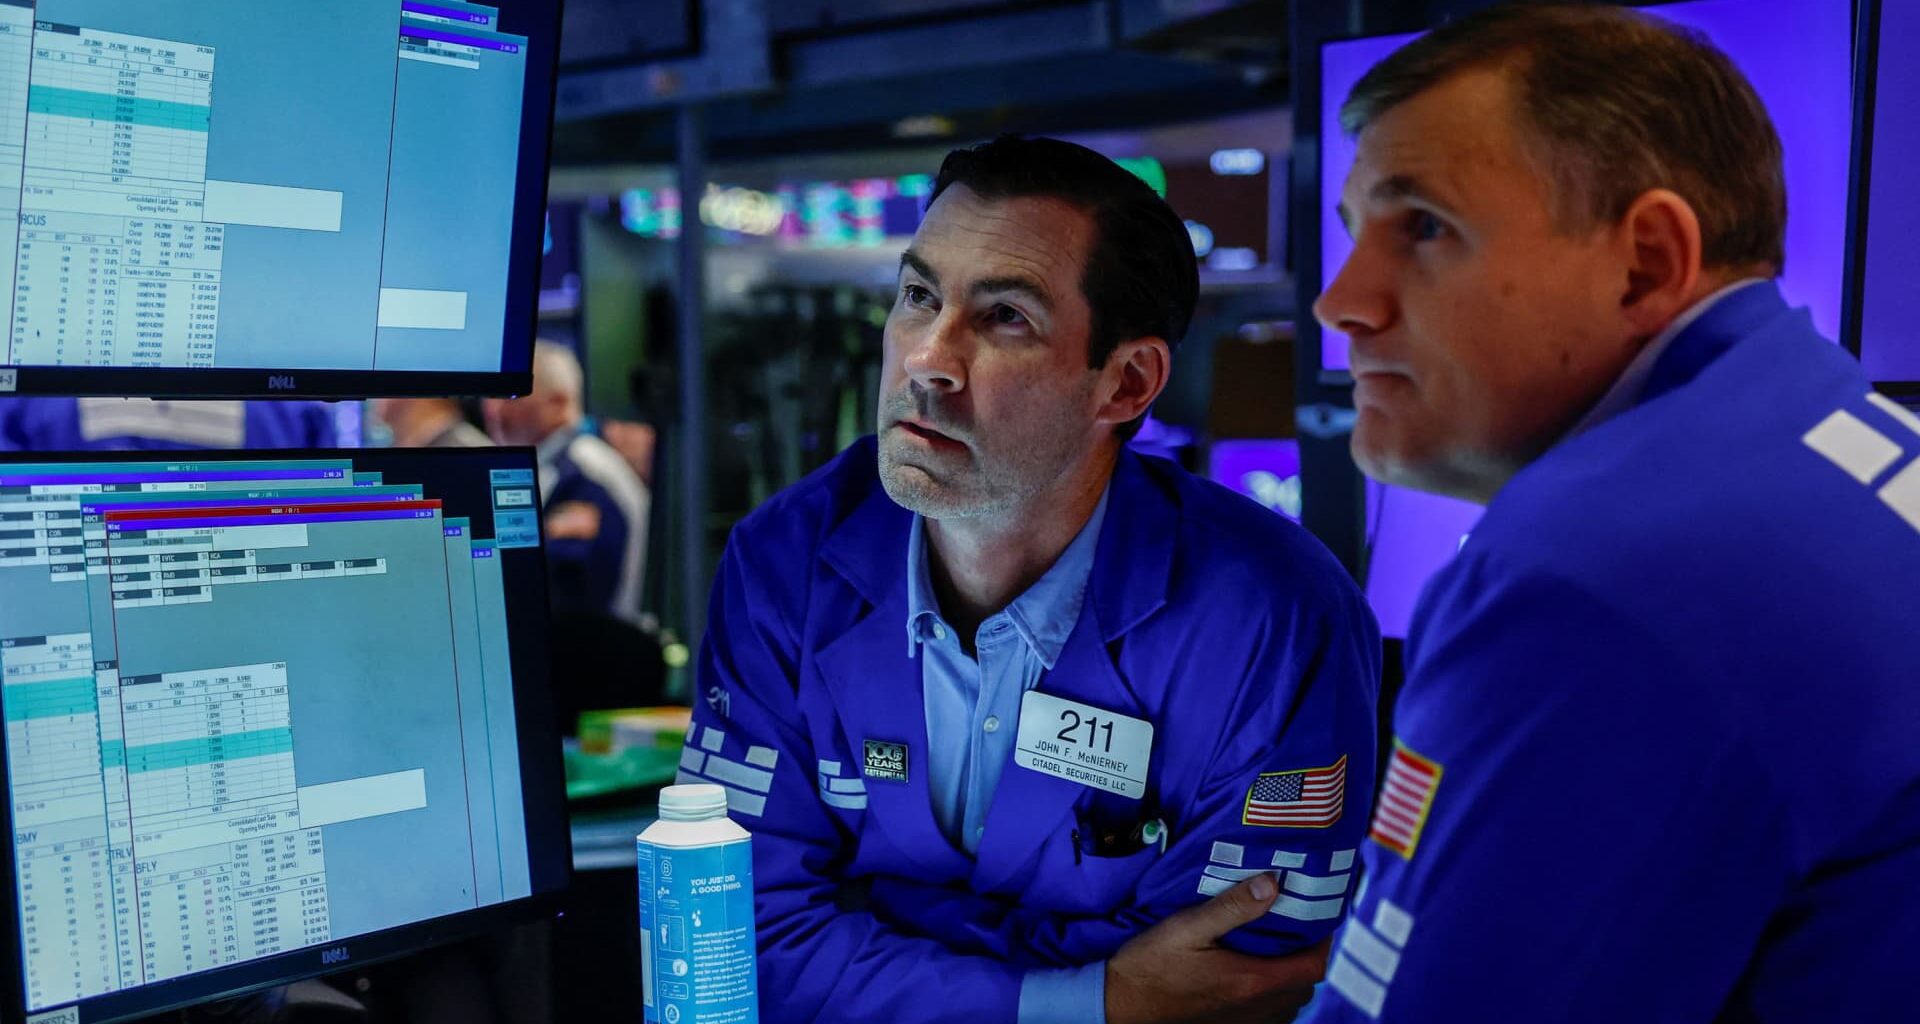
Traders work on the floor of the New York Stock Exchange (NYSE) in New York City.
Jeenah Moon | Reuters
Stock futures were little changed Monday after the major averages posted a winning week, as investors looked ahead to a busy week of earnings results and inflation data.
Futures tied to the S&P 500 climbed 0.1%, while Dow Jones Industrial Average futures rose by 53 points, or 0.1%. Nasdaq 100 futures, however, were down 0.1%.
Shares of Micron Technology were more than 2% lower in the premarket as investors assessed increasing competition from China’s CXMT, which reported progress on a new chip structure.
Oil prices ticked higher in early trading. West Texas Intermediate futures advanced 1% to around $93 per barrel. Brent crude gained 1% to trade at $105 per barrel.
Crude rose after President Donald Trump announced an ‘energy ceasefire’ between Russia and Ukraine over the weekend, then Ukrainian President Volodymyr Zelenskyy said Moscow had already violated it.
Trump also told reporters he was considering joining Saudi Arabia in its fight against Tehran-backed Houthis in Yemen after another deadly attack on Riyadh’s international airport. The remarks raised the prospect of escalating tensions in the region.
Wall Street is coming off a winning week for the major averages, as a rally in tech stocks helped investors shrug off higher oil prices and yields. The Dow and S&P 500 each posted their second positive week in three, while the Nasdaq Composite netted its fourth straight week of gains.
Investors hope the third-quarter earnings season will help stocks power through the Middle East turmoil. By all estimations, the incoming results are expected to be strong. According to FactSet’s John Butters, the S&P 500 is set to post 29.6% earnings growth in the quarter. That would be the fourth straight quarter that the broader index posts above-25% earnings growth, thanks to the strength of the AI data center buildout.
But it’s what managers say that will matter more to investors, given the uncertainty around how businesses and their customers are contending with higher fuel and borrowing costs.
“Investors have kind of narrowed in on some of the important aspects,” said Brian Leonard, portfolio manager of Keeley Gabelli Small Cap Dividend Fund (KSDIX). “Can this company withstand what’s happening? Pass along, continue to grow margins, and the future is going to be better than the most recent past.”
The reporting season will ramp up in earnest this week with the big banks, with Bank of America, Citigroup, Goldman Sachs, JPMorgan Chase, Morgan Stanley and Wells Fargo all expected to post results this week.
Key inflation data is due out this week as well, with the September consumer and producer price indexes due out Wednesday and Thursday, respectively.
This week also marks four years since the start of the S&P 500’s bull run after the index notched a closing low of 3,577.03 in October 2022. Since then, the index has more than doubled.
Across the Atlantic, the pan-European Stoxx 600 was 0.4% higher. The U.K.’s FTSE 100 added 0.6%, and the Italian FTSE MIB gained 0.7%. Germany’s DAX rose 0.7%, and the French CAC 40 moved 0.2% higher.
In Asia, South Korea’s Kospi fell 3.65%, while the small-cap Kosdaq dropped 4.83%. Australia’s benchmark S&P/ASX 200 gained 0.76%. Mainland China’s CSI 300 closed 0.68% lower. Markets in Japan were closed for a holiday.
— CNBC’s Terri Cullen contributed to this report.