

The Australian share market has been experiencing a challenging period, with a notable downturn leading to seven consecutive days of declines and the index approaching 8,600 points. Amidst this backdrop of fluctuating oil prices and global economic pressures, investors are increasingly seeking opportunities in lesser-known stocks that show resilience and potential for growth. Identifying such gems often involves looking at companies with strong fundamentals, innovative approaches, or unique market positions that can thrive despite broader market challenges.
Top 10 Undiscovered Gems With Strong Fundamentals In AustraliaNameDebt To EquityRevenue GrowthEarnings GrowthHealth RatingPeet43.28%13.82%20.62%★★★★★★Fiducian GroupNA9.85%10.78%★★★★★★JoyceNA7.70%7.34%★★★★★★Euroz Hartleys GroupNA-2.67%-37.02%★★★★★★Focus MineralsNA75.66%75.61%★★★★★★WAM Strategic ValueNA-9.74%30.51%★★★★★★SDI14.65%8.06%12.66%★★★★★☆Zimplats Holdings3.35%-10.45%-46.73%★★★★★☆AMCILNA2.99%1.18%★★★★★☆Australian United Investment6.80%2.27%1.31%★★★★☆☆
Let’s review some notable picks from our screened stocks.
Simply Wall St Value Rating: ★★★★☆☆
Overview: Cobram Estate Olives Limited is involved in the production and marketing of olive oil across Australia, the United States, and international markets with a market cap of A$1.88 billion.
Operations: With a market cap of A$1.88 billion, the company generates revenue primarily from its Australian operations (A$177.63 million) and US operations (A$60.80 million), with some deductions for eliminations and corporate costs (-A$5.40 million).
Cobram Estate Olives, a prominent player in the olive oil industry, has seen its debt to equity ratio improve significantly from 106.8% to 37.3% over five years, indicating better financial health. Despite reporting a net loss of A$11.93 million for the recent half-year period, earnings grew by an impressive 98% last year, outpacing the food industry’s growth rate of 40.2%. The company’s interest payments are well covered with EBIT at 7.5 times coverage, reflecting strong operational performance despite rising water costs impacting margins in Australia and expansion efforts in the U.S., which may affect cash flow and leverage if demand projections fall short.
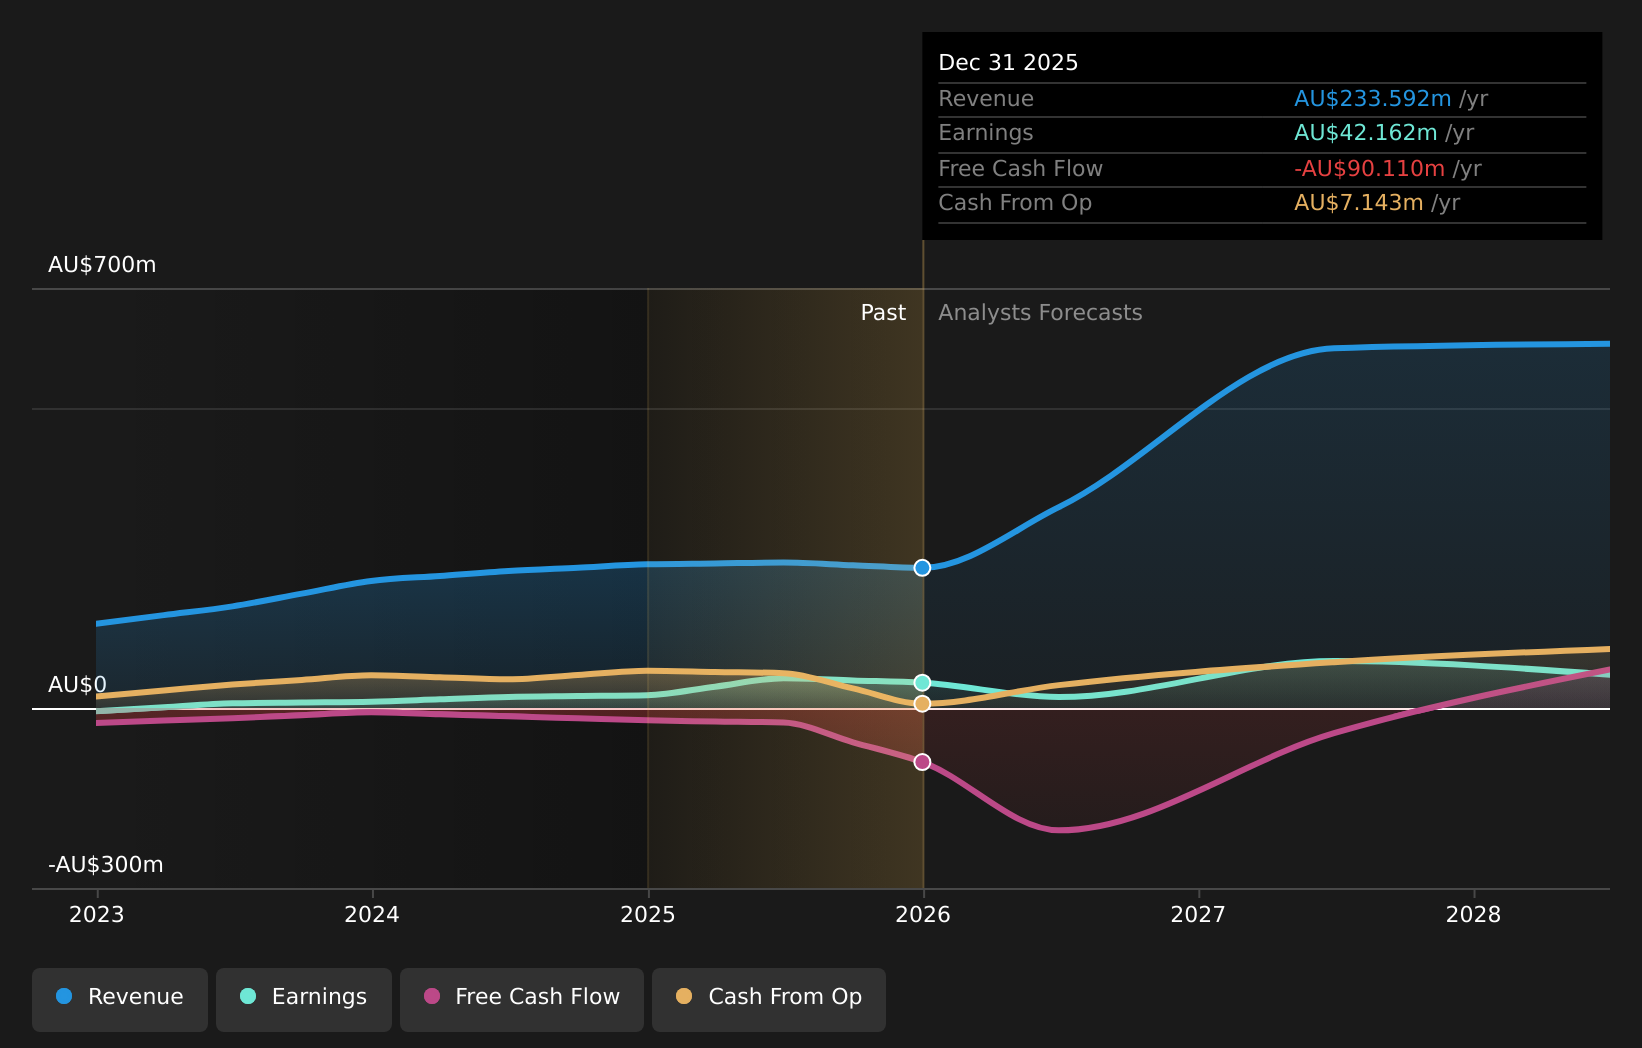 ASX:CBO Earnings and Revenue Growth as at Apr 2026
Simply Wall St Value Rating: ★★★★★★
Overview: GR Engineering Services Limited offers engineering, process control, automation, and construction services primarily to the mining and mineral processing industries globally, with a market cap of approximately A$769.70 million.
Operations: GR Engineering Services Limited generates revenue primarily from its Mineral Processing segment, contributing A$330.86 million, and Oil and Gas segment, which adds A$94.06 million.
GR Engineering Services, a nimble player in the engineering sector, is showing mixed signals. Despite being debt-free now, five years ago it had a debt to equity ratio of 18.3%. The company’s revenue forecast suggests an annual growth of 12.53%, yet recent earnings reveal challenges with net income dropping to A$17.23 million from A$21.82 million last year and sales at A$218.01 million compared to A$272.11 million previously. Trading at 33% below its estimated fair value, GR Engineering might appeal to those seeking undervalued opportunities despite its recent negative earnings growth of -23.5%.
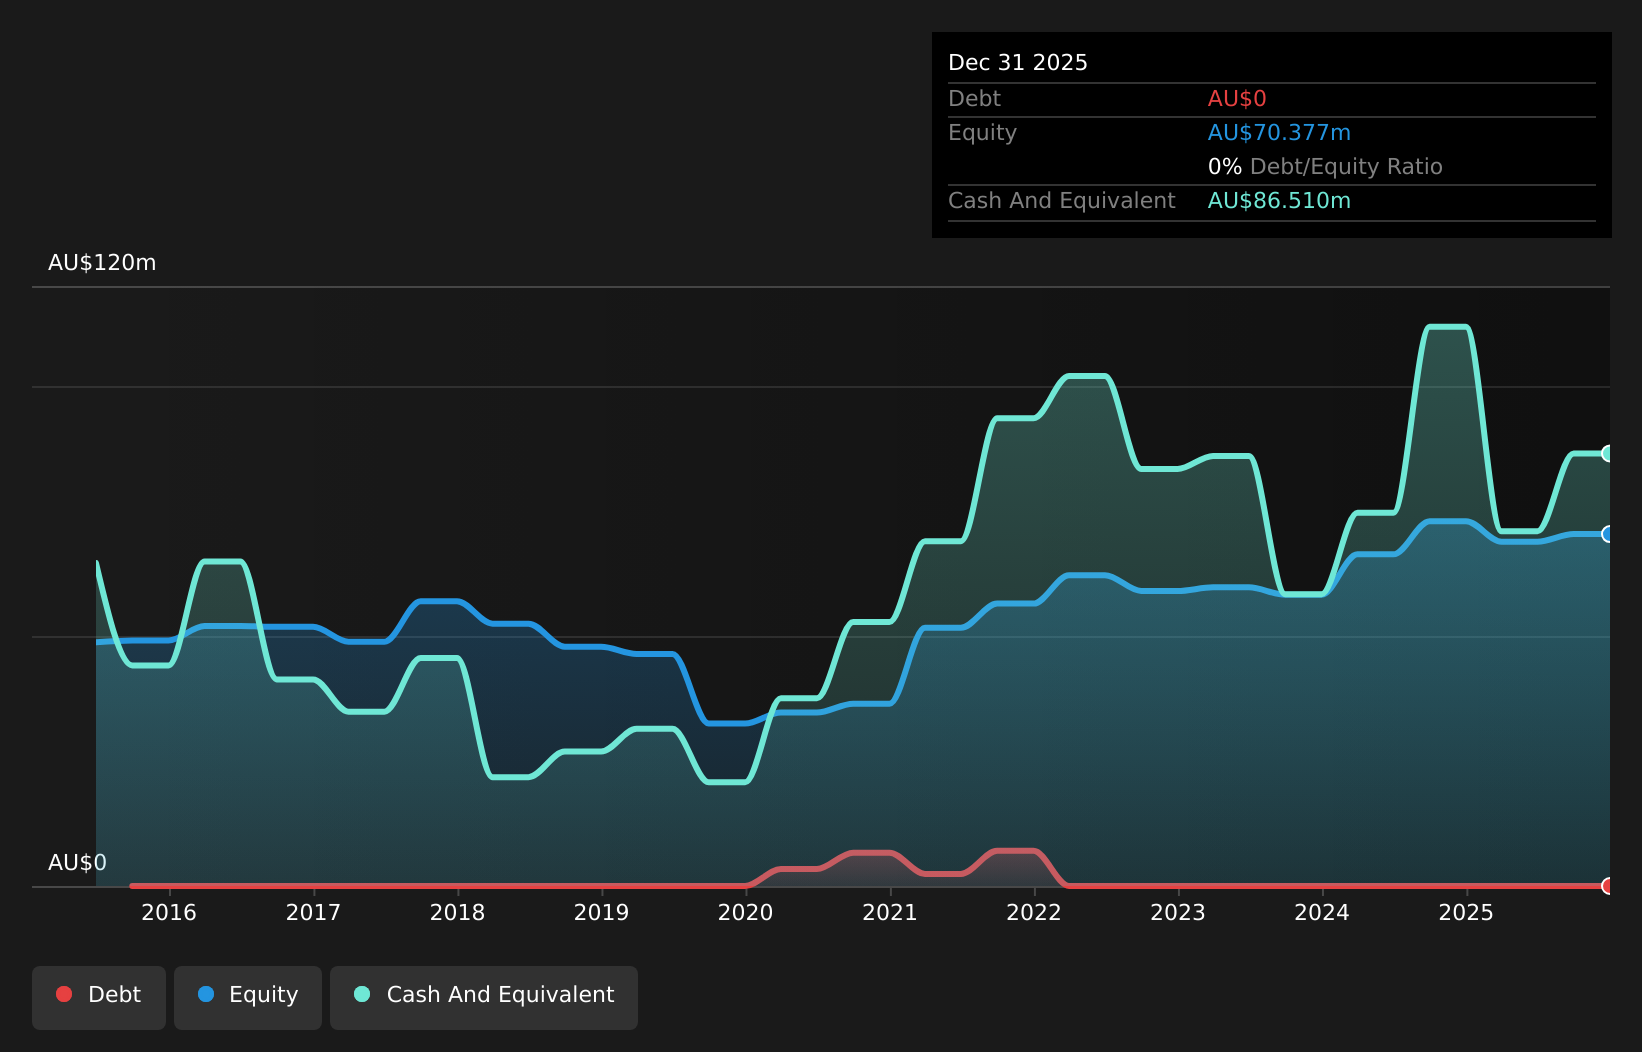 ASX:GNG Debt to Equity as at Apr 2026
Simply Wall St Value Rating: ★★★★★★
Overview: SKS Technologies Group Limited is an Australian company that specializes in the design, supply, and installation of audio visual, electrical, and communication products and services, with a market cap of A$770.34 million.
Operations: The primary revenue stream for SKS Technologies Group comes from the Lighting and Audio-Visual Markets, generating A$277.47 million.
SKS Technologies Group, a nimble player in the digital infrastructure space, has seen its earnings grow by 63.8% over the past year, outpacing the Electrical industry average of 10.2%. With no debt on its books and high-quality earnings, SKS is well-positioned to leverage growing demand for smart technology solutions. The company reported a notable rise in revenue to A$132.92 million for the half-year ending December 2025, with net income climbing to A$8.72 million from A$5.63 million previously. Despite operational risks like customer concentration and rising labor costs, SKS’s strategic investments could drive profit margins from 6.2% to 8.6%, suggesting robust potential ahead even as shares hover around A$6.90 against an analyst target of A$6.47.
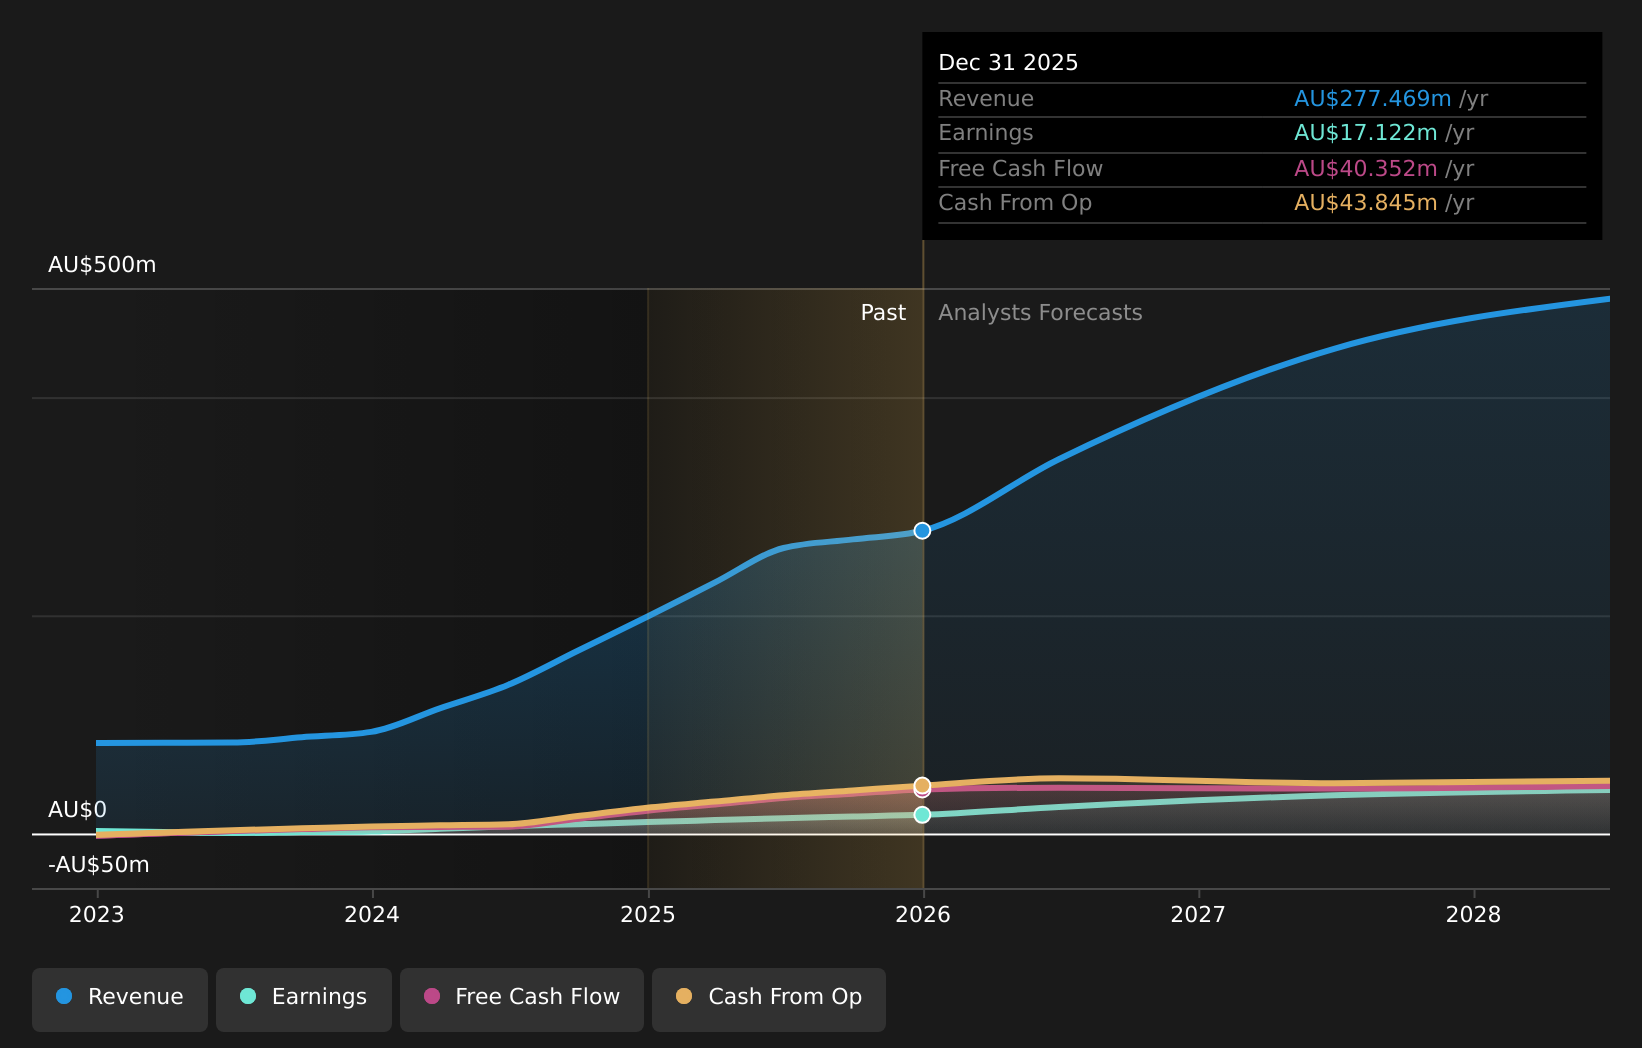 ASX:SKS Earnings and Revenue Growth as at Apr 2026Make It HappenSeeking Other Investments?
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com