
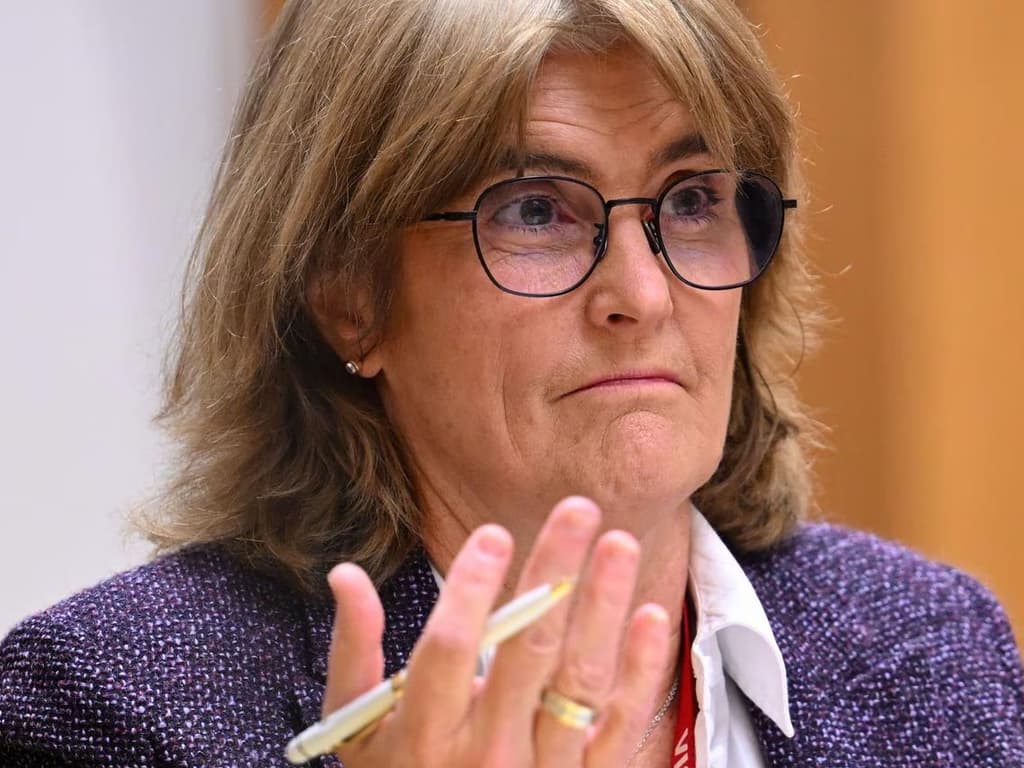

RBA Governor Michele Bullock only has “one lever” for taming inflation. Picture: Nikki Short
OPINION
Today the RBA hiked rates for the fifth time this year, taking the cash rate to an 18 year high.
The last time it was at this level, we were mired in the midst of the GFC.
But this latest hike will not be effective in bringing inflation down.
We are seeing month after month that inflation is a much bigger problem than can be solved by taking more money off people with mortgages.
And there are a couple of other problems with the way the RBA’s “only lever” (as they keep reminding us) to manipulate inflation works.
First of all, raising interest rates may mean less money in the budget for mortgage holders, but it also means more money in the budget for people who own their homes outright, because they get higher returns on their cash product investments.
MORE: The 10 economists predicting an RBA hold
Mortgage holders make up roughly a third of the adult population of Australia, but so do those who own their homes outright. So one basically offsets the other. And the latter are the ones more likely to be treating themselves to a bit of discretionary spending.
Who would be spending extra money on petrol these days, for example? Could it be the grey nomads travelling the highways in their fleets, flush with extra money from their increasing term deposit returns?
The RBA has lifted the cash rate to 4.85 per cent.
The other problem is that housing accounts for nearly a quarter of the consumer price index weighting (CPI), which the RBA uses as a gauge.
Housing prices aren’t measured in the CPI, but construction costs and rents are included.
When rates go up, landlords are more likely to increase rents to cover their own extra borrowing costs. And with vacancy rates still incredibly tight, they are able to hike rents without risking vacancy periods. Those rent increases turn up in the next CPI and, uh-oh, looks like inflation is on the rise again … better hike rates!
Surely, the time has come to find a better way to put the brakes on inflation and get it back to where it needs to be.
MORE:If your salary is below this, you’re in trouble
There have been a few alternatives suggested.
One was to raise the GST to 15 per cent. Obviously, this is something that is beyond the powers of the RBA, so it would fall to the federal government to make that happen.
It is one measure that would take money away from household budgets, but increasing the GST would require legislation to be passed.
It’s hard to imagine a government getting bipartisan support for a tax increase and to go to an election with a policy to raise taxes would be political madness. Especially for Labor, after witnessing the spectacular fallout for its popularity since introducing what it must have thought were safe tax increases on property investors in the May budget this year.
The new rate of 4.85 per cent is the highest since GFC times.
Another option is changes to superannuation. An idea floated was to raise compulsory super contributions. In Australia, the super contribution rate is currently 12 per cent.
So in times of inflation, that rate could be increased to 14 or 15 per cent, which would reduce the amount of money people have to spend, but they would retain it in their savings to access later in life.
MORE:Hated money move fuels recession fears
That extra money in their super would also grow further through investment.
That would certainly be more palatable for average Australians than simply paying more money to the government in tax, or contributing more interest to the multi-billion dollar profits of the banks.
Surely more money in super would be better than paying the bank or the government.
This potential solution would also require to be legislated and could take some time to work its way through, but who’s to say it’s not worth a shot?
All the alternative options should be on the table at the moment, because rate hikes just aren’t working. And how much more can borrowers be squeezed?
How much frivolous spending are they really still doing?
It’s time for change. We need to take the responsibility off the RBA and find some new levers to pull.