
To print this article, all you need is to be registered or login on Mondaq.com.
Article Insights
Herbert Smith Freehills Kramer LLP are most popular:
within Transport, Antitrust/Competition Law and Environment topic(s)
in Australia
Updated compulsory merger notification rules
From 1 January 2026, under the new Part IVA Competition and
Consumer Act 2010 (Cth) (CCA), businesses may need to notify the
ACCC of any acquisition of shares or assets that meet the
notification revenue and transaction thresholds.
Transactions that meet the notification thresholds (and cannot
rely on any exceptions) will need to be notified to the ACCC and
approved before completion. This week Treasury made a new
Notification Determination that updates the rules dealing with the
notification thresholds and certain exceptions. The effect of the
new rules include:
New rules on who is a ‘connected entity’ for private
companies and non-listed trusts
Limiting the ability to rely on the ‘no
control’ exception based on changes in
‘voting power’
Changing the monetary thresholds for
asset acquisitions that do not involve acquisitions of all or
substantially all of the assets of a business (some changes
commencing 1 January 2026 and some 1 April 2026)
Making acquisitions of interests in
land exempt where they are in ‘the ordinary
course of business’
‘Grandfathering’ agreements for lease
(AFLs) in certain circumstances
Changing how the rules for determining
the revenues of the acquirer (and its
connected entities) operate
Clarifying and expanding the exemptions associated with debt
instruments, money lending, financial
accommodation and security interests for loan
transactions involving security interests
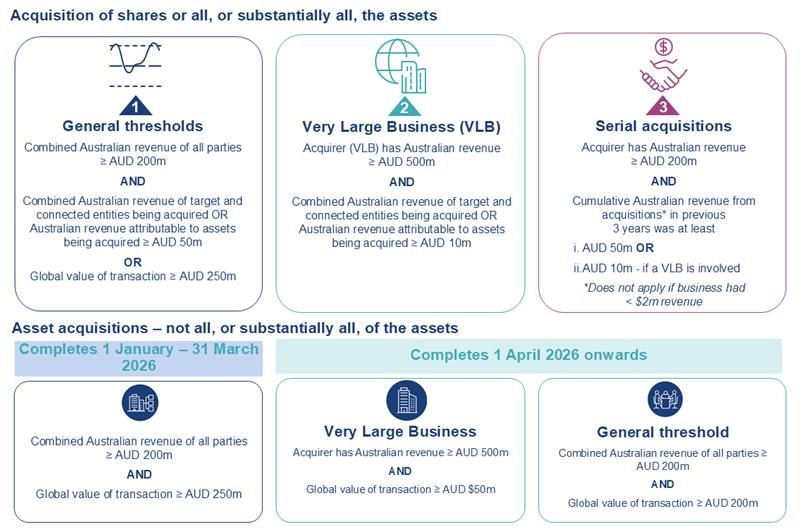
Updated financial thresholds – staggered start dates
New rules for who is a ‘connected entity’ for private
companies and non-listed trusts
Transactions may be notifiable where the Australian annual gross
revenues of the acquirer (principal party) exceed the notification
thresholds. The rules include the revenues of the principal
party’s ‘connected entities’. Connected entities
include related entities
and control entities.
The related entity concept broadly corresponds to the related
body corporate provisions in the Corporations Act 2001 (Cth)
(Corporations Act) – and captures (with some
modifications) subsidiaries, holding companies and co-subsidiaries.
The control entity is a broader concept. It captures not just legal
ownership, but practical control (including control together with
one or more ‘associates’, within the meaning of Chapter 6
of the Corporations Act). This second ‘control
test’ adopts the definition of ‘control’
in section 50AA of the Corporations Act and ‘associates’ in
Chapter 6 of the Corporations Act. An entity controls another
entity when it, alone or with ‘associates’, has the
capacity to determine the outcome of decisions about the second
entity’s financial or operating policies.
Commonwealth Treasury has amended the rules for determining
‘connected entities’ in response to concerns that the
inclusion of the definition of ‘associates’ in the
‘control test’ would result in the over-capture entities as
having ‘control’ of the principal party and therefore
inflate the Australian revenues for the purposes of the
notification thresholds.
Where passive or largely passive shareholders or investors have
agreements which include terms dealing with decision making in
relation to the affairs of the principal party, the application of
the ‘associate’ component of the control test may mean that
all shareholder or investors are deemed to have ‘control’
and their revenues need to be included for the purposes of applying
the financial thresholds (including irrespective of the size of
their shareholding).
The new rules (which take effect on 1 January 2026) address this
concern by expressly excluding ‘minority
shareholder rights’ from the control analysis.
The new rules mean that a shareholder or investor in the principal
party will not be taken to be an ‘associate’ of other
shareholders solely because they have an agreement that gives them
‘minority shareholder protection rights’. The new rules
only apply to entities that are not Chapter 6 entities under the
Corporations Act (Chapter 6 entities include listed companies,
companies with more than 50 members, or listed managed investment
schemes).
Minority shareholder protection rights are defined as a bundle
of rights that meet all of the following:
they are consistent with rights normally accorded to
minority shareholders to protect their financial interest as
investors;
they are reasonably appropriate and adapted to achieving that
purpose and not for some other purpose; and
they do not include the capacity to control or practically
influence (alone or in concert with others):
the composition of the board,
the appointment or termination of senior managers,
decisions about the entities’ financial and operating
policies.
The practical effect of these updated rules will be to
remove the risk that the Australian revenues of passive or largely
passive investors in private entities undertaking acquisitions will
need to be taken into account in the application of the
notification thresholds.
New rules from 1 April 2026 limiting reliance on exemption for
acquisitions that do not give rise to ‘control’
Section 51ABS of the CCA provides that an acquisition of shares
or units will be exempt from the notification obligations if the
acquisition does not result in ‘control’, within the
meaning of section 50AA of the Corporations Act (with some
modification). In general terms, in determining whether the
‘control exemption test’ for the mergers regime applies, it
requires asking whether the acquisition gives a person or entity
the capacity to determine, alone or jointly with one or more
associates, the outcome of decisions about the target’s
financial or operating policies. The term ‘associates’ has
the meaning given to it in ss 12 and 15 of the Corporations Act and
it includes persons ‘acting or proposing to act in
concert’.
The CCA gives the Minister power to make a ministerial
determination determining a class or classes of acquisitions that
will not have the benefit of the exemption in s 51ABS. The updated
rules provide that, subject to satisfaction of the notification
thresholds, acquisitions of shares or units in a unit
trust or interests in a managed investment
scheme (within the meaning of the Corporations Act)
do not have the benefit of s 51ABS of the CCA where:
Unlisted bodies corporate with less than 50
members – the acquisition results in
someone’s voting power increasing from 20% or below to more
than 20%
All bodies corporate – the acquisition
results in someone’s voting power increasing from 20% or more
to 50% or more
Bodies corporate that are listed or have more than 50
members – a person or entity already
controls the target (within the meaning of s 50AA of the
Corporations Act) and the acquisition increases their voting power
from 20% or below to more than 20%
Bodies corporate that are listed or have more than 50
members – a person or entity does not
control the target (within the meaning of s 50AA of the
Corporations Act) and the acquisition increases their voting power
from below 20% or below to 50% or more
The term ‘voting power’ is given the same meaning it is
given under s 610 of the Corporations Act and in general a
person’s ‘voting power’ in a target entity will be the
sum of the voting shares in the target entity in which the person
has a relevant interest plus the voting shares in the target in
which the person’s associates have a relevant interest, divided
by the total voting shares multiplied by 100. For bodies corporate
that are unlisted or have less than 50 members, when calculating
the voting power of a person the voting power of any associates
will be excluded where the arrangements between the person and the
associate(s) only give the associate(s) ‘minority shareholder
protection rights’ (see definition above). However, where a
person is acquiring a minority shareholding in a private company
and becoming party to a shareholders agreement (or similar) in
relation to that company, it will still be necessary to assess
whether that person is acquiring a “relevant interest”
(broadly defined to cover direct or indirect control over the
voting or disposal of shares) in all or a majority of shares in
that company as a result of the terms of the shareholders
agreement.
New monetary thresholds for asset acquisitions
Acquisitions may be notifiable when the rules for transaction
value or revenue attributable to the target are met. The new rules
have been made in response to stakeholder concerns that for
transactions that involved the acquisition of only some of the
assets of a business the rules made in July 2025 required parties
to ‘attribute’ some of the business revenue to the assets.
Stakeholders were concerned that the application of these rules was
uncertain and burdensome to apply.
The new Determination made this week by Treasury repeals certain
aspects of the July 2026 Notification determination and introduce
new rules that will apply from 1 April 2026.
If a transaction is put into effect between 1 January
2026 to 1 April 2026 and the transaction involves
only the acquisition of assets and those assets are not all or
substantially all of the assets of a business the acquisition will
only be notifiable if the acquirers revenues exceed $200 million
and the transaction value exceeds $250 million.
If a transaction is put into effect from 1 April
2026 the new rules introduce an additional
transaction value test for the acquisitions of assets that do not
constitute all or substantially all of the assets of a
business.
The new transaction value test means
that:
where an acquisition satisfies the combined revenue test on the
contract date (combined Australian revenue is AUD$200
million or more) – and the market value of, or
consideration received or receivable for, the target asset is over
AUD$200 million, or
where an acquirer satisfies the very large business revenue
test (revenue is AUD$500 million or more)
– and the market value of, or consideration received or
receivable for, the target asset is over AUD$50 million,
the asset acquisition will need to be notified (unless it is
subject to one of the exemptions including the new “ordinary
course of business” exemption outlined below).
In this context, “market value” takes its ordinary
meaning – the price that a willing, but not anxious,
purchaser would, as at the date in question, have had to pay to a
vendor who was not unwilling, but not anxious, to sell.
“Consideration” also takes its ordinary meaning, the
amount paid for the target and includes cash and non-cash
consideration.
What is the ‘transaction value’ of a leasehold
interest?
The Treasury Explanatory Note for the Notification Determination
indicates that for a leasehold interest, consideration will
generally be the total of:
the upfront initial payments (other than taxes and regulatory
charges) for the grant of the interest;
annual lease payments including amounts as increased in
accordance with a formula over the term of the lease;
the amount likely paid for an extension or renewal of the lease
(if prescribed in the lease agreement).
In determining whether the revenue tests for the notification
thresholds are met, the revenue of the target attributable to the
assets of the business will only be included where the acquisition
is of all or substantially all of the assets of the business.
New exceptions for acquisitions of interests in land
Importantly, for businesses (excluding major supermarkets) that
acquired an equitable interest in land before 1 January 2026
(previous interest), the same acquirer will not have to notify the
acquisition of the subsequent interest where that occurs after 1
January 2026 (subsequent interest) provided
that:
The size of the land to which the previous interest and
subsequent interest relate are materially the same; and
The proportion of the ownership interest in the land which the
previous and subsequent interests relate are the same.
This means that for parties that entered into Agreements for
Lease, Option Deeds or other agreements for equitable interests in
land which took effect prior to 1 January 2026, there will be no
requirement to notify the subsequent legal interest acquisition
(e.g. entry into the actual lease or purchase contract).
The explanatory note to the Amending Determination gives the
following guidance.
Where an acquirer entered into an agreement for lease prior to
1 January 2026, (ie an equitable interest in land) the subsequent
acquisition of the legal interest on entering into the lease does
not require a separate notification provided
that the land remains unchanged.
Minor, incidental changes will not exclude the acquirer from
relying in this exemption. Minor, incidental changes are, for
example, routine land title changes, easements, boundary
adjustments or the registration of a strata plan.
The exemption would not be available where, for example, the
initial equitable interest acquired was a 20% interest in land but
at settlement, that interest was increased to a 50%
interest.
Acquisitions of land that are
in the ordinary course of
business are exempted
Under the new rules where a person acquires a legal or equitable
interest in land that is in the ordinary course of
business, that acquisition is exempt from
notification.
What constitutes ‘ordinary course of business’ is
critically important in this context. Only a few court cases have
applied the term of ordinary course of business, the key principles
of which are set out below.
Ordinary course of business should not be interpreted as a
reference to the ordinary course of the acquirer’s, or anyone
else’s business. It refers to the ordinary course of
business,1 in general.
Case law suggests that conduct may be in the ordinary course of
business if that conduct:
regularly takes place in a sustained course of activity or some
usual process;2
takes place as part of the undistinguished common flow of
business done;3 and
does not arise from any special or unusual circumstances and is
something a business manager could undertake without special
approval or reporting requirements to superiors for example a board
of directors.4
The explanatory note to the Amending Determination states
expressly that use of the phrase in
the ordinary course of business is a
deliberate decision recognising the history of the phrase in
legislation and case law. It gives the following examples and notes
that these types of acquisitions will qualify for the exemption
even where they are large or infrequent acquisitions:
the acquisition of an interest in land for the purpose of an
office, headquarters or other routine trading activities;
the acquisition of office towers for commercial property
investment;
a property development company acquiring land to develop
residential or commercial property;
retailers leasing or acquiring land for a warehouse to store
inventory;
a manufacturer leasing or acquiring land for a new
manufacturing facility;
an energy generator acquiring land for a solar farm;
an energy distributor acquiring land to build pylons.
The Explanatory Note also describes examples that
are not intended to be exempt. They
include:
acquisitions of land for the purposes of land-banking;
acquisitions of land from which a competitor is operating their
business;
the transfer of production or supply capacity from one
competitor to another.
Additional exceptions for subsequent land and quasi-land
interest acquisitions
The new rules expand the existing exception for acquisitions of
subsequent legal or equitable interests in land (where the initial
equitable interest acquisition in the same land had already been
notified to the ACCC) to now also cover:
where any initial equitable interest acquisition over the same
land was determined by the ACCC not to require notification
pursuant to the waiver application process; and
subsequent acquisitions of legal or equitable interests in
‘quasi-land rights’ which include mining, quarrying or
prospecting rights, water entitlements or rights in creation to
land or forestry operations.
Debt Instruments, money lending, financial accommodation and
security interests
Following considerable comments from industry participants
regarding the previous Determination, there have been significant
changes to the rules dealing with debt instruments, money lending,
financial accommodation and security interests. Whilst various core
concepts remain, the changes are sufficiently substantive that the
relevant section of the Determination has been repealed and
replaced.
The types of transactions subject to exemptions are broad in
scope reflecting the various forms of financial products and
services which come under this heading. Market participants will
need to consider both the wording of the Determination and the
extensive comments in the Explanatory Statement. For example, the
Determination exempts from notification requirements an acquisition
of shares or assets which is part of an “asset securitisation
arrangement”. The term “asset securitisation
arrangement” is not defined and may cover a wide range of
activity. The Explanatory Statement provides significant guidance
as to the intended scope of such concepts.
Core exemption classes
The Determination sets out a broad class of instruments,
arrangements and transactions for which no notification is required
(subject to the conditions discussed below). These include:
debt instruments (whether or not contingent or
conditional);
loans;
a debt interest in an entity;
asset securitisation arrangements;
securities financing transactions; and
acquisitions that are directly connected with or occur as a
result of such transactions.
Not all of these concepts are defined. There is a new definition
of “loan” in the Determination. The explanatory note
remarks that the definition is non-exhaustive and is broadly
intended to “capture arrangements that may not strictly
qualify as ‘loans’ in other contexts (such as in accounting
or other legal contexts).” The loan exemption is intended to
cover a range of loan market and financial accommodation practices,
including whole of loan sales, forward flow arrangements, sale and
repurchase arrangements and other types of arrangements.
Whilst the term “asset securitisation arrangement” is
not defined, the explanatory note sets out over a number of pages
what might be considered an asset security arrangement. This
exemption is intended to cover the full lifecycle of securitisation
structures used in financial markets, including, for example,
acquisitions associated with the establishment of a warehouse
vehicle, a securitisation vehicle, the granting, transfer, release
of guarantees, the issuing of instruments, as well as range of
other matters.
Limitation to exemptions
There are limitations on the operation of the above exemptions.
Relevantly, the exemptions will not apply in circumstances where
the acquisition has the effect that a person will begin, or can
begin, to control the relevant entity (within the meaning of
section 50AA of the Corporations Act, subject to the modifications
set out in the CCA). Importantly, this limitation does not apply in
respect of acquisitions of a share or asset which are part of, or
directly connected with, or occur as a result of an asset
securitisation arrangement.
Security Interests
As per the prior determination, the new determination provides
for a notification exemption for acquisitions involving security
interests. There have been some significant changes to the
approach.
An exemption is provided for the acquisition of shares or assets
taken or acquired as a security interest or where the share or
asset is directly connected with the taking or acquiring of a
security interest (but does not relate to the enforcement of the
security interest). A change from the earlier determination is
intended to ensure that an exemption applies “regardless of
whether there is a change of control of an entity, or an
acquisition of all or substantially all of the assets of a
business”.
The Determination separately considers circumstances where the
acquisition of the share or asset is a direct result of the
enforcement of a security interest. This exemption is narrower than
the exemption considered above. In the context of enforcement of a
security interest the relevant acquisition must occur in the
ordinary course of business of providing financial accommodation
with parties dealing with each other at arm’s length or for the
benefit of one or more parties to financial accommodation provided
to them in the ordinary course of their business of providing
financial accommodation and at arm’s length terms.
A new definition of security interest has been introduced.
Responding to commentary on the earlier determination, the
definition now refers to the meaning of a security interest given
by the Personal Property Securities Act
2009 (Cth), a charge within the meaning of the
Corporations Act as well as a lien or pledge. Collateral under a
credit support agreement continues to be included in the
definition.
Asset Financing
A new provision exempts certain asset financing transactions
from notification requirements. This is intended to avoid double
notifications over the same assets. The amendment does not exempt
the subsequent acquisition of a relevant asset by the client of the
financier assuming that other relevant thresholds required for
notification are met.
Nominee exemption
The Determination also inserts a new provision dealing with
acquisitions by nominees and other trustees occurring in the
context of loss absorption mechanisms under APRA prudential
standards. This exemption has been included to ensure that
notification requirements do not interfere with certain core APRA
functions.
Footnotes
1. TPC v Gillette (No 2) (1993) 118
ALR 280.
2. Taylor v White (1963) 110 CLR
129.
3. Downs Distributing Co Pty Ltd v Associated
Blue Star Stores Pty Ltd (1948) 76 CLR 463.
4. Re Bradford Roofing Industries Pty
Ltd [1966] 1 NSWR 674.
The content of this article is intended to provide a general
guide to the subject matter. Specialist advice should be sought
about your specific circumstances.