
China-Australia economic ties in 2026 are defined by resilient trade, selective investment, and expanding policy frameworks, shifting the relationship from disruption to structured engagement. For investors, the opportunity lies in navigating regulation, diversifying exposure, and leveraging growth in services, clean energy, and strategic sectors.
The China-Australia economic relationship is entering 2026 on a more stable and commercially viable footing than in previous years. While tensions between 2020 and 2022 disrupted trade flows, recent developments point to a recalibrated engagement model characterized by resilient trade volumes, selective investment, and diversified policy frameworks.
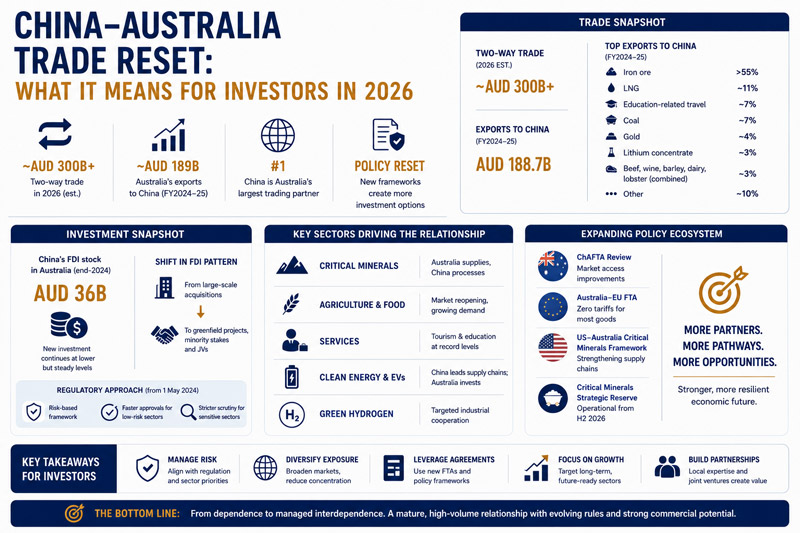
Two-way trade remains above AUD 300 billion (US$213.45 billion), services exports have recovered strongly, and new bilateral and multilateral policy tools are expanding investor options. For businesses, the key takeaway is a shift away from a “restriction narrative” toward managed interdependence with broader strategic flexibility.
Explore vital economic, geographic, and regulatory insights for business investors, managers, or expats to navigate China’s business landscape. Our Online Business Guides offer explainer articles, news, useful tools, and videos from on-the-ground advisors who contribute to the Doing Business in China knowledge.
Start exploring
Trade recovery and structural resilience
Trade data underscores the durability of the bilateral relationship. Since the entry into force of the China-Australia Free Trade Agreement (), two-way trade has more than doubled, from AUD 151.2 billion (US$107.55 billion) in 2015 to AUD 311.7 billion (US$221.73 billion) in 2024. (FY2024-25) still records AUD 309.0 billion (US$219.80 billion) in trade, with Australian exports to China reaching AUD 188.7 billion (US$134.23 billion).
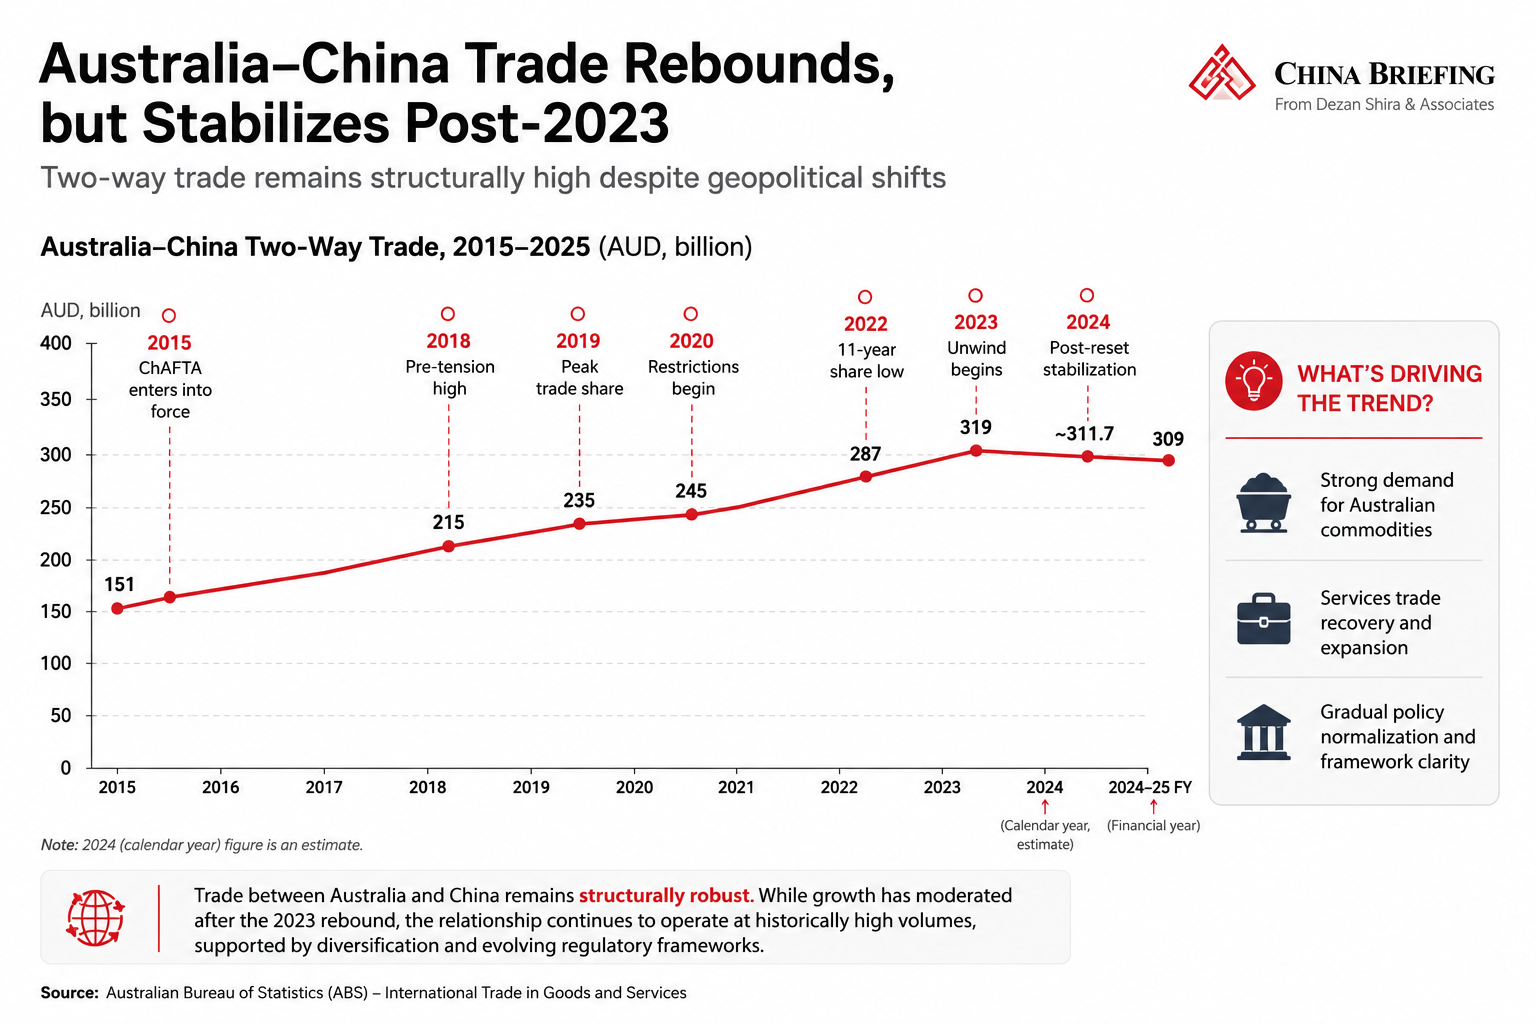
Although early indicators for 2026 suggest slightly softer values due to commodity price normalization, overall volumes remain robust. A working estimate of around AUD 300 (US$213.40 billion) reflects price moderation rather than demand contraction, supported by recovering services and stable export flows.
This reinforces a key point for investors: China remains Australia’s largest trading partner, but the relationship is now less binary and more diversified across sectors.
Australian export composition: Concentration with gradual diversification
Australia’s export structure to China continues to be anchored by natural resources, particularly iron ore, which accounts for over half of exports. Other key categories include liquefied natural gas, coal, and education-related travel.
However, the composition tells a more nuanced story than before:
Education services have re-emerged as a major growth pillar;
Tourism flows have rebounded to record levels; and
Agricultural exports, while fragmented in data, remain strategically significant.
Rather than a single-channel dependency, exporters are increasingly operating across multiple commercial tracks, including commodities, services, and premium consumer goods.
Australia–China Two-Way Trade, 2015-2025 (AUD, billion)
Category
(AUD, billion)
Share of exports to China
Iron ore
104.8
>55%
LNG
20.9
~11%
Education-related travel services
12.7
~7%
Coal (thermal + metallurgical)
12.5
~7%
Gold
~7
~4%
Lithium spodumene concentrate
~5
~3%
Beef, wine, barley, dairy, lobster (combined)
~6
~3%
Other
balance
~10%
Source:
Investment trends: Selective engagement over expansion
Foreign direct investment remains the most constrained dimension of the relationship, but the trend is better described as selective restructuring rather than decline.
China’s FDI stock in Australia at approximately AUD 36 billion (US$25.60 billion) by end-2024, with new investment continuing at lower but steady levels. Importantly, the composition of investment has shifted:
From large-scale acquisitions;
Toward greenfield projects, minority stakes, and joint ventures;
This reflects both regulatory changes and evolving investor strategies.
(implemented since May 1, 2024) applies a risk-based approach, accelerating approvals for low-risk sectors while tightening scrutiny in areas such as:
Critical infrastructure;
Critical minerals; and
Sensitive data and technologies.
For foreign investors, this means opportunities remain viable, but deal structuring is now critical.
Expanding policy ecosystem beyond bilateral ties
A defining feature of the 2026 landscape is the expansion of Australia’s external economic framework. Rather than replacing China, policymakers are building complementary channels to reduce overdependence.
Key developments include:
Ongoing review of ChAFTA to improve market access;
The , which opens near-zero tariffs for most goods;
The , supporting strategic supply chains; snf
The , enhancing project bankability.
Collectively, these initiatives create a multi-layered trade and investment environment, where engagement with China is supplemented (not replaced) by alternative partnerships.
Key investment and trade sectors
Critical minerals: Opportunity within structural constraints
Critical minerals illustrate both the strengths and limitations of the current model.
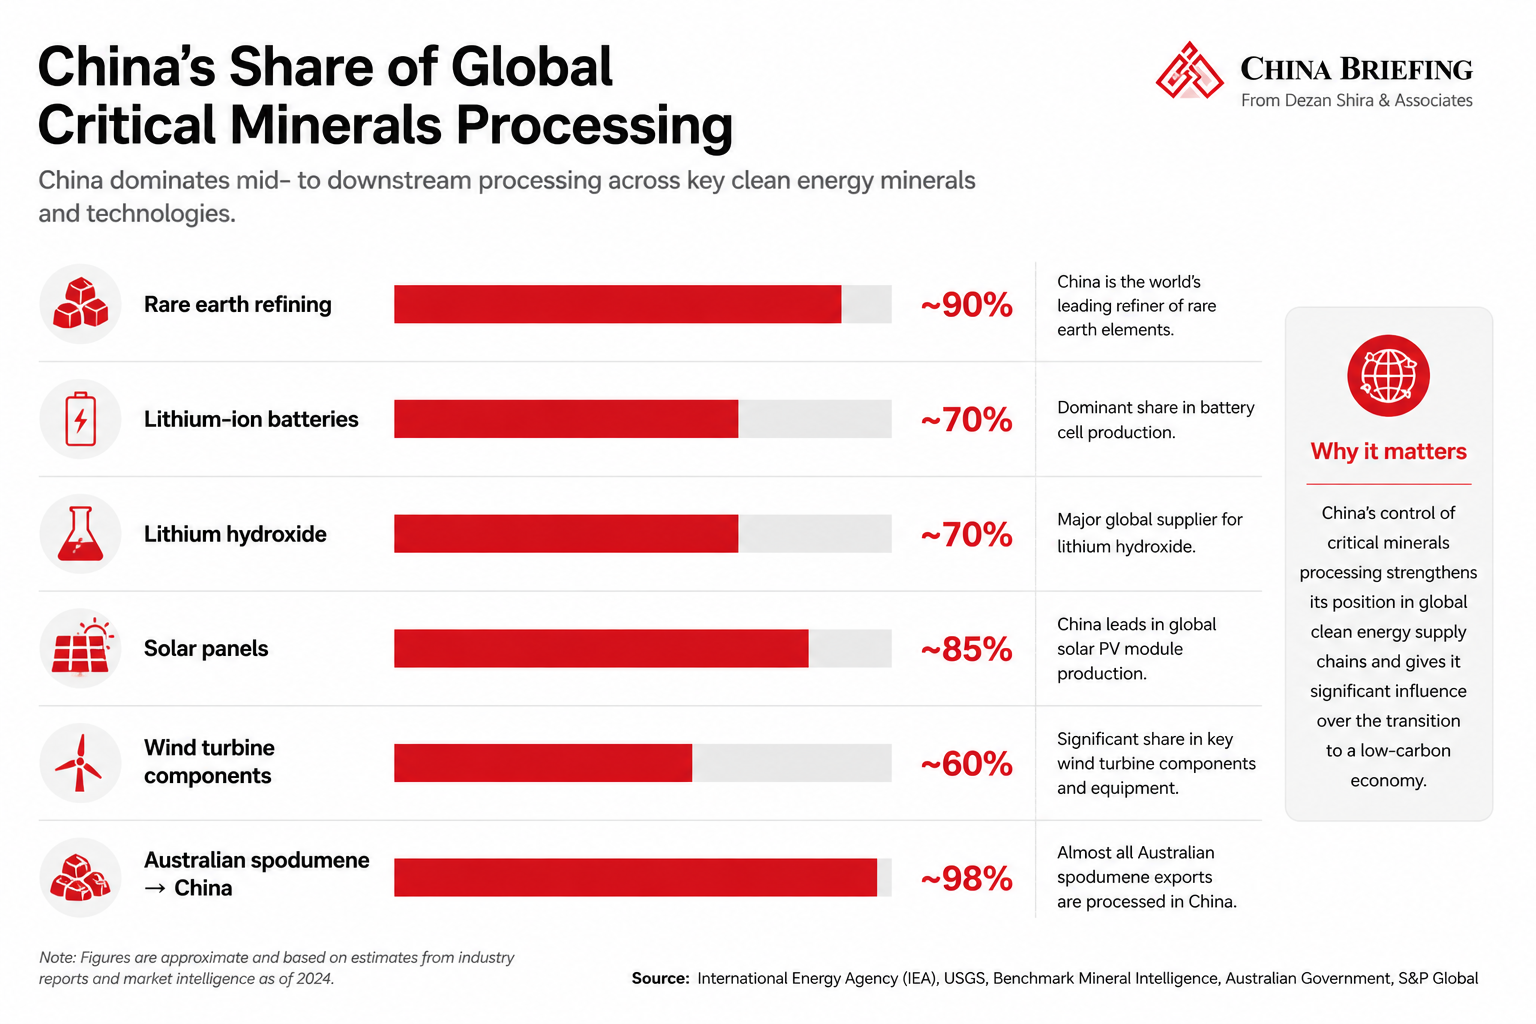
Australia remains a leading upstream supplier, while China dominates processing capacity, including:
Around 70 percent of global refining across key minerals; and
Up to 90 percent in rare earth processing.
This creates a structural dependency, particularly in lithium and clean-tech supply chains.
However, Australia is actively developing midstream capabilities through:
Tax incentives;
Public financing; and
Strategic offtake agreements.
The result is a gradual shift toward a more balanced value chain, although economic viability still depends heavily on policy support.
Agriculture and services: Renewed growth drivers
Agricultural trade has shown clear signs of normalization following the removal of earlier restrictions:
Wine exports resumed in 2024;
Meat export suspensions were lifted; and
Lobster trade reopened.
At the same time, new safeguards,such as quotas on beef imports, indicate a transition toward managed market access rather than unrestricted trade.
Australia–China Two-Way Trade, by Category
Product
2025 result
2026 risk/event
Investor implication
Beef
1.545Mt record; China 273kt
Quota 205kt; 55% out-of-quota tariff
Diversification mandatory
Wine (TWE)
Penfolds +7.3%; +21% China depletions Oct
−40% H1 FY26 EBITS guidance
Channel restructuring underway
Dairy
A$987M China exports
Final tariff elimination 1 Jan 2026
Premium positioning vs NZ
Barley
73.1% reconcentrated to China
Saudi Arabia / Vietnam fall back
Single-buyer risk returns
Apples
<1% exports; A$680M domestic
Mainland market access from May 2026
Greenfield growth runway
Lobster
Ban lifted Dec 2024
Tropical Rock Lobster (Torres Strait) still impeded
97.7% pre-ban concentration risk
In parallel, services have emerged as a major strength:
has returned to high levels;
Visitor arrivals one million annually; and
China remains the largest source of international students in Australia.
This reinforces the shift toward a broader economic relationship that includes people flows, services exports, and consumption-driven demand.
Green economy, clean tech, EVs
Chinese electric vehicle (EV) imports have rapidly become one of the most dynamic components of Australia’s automotive market, with China’s BYD emerging as the leading driver of this shift. The company 100,000 cumulative deliveries in Australia by April 2026 (less than three and a half years after entering the market) highlighting both strong consumer uptake and the scalability of its distribution model.
This rapid expansion is reflected in broader market dynamics. Battery electric vehicle (BEV) adoption continues to accelerate, supported by competitive pricing, expanding model availability, and improvements in charging infrastructure. In February 2026, Chinese brands for more than half of Australia’s BEV market, with BYD models and newer entrants such as Zeekr gaining traction alongside established players.
Solar, batteries, and grid-scale renewables
China’s role in global clean-energy supply chains remains dominant, and this influence is clearly visible in Australia’s renewable energy sector. Chinese manufacturers supply an estimated 85 percent of global solar panels, 70 percent of lithium-ion batteries, and approximately 60 percent of wind turbine components, making them integral to project development across Australia.
Domestic investment in clean energy has also strengthened. Australia recorded AUD 12.7 billion (US$9.03 billion) in , including AUD 9 billion (US$6.40 billion) in new large-scale generation commitments, the highest level since 2018.
Find Business Support

Despite this strong activity, formal Chinese outbound direct investment (ODI) in Australia’s renewable sector remains relatively limited. In 2024, only one transaction valued at AUD 183 million (US$130 million) was recorded.
Hydrogen: Cooperation under pressure
Hydrogen development has emerged as a more complex and uncertain area ofAustralia–China cooperation. Several high-profile projects have faced setbacks due to shifting policy environments and challenging project economics. At the same time, cooperation has not disappeared but is evolving into more targeted forms. In 2025, Fortescue a US$2 billion green financing package from Chinese banks, representing one of the largest sustainable finance transactions between the two countries. The company has also partnered with Taiyuan Iron and Steel, a subsidiary of China Baowu, to develop hydrogen-based, plasma-enhanced green iron technology, with an industrial trial line targeting 5,000 tonnes of output.
This points to a narrower but strategically important cooperation niche: industrial decarbonization, particularly in iron and steel production. Initiatives such as , (MoU) with Chinese partners, and government-led platforms like the suggest that climate-related industrial cooperation remains one of the most viable areas for sustained engagement.
Here, hydrogen is not an independent growth driver. Rathher, its role is tied to wider decarbonisation efforts, where business incentives and emissions targets are converging.
Lithium operations under Chinese ownership
Chinese companies continue to play a significant role in Australia’s lithium sector, particularly through joint ventures, equity participation, and long-term offtake agreements.
Find Business Support
Tianqi Lithium, for example, a 51 percent stake in Talison Lithium Energy Australia (TLEA), alongside IGO, and is involved in the Greenbushes mine, one of the world’s largest lithium operationsm, alongside Albemarle. The company has also invested in downstream processing capacity, although operations at the Kwinana refinery have faced interruptions.
has similarly established a diversified presence in Australia through investments in Pilbara Minerals, Core Lithium, and several smaller projects, as well as through long-term supply agreements.
While Chinese participation remains substantial, the structure of involvement has evolved. There is a gradual shift away from majority ownership toward joint ventures, minority stakes, and offtake-linked financing, reflecting both regulatory considerations and risk management strategies. Overall, Chinese involvement in Australia’s lithium sector remains critical to project development and global supply chains, even as ownership structures become more balanced and subject to closer regulatory oversight.
Comparative sector snapshot
Variable
Critical Minerals
Premium Agriculture
Green Economy / EVs
Bilateral exposure
~A$5–8bn lithium spodumene + REE; 49 mining + 29 processing projects
~A$6bn beef/wine/dairy/barley + apples opening 2026
EV imports dominant; renewable FDI modest (A$183m 2024)
Growth profile
Moderate-high (CMPTI from 2027; A$18bn export target)
Moderate; quota-constrained
High on import side; slow on Australian green-export side
Risk level
High (Chinese processing dominance; FIRB divestment)
Medium (quotas + NTBs + grey-market crackdown)
Medium-high (FIRB scrutiny; supply-chain concentration)
Preferred Chinese entry mode
Minority equity + offtake; greenfield processing-adjacent
CBEC / O2O distribution; brand JV
Greenfield distribution (BYD model); equipment supply
Key 2026 policy event
CMSR operational H2 2026; CMPTI from 1 July 2027
Beef quota 1 Jan 2026; dairy 0% 1 Jan 2026; apples May 2026
EU FTA tariff-free critical minerals from March 2026
Lobster
Ban lifted Dec 2024
Tropical Rock Lobster (Torres Strait) still impeded
97.7% pre-ban concentration risk
Implications for investors
The China-Australia trade reset marks a transition from unrestricted expansion to structured, policy-aware engagement.
For investors, the key strategic considerations include:
Structuring investments to align with regulatory priorities;
Diversifying exposure across markets and sectors;
Leveraging new policy frameworks and trade agreements; and
Expanding into services and value-added segments.
The relationship has developed into a high-volume trade corridor, with rules and opportunities that continue to evolve.
Conclusion
Find Business Support
The 2026 phase of China–Australia economic engagement is becoming more complex, but it is also offering clearer avenues for investment. Trade flows remain substantial, services are expanding, and policy frameworks are gradually opening new pathways for growth.
For businesses, success will depend on adjusting to this evolving landscape rather than expecting a return to past conditions. Scale, diversification, and regulatory strategy are all becoming central considerations.


Whether launching, restructuring, or expanding, we ensure our clients benefit from coordinated input across legal, HR, tax, and financial teams. From startup to exit, our advisory scales with your business—designed to meet both immediate needs and long-term goals.
Partner
About Us
China Briefing is one of five regional Asia Briefing publications. It is supported by Dezan Shira & Associates, a pan-Asia, multi-disciplinary professional services firm that assists foreign investors throughout Asia, including through offices in Beijing, Tianjin, Dalian, Qingdao, Shanghai, Hangzhou, Ningbo, Suzhou, Guangzhou, Haikou, Zhongshan, Shenzhen, and Hong Kong in China. Dezan Shira & Associates also maintains offices or has alliance partners assisting foreign investors in Vietnam, Indonesia, Singapore, India, Malaysia, Mongolia, Dubai (UAE), Japan, South Korea, Nepal, The Philippines, Sri Lanka, Thailand, Italy, Germany, Bangladesh, Australia, United States, and United Kingdom and Ireland.
For a complimentary subscription to China Briefing’s content products, please click here. For support with establishing a business in China or for assistance in analyzing and entering markets, please contact the firm at china@dezshira.com or visit our website at www.dezshira.com.