
As the Australian market holds steady, awaiting key inflation data, the broader sentiment remains cautious amid global economic shifts and volatile commodity prices. In this environment, identifying promising small-cap stocks requires a keen eye for potential growth drivers and resilience in challenging conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In AustraliaNameDebt To EquityRevenue GrowthEarnings GrowthHealth RatingFiducian GroupNA9.85%10.78%★★★★★★JoyceNA7.70%7.34%★★★★★★Euroz Hartleys GroupNA-2.67%-37.02%★★★★★★Focus MineralsNA75.66%75.61%★★★★★★WAM Strategic ValueNA-9.74%30.51%★★★★★★SDI14.65%8.06%12.66%★★★★★☆Zimplats Holdings3.35%-10.45%-46.73%★★★★★☆AMCILNA2.99%1.18%★★★★★☆Australian United Investment6.80%2.27%1.31%★★★★☆☆SkinkandyNA26.91%31.30%★★★★☆☆
Let’s explore several standout options from the results in the screener.
Simply Wall St Value Rating: ★★★★☆☆
Overview: Australian United Investment Company Limited is a publicly owned investment manager with a market capitalization of A$2.38 billion.
Operations: The primary revenue stream for Australian United Investment comes from its investments, generating A$60.01 million.
Australian United Investment, a smaller player in the investment landscape, has shown disciplined financial management over recent years. Its debt to equity ratio decreased significantly from 11.9% to 6.8%, indicating prudent leverage control. The company’s interest payments are comfortably covered by EBIT at a multiple of 27, reflecting robust earnings quality. Despite an annual earnings growth of only 1.3% over five years and not outpacing the industry average last year, AUI remains profitable with positive free cash flow around A$51 million as of June 2025. However, shareholder dilution in the past year might concern some investors looking for stability in ownership stakes.
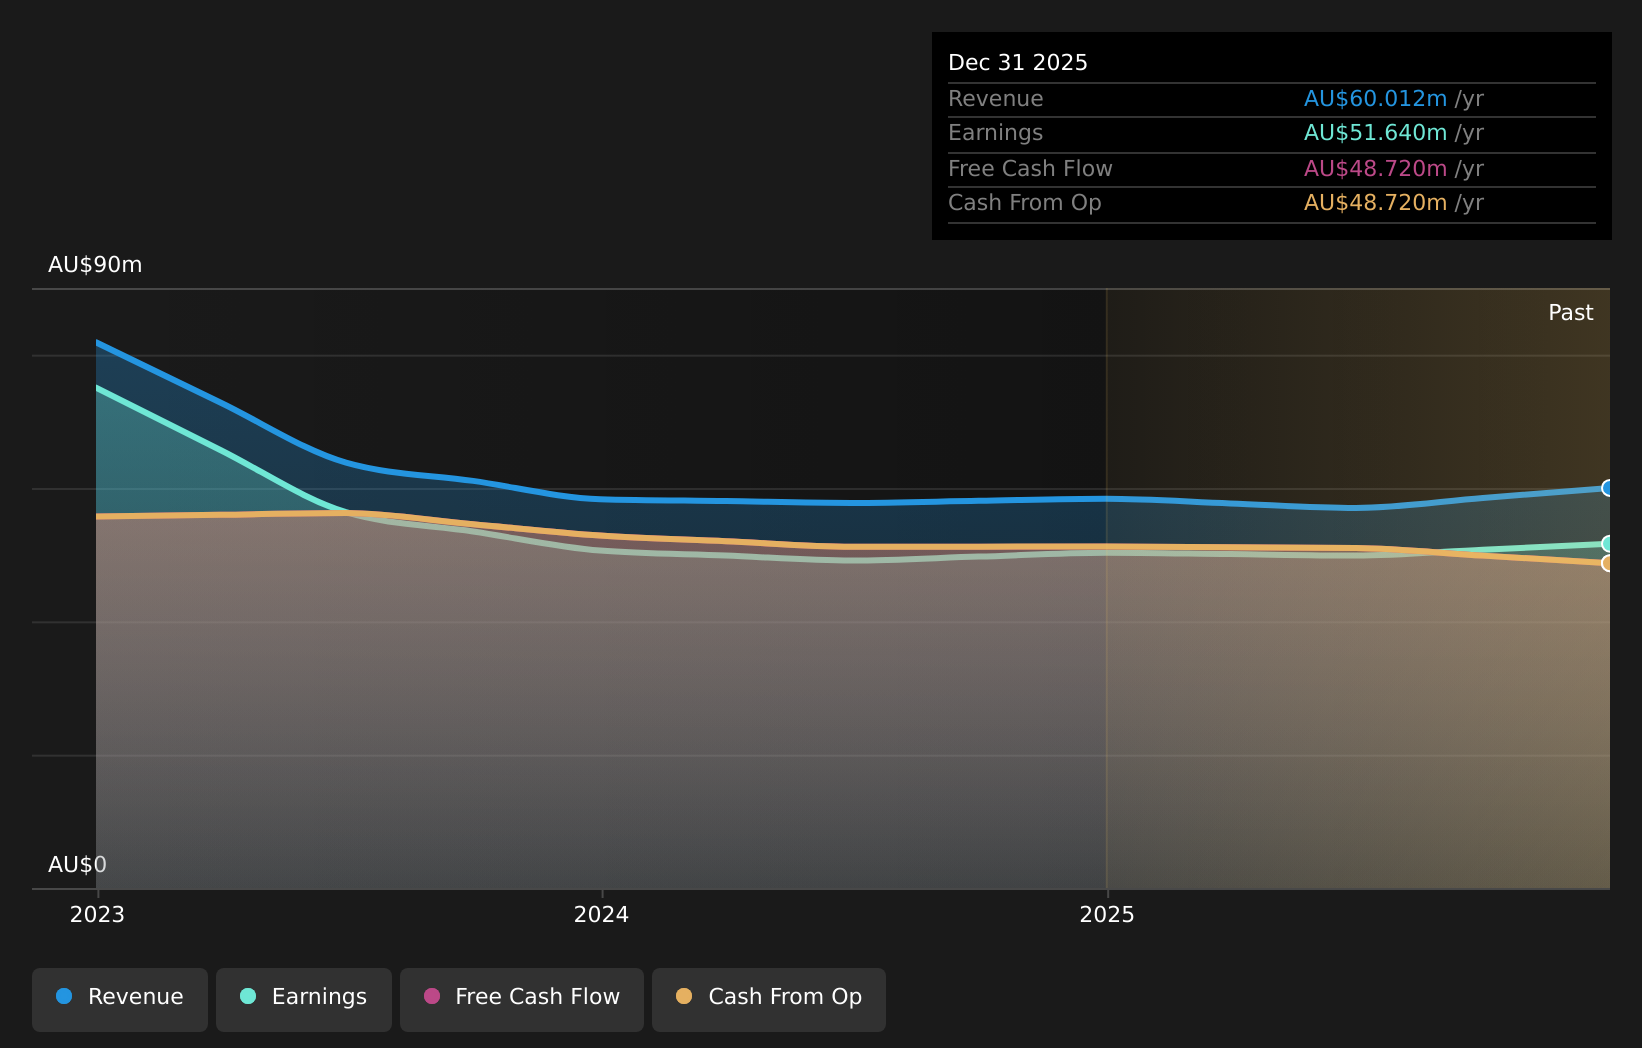 ASX:AUI Earnings and Revenue Growth as at May 2026
Simply Wall St Value Rating: ★★★★★☆
Overview: Emeco Holdings Limited provides surface and underground mining equipment rental and related services in Australia, with a market capitalization of A$553.08 million.
Operations: Emeco Holdings generates revenue primarily from equipment rental (A$657.49 million) and workshops (A$271.38 million). The company exhibits a net profit margin trend worth noting, with the latest figures reflecting its operational efficiency.
Emeco Holdings, a small Australian player in the equipment rental industry, showcases robust financial health with its interest payments well covered by EBIT at 6.3 times. The company’s debt to equity ratio has impressively decreased from 50.4% to 33.1% over five years, reflecting prudent financial management. Despite trading at a notable discount of 41.1% below estimated fair value, Emeco’s earnings grew by 20%, outpacing the industry average of -10%. With recent leadership changes and a strategic shift towards ESG-compliant equipment and digital services, Emeco is poised for growth despite challenges in adapting to new industry trends.
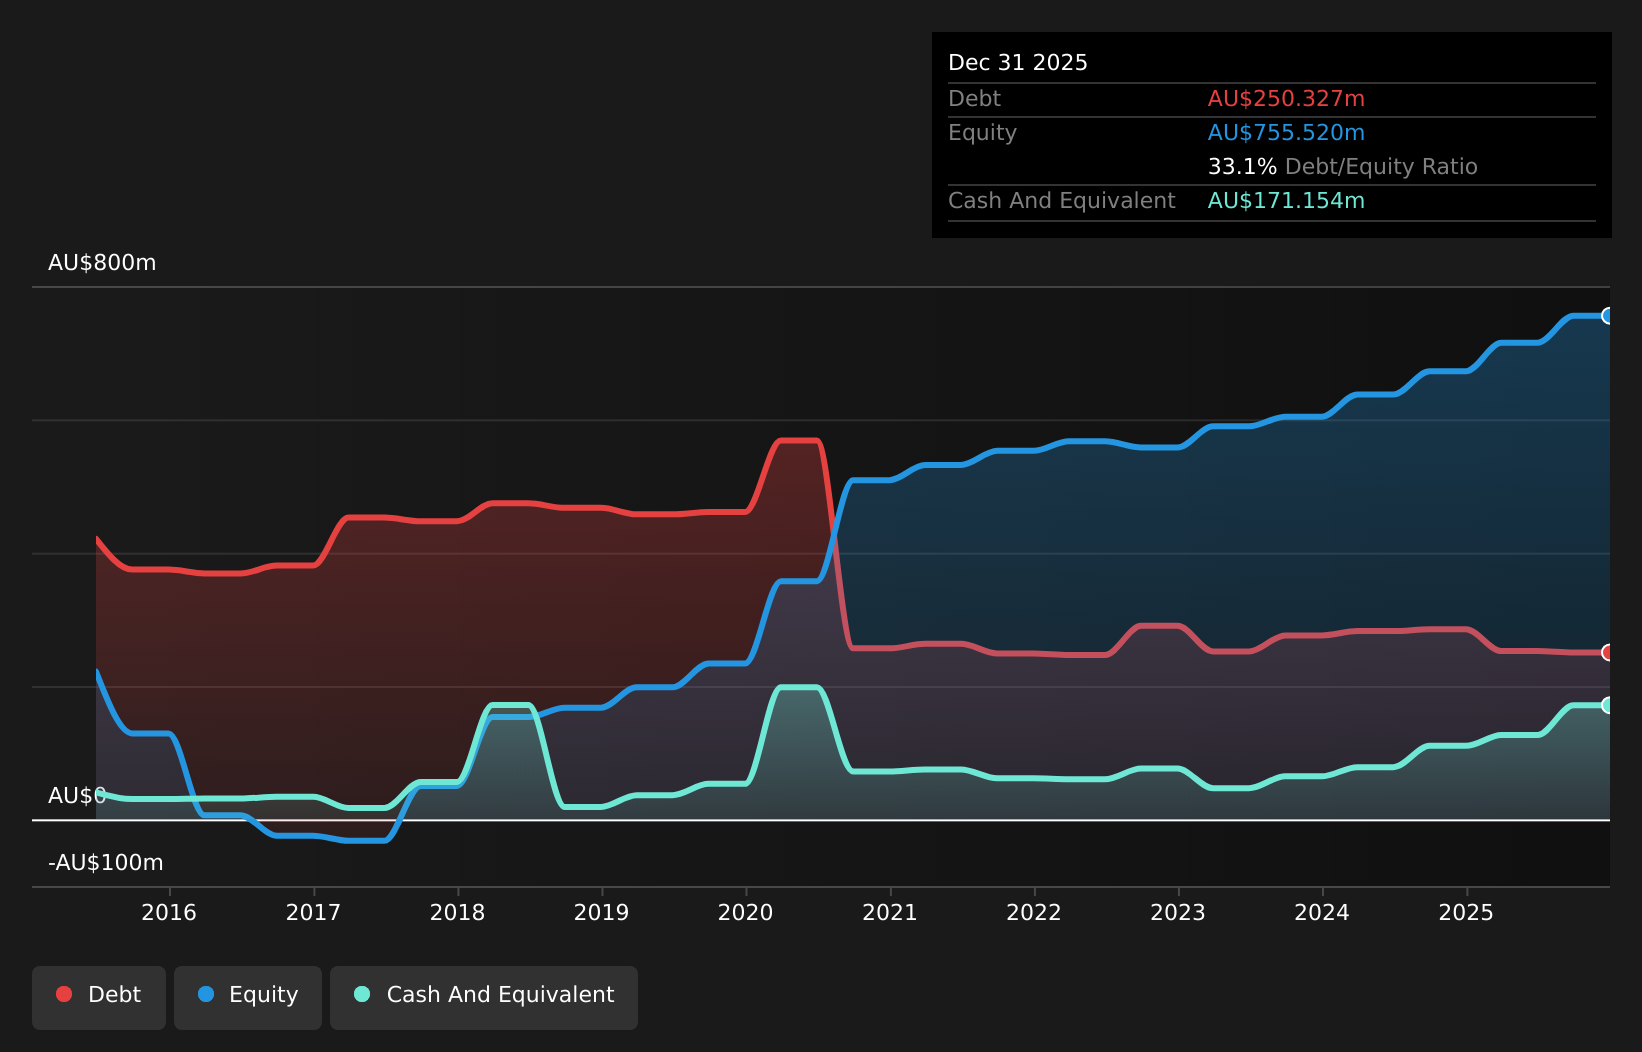 ASX:EHL Debt to Equity as at May 2026
Simply Wall St Value Rating: ★★★★★★
Overview: Jupiter Mines Limited is an independent mining company based in Australia, primarily involved in manganese mining operations in South Africa, with a market capitalization of A$540.61 million.
Operations: Jupiter Mines generates revenue primarily from its manganese mining operations in South Africa, with reported earnings of A$9.45 million.
Jupiter Mines, a small player in the Australian mining scene, showcases a mixed bag of financial metrics. With no debt over the past five years and high-quality earnings, it stands out for its fiscal prudence. However, significant insider selling in recent months raises eyebrows. The company is free cash flow positive with A$4.47 million noted recently but has seen earnings decline by 10% annually over five years. Its P/E ratio of 12.8x suggests it’s undervalued compared to the broader market at 17.1x, offering potential value despite underperforming industry growth rates recently at just 9%.
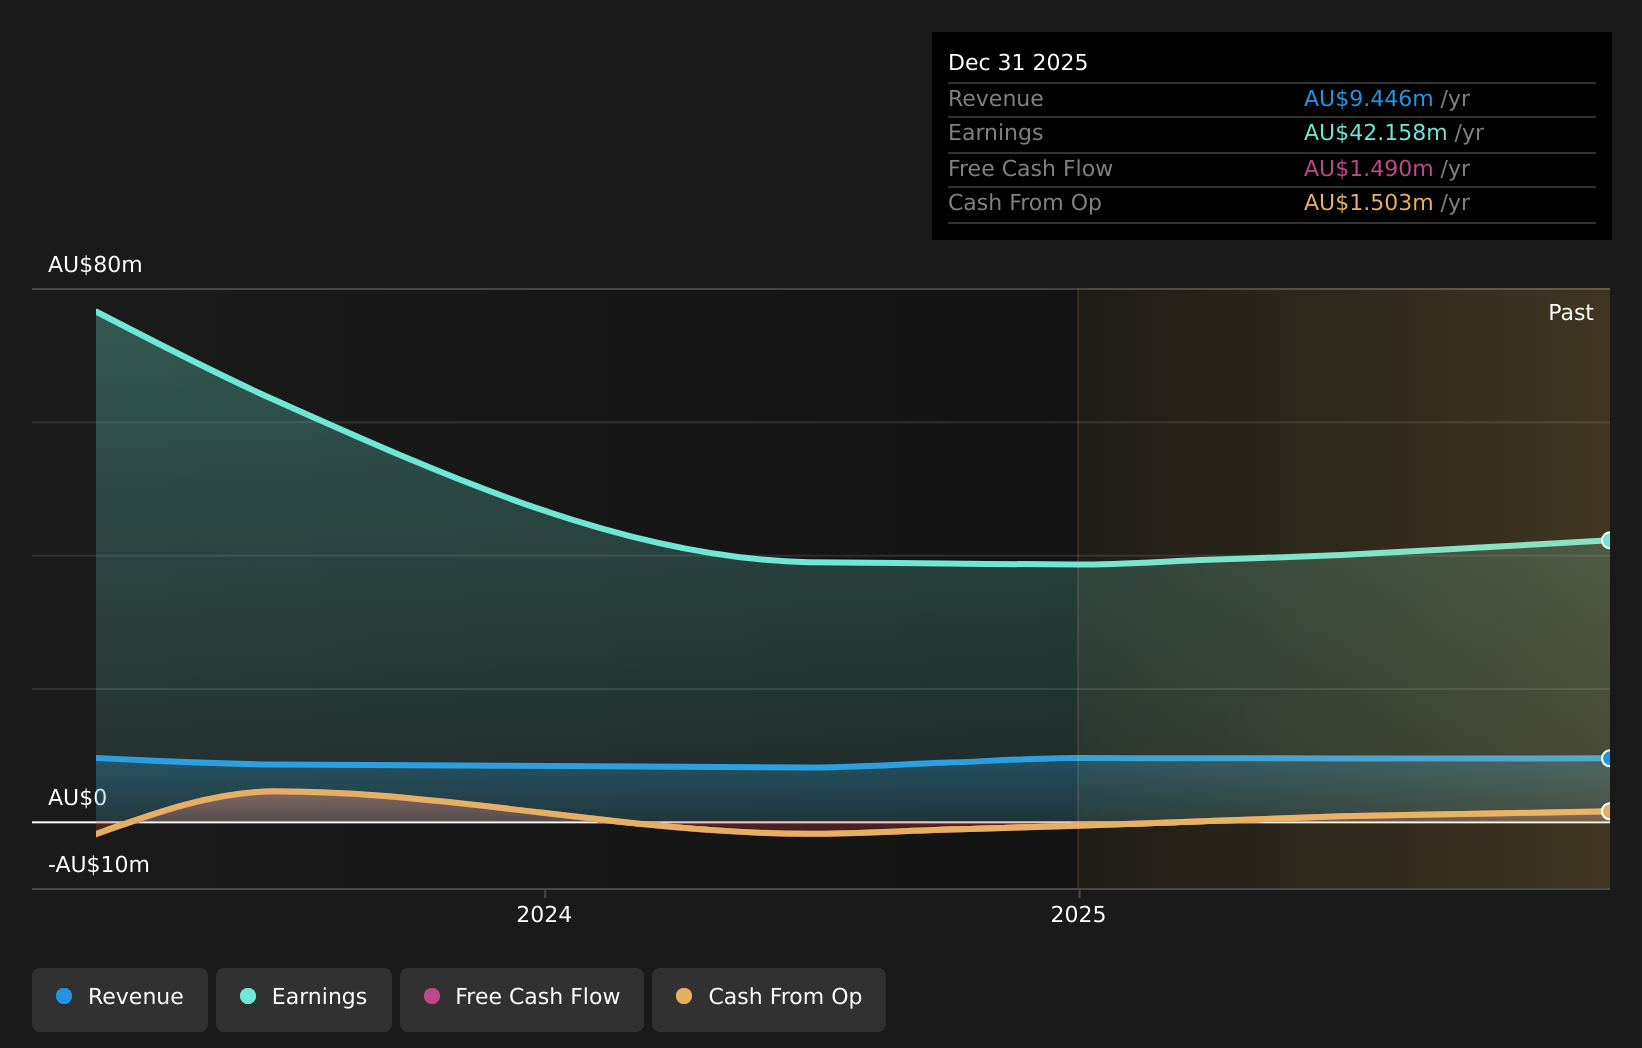 ASX:JMS Earnings and Revenue Growth as at May 2026Key TakeawaysSeeking Other Investments?
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Emeco Holdings might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com