
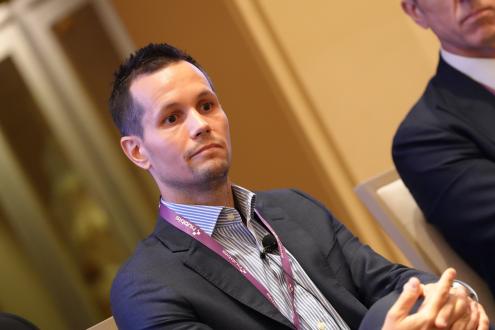
Product comparisons in high-net-worth insurance tend to be framed as contests. On a panel in Singapore last month, Christopher Tanchou made the case that the question is unusually posed: the right answer for most families is a combination, and it can only be identified after four fairly unglamorous questions about assets, tax residency, existing protection and reporting.
At the recent Hubbis HNW Insurance Summit in Singapore, a session chaired by Roger Chi, Managing Partner at 1291 Group, examined how policies are designed, underwritten and maintained over the long term. Christopher Tanchou, Head of Business Development Asia at Swiss Life Global Solutions, addressed the practical distinction between PPLI and variable universal life, the state of reinsurance capacity, and what advisers can do to keep a PPLI structure defensible as clients move between jurisdictions.
Key Takeaways
Start With the Client, Not the Product: Tanchou set out four diagnostic questions, covering asset type, tax residency, existing protection and reporting obligations, before any solution is proposed.
Speed of Distribution Is a Real Benefit: He pointed to the time probate can take, during which a family may have no access to assets, as an argument for holding investments within a policy.
Liquidity Helps Determine the Fit Between PPLI and VUL: Where a family needs cash to settle liabilities, he sees VUL as the stronger fit; where the objective is structuring and reporting simplification, PPLI.
Capacity Is Less of a Constraint Than It Was: In his view the reinsurance market is well resourced, and treaty arrangements now involve several reinsurers rather than one.
Control Is a Key Defensibility Question: For certain markets he recommends third-party discretionary management of the underlying assets.
A Specialist Mandate
Tanchou leads business development for Asia at Swiss Life Global Solutions, working through brokers and other business partners. He has spent more than a decade with the group across Zurich, Luxembourg and Singapore.
He described the Asian proposition as deliberately focused on high net worth individuals, with VUL forming a core part of the regional business across selected markets.
Four Questions Before Any Product
Asked how he guides clients between PPLI and VUL, Tanchou began by rejecting the premise of a single answer. “First of all, I don’t believe that there is only one solution that’s possible,” he said. “You can actually consider a spectrum of different solutions depending on client situation, client needs.”
He then set out the sequence he works through. The first question concerns the assets themselves. “What kind of assets do the clients have? Cash rich, cash poor? Is he having investments? What kind of investments?”
The second is tax residency. “How is it taxed currently? Is there a better way to actually hold those investments and the income through different structures? Is insurance actually valuable or not?” The final clause matters: he framed insurance as one possible answer rather than the assumed one.
Third comes existing protection and planning. “Is it already insured? Is it protected? Has he got any succession planning around these assets and wealth?” Fourth are reporting obligations.
Only after working through those, he said, does a recommendation take shape, and it is rarely singular. “When you start looking at all these elements, then you will end up probably giving several solutions, not only one.”
The Probate Argument
One of the clearest practical benefits he identified concerns timing rather than tax. Probate, he noted, can take a considerable period to complete, and during that time the family may have no access to the assets in question.
Where investments are held within an appropriately structured insurance policy with the relevant beneficiary arrangements, proceeds may be distributed outside the ordinary estate-administration process and can therefore reach beneficiaries more quickly. Tanchou put the point more directly: “If you put those assets into an insurance policy, whether it’s a PPLI or VUL policy, you ensure that the distribution is actually done much faster,” he said.
It is a straightforward point that is easily lost in discussion of tax treatment, and it applies to both structures he works with.
PPLI or VUL: What Does the Policy Need to Do?
Tanchou’s distinction between the two turns on whether the family needs additional money at the point of death, or a better way of holding what it already has.
“It just depends on how much insurance cover is requested by the client,” he said. Where the client has no existing cover and needs liquidity to settle taxes, inheritance costs or other liabilities, his view was clear: “VUL will definitely be a very good solution because it provides additional liquidity on top.”
“Where the objective is wealth structuring, succession planning, and long-term continuity for the family, PPLI can be a very effective tool, and it can also help simplify certain administrative and reporting processes along the way.”
Retention, Demystified
Asked to explain some of the underwriting vocabulary that advisers hear without necessarily understanding, Tanchou focused on retention, and on a perception, he thinks is out of date.
There is a view in the market, he said, that carriers hold substantial retention and that this makes cover easier or cheaper to obtain. “Maybe that could be a little bit closer to truth about 10 to 20 years ago,” he said. “But today the reinsurance market is extremely well resourced.”
He described cover at levels of 15 million, 25 million and 100 million dollars as unremarkable in the applications he sees over the last five years. Retention, in insurance terms, is the amount of risk a carrier keeps on its own balance sheet. Separate treaty arrangements and automatic binding limits determine how much additional risk can be ceded to reinsurers without referring each case back for individual approval. Those treaty arrangements, he noted, increasingly involve not one reinsurer but two, three or four.
His conclusion was that the market has become more accommodating. “I find that the market is a lot more supportive of customers when trying to get more coverage as opposed to five or 10 years” ago, he said, which “bodes well for a lot of the advisers”.
Making PPLI Defensible
On the scrutiny PPLI attracts, Tanchou acknowledged the question being asked. Because VUL carries substantial insurance cover, it tends not to be queried. PPLI attracts more debate, with some in the market asking whether it is genuinely a life insurance policy.
His response drew on the product’s history. PPLI has been used for more than 30 years in Europe and the United States, he said, and he pointed to that history as evidence of the structure’s durability. He also pointed to increasing regulatory attention in Asia. Taiwan, for example, has expressly addressed PPLI in guidance concerning its controlled foreign company regime, including the question of whether a policyholder retains substantive control over underlying assets. Tanchou also said Indonesia had referred to PPLI some years earlier. “It shows that the solution is actually understood,” he said.
Swiss Life works with lawyers across the region, he added, to confirm that its policies are treated as life insurance in the targeted markets. In the covered markets, he said, none has taken the position that PPLI is not a life insurance policy, given that there is insurance cover, a life insured and a death benefit payable.
Where a policy could be challenged, in his account, the pressure point is control. He said certain governance measures may be needed to reduce the risk of a structure being challenged. “Under certain circumstances, we would suggest only to have the policy managed by a third-party asset manager,” he said, distancing the policyholder from investment decisions. Whether any given structure achieves its intended treatment will, of course, depend on the client’s circumstances and on local advice.
A Policy That Travels
His closing theme was duration. “It’s a solution that follows you throughout your entire journey,” he said. “It’s not something that you buy just five years, 10 years, it’s long term.”
That has implications when a client changes residence. “If you’re moving from one country to another, it’s always very, very important to talk with your adviser, or your insurance broker, with the insurance company,” he said, so that the policy continues to deliver the intended advantages and remains aligned with local requirements. Swiss Life, he said, follows this carefully to ensure policies remain compliant.
Diagnosis Before Prescription
The discipline Tanchou described is diagnostic rather than promotional. Ask what the client owns, where they are taxed, what is already protected and what must be reported, and the shortlist assembles itself. Ask which product is better, and the answer is unanswerable.
For advisers, the useful implication is that a mobile client’s policy is not a completed transaction. It is a position that needs reviewing each time the family’s map changes.