
Opinion
 Bec WilsonMoney contributor
September 19, 2026 — 5:00am
September 19, 2026 — 5:00am
Save
You have reached your maximum number of saved items.
Remove items from your saved list to add more.
AAA
Have you ever been at a weekend barbecue listening to Robert in the corner tell you about how he really could retire now, at 54, and head off caravanning around the country. You nod politely, quietly shudder, look inward and wonder what you’re doing wrong.
Until five minutes ago, you thought you were doing reasonably well.
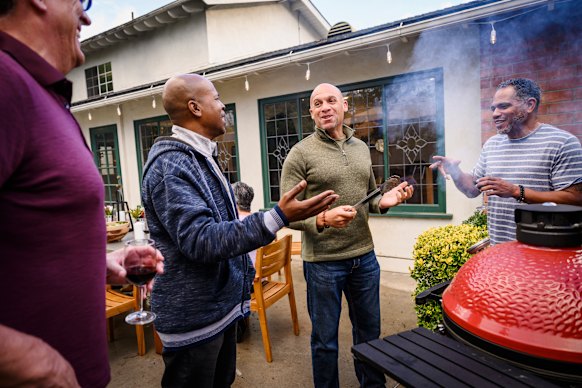 The trouble with barbecue advice is that a useful conversation can quickly morph into one-upmanship.Getty Images
Now Robert might legitimately have his retirement sorted. Good on him if he does. But you haven’t seen his numbers, you don’t know what he’s planning to live on, and you have no idea how he reached that conclusion. You just heard the announcement and now, for some reason, you’re using it to judge your own progress.
That’s the trouble with barbecue advice: a useful conversation can quickly morph into one-upmanship. Who’s made the most, whose super fund is better, who can retire first. Meanwhile, the person wanting to ask a basic question decides they’d rather not advertise what they don’t know.
The bigger problem with giving weight to someone’s barbecue answer is it doesn’t help you work out your own. The Understanding Modern Australia Report, released this week, commissioned by life insurer TAL and produced by McCrindle, found that 33 per cent of respondents would be extremely or very likely to act on financial advice from family and 24 per cent from friends.
Paid, in-person advisers came in at 42 per cent, while AI platforms came in at 18 per cent. These are stated intentions – not what people actually did. But they do show the importance of a quality barbecue conversation about retirement.
Retirement is particularly terrible territory for copying someone else’s homework.
So my goal is to make more Australians become a retirement expert at their next barbecue.
In fact, the No. 1 thing people tell me they’re going to do after completing one of our retirement courses is talk to their friends and family about what they’ve learnt. I love that, because they’re not walking away wanting to tell everyone what to do. They’ve finally got their heads around things they didn’t understand before and they want the people they care about to understand them, too.
There’s a world of difference between, “You should have done what I did,” and, “I didn’t understand this either until recently – let me show you what I learnt.” One shuts the conversation down and makes you wish you’d never asked. The other gets it started. We need more of the second kind.
Related Article
The TAL and McCrindle research suggests there’s an appetite for learning: 86 per cent of Australians said that growing their financial knowledge was important to them, even though fewer, 58 per cent, reported taking steps to improve it in the prior year.
That’s quite a gap – between knowing you want to learn and actually doing something about it. And maybe part of the problem is that we make “financial knowledge” sound much harder than it needs to be. You don’t need to become an expert in investment markets or understand every rule in the superannuation system before you can make progress.
You can start with decisions that are right in front of you.
If you’re in your fifties, that might be working out what you actually spend now, and what you think you’ll want to spend in retirement. It might be understanding if you can afford to contribute a little more to super in the run-up to your retirement. Or it might be understanding when you can access your super, how the Age Pension works and whether you could afford to work a little less before you stop working altogether.
It might be ringing your super fund and asking them to explain something you never really understood. Then share what you learnt.
Tell your mate how you finally sat down and worked out what you spend each year. Tell your sister about the calculator that helped you understand how long your super might last. Tell your workmate the three questions you asked your super fund. Tell your adult kids the thing you wished someone had explained to them when you were their age.
This is useful barbecue financial advice. Not necessarily giving someone the answer but helping them ask a better question.
Of course, some serious responsibility comes with this.
If you’re going to share something about money, understand it well enough to explain where it came from and know where someone can check it for themselves. And take serious note of when someone else’s situation differs sufficiently from yours that your answer might not work for them at all.
Related Article
Retirement is particularly terrible territory for copying someone else’s homework.
Two people the same age with the exact same amount of super can have completely different retirement prospects. One might own their own home outright while the other rents. One might live happily on $50,000 a year while the other needs $100,000.
Which brings us back to Robert. Maybe instead of asking him how much he has in super (or trying to guess after the barbecue), or allowing his impending retirement at 54 to trigger a small existential crisis, ask him a different question. “How did you work out that you could afford to retire?”
Now, that might spark an interesting conversation. Maybe Robert has spent two years tracking his expenses, has tested out living with his partner on his retirement budget, and has modelled what might happen if markets fall in the first five years. And perhaps he’s factored in some juicy travel expenses for his first 15 years, or thought through how he’s going to downsize his home and living expenses.
Or he may look startled and admit he hasn’t really worked any of that out yet. Either way, the barbecue just got more useful. And it might also make others around the table feel more confident asking questions, too.
If we become this sort of barbecue expert, we’ll all be better off.
Bec Wilson is author of the bestseller How to Have an Epic Retirement and the newly released Prime Time: 27 Lessons for the New Midlife. She writes a weekly newsletter at epicretirement.net and hosts the Prime Time podcast.
Advice given in this article is general in nature and is not intended to influence readers’ decisions about investing or financial products. They should always seek their own professional advice that takes into account their own personal circumstances before making any financial decisions.
Expert tips on how to save, invest and make the most of your money delivered to your inbox every Sunday. Sign up for our Real Money newsletter.
Save
You have reached your maximum number of saved items.
Remove items from your saved list to add more.
 Bec Wilson is the author of How To Have An Epic Retirement and writes a weekly newsletter for pre- and post-retirees at epicretirement.net.From our partners