
Home loan rates under 5 percent are “on borrowed time”, the head of one mortgage advice firm says, as bond yields push up around the world.
It is usually the case that shorter-term home loan fixes are driven more by movements in New Zealand’s official cash rate (OCR). Longer fixes are more often determined by international factors.
Squirrel chief executive David Cunningham said a recent increase in US bond yields was likely to be felt primarily in the three- to five-year home loan fixes.
He said while one- and two-year rates were likely to remain the “battleground” for banks, any home loan below 5 percent was probably on borrowed time as domestic and international wholesale rates increased.
At the moment, the big banks are advertising six-month and one-year rates below 5 percent.
Two-year rates are between 5.29 percent and 5.49 percent.
Infometrics managing director Gareth Kiernan said there had been a 25 to 35 point jump in swap rates between 8 and 17 September, and that was being reflected in the recent round of mortgage rate increases.
“Another jump of about 15 basis points over the last one or two days in bond rates both here and overseas is likely to flow through from swaps into mortgage rates as well over the next couple of weeks if it is sustained.”
Cotality chief property economist Kelvin Davidson said it was probably not the case that bank margins were elevated to the extent that they could afford to absorb a lot of increase in wholesale rates.
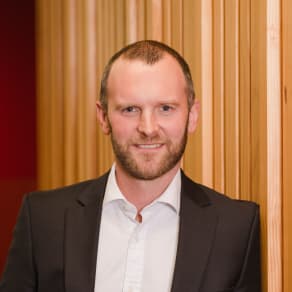
Cotality chief property economist Kelvin Davidson.
SUPPLIED
“There’s perhaps not as much margin as there could be so a rise in input costs would tend to see your output prices go up and that’s probably what we are going to see.”
Banks have already made adjustments to some terms, but some have left the two-year term on hold, or even reduced it. The two-year rate has historically been popular with New Zealand borrowers.
Kiernan said it would be hard to see it stay around its current levels given the pressure on interest rates locally and from offshore.
“There might be a competitive element at play, particularly when one considers the relatively weak state of the housing market and probable lack of demand for borrowing that will be making it difficult for banks to achieve their lending targets.”
Davidson said the term the banks would choose to compete on would vary over time. “Right now the two-year term is looking more competitive but it makes it tricky for borrowers because the two-year rates are higher than the one-year rates, do you take a couple of rolling one-year fixes and hope it turns out better than just taking a two-year fix now?”
Westpac chief economist Kelly Eckhold said two-year rates were likely to settle about 5.5 percent. “The two-year rate is perhaps a bit lower than what it would otherwise be, given the competition. If that passes and you pitch it where the wholesale rate is, it would suggest rates probably have to go up 20, 30 points.”
He said the increases were in line with what was expected but were happening more quickly than forecast.
What happened next would depend on what data came out, he said. “It’s quite volatile in the global interest rate markets at the moment so I don’t think there’s any guarantee that the rates you see today will last. It could be the case that some announcement or piece of information comes out that perhaps causes global rates to fall, in which case the pressure might come off a bit.”
Sign up for Money with Susan Edmunds, a weekly newsletter covering all the things that affect how we make, spend and invest money.