
Carter’s Inc. and Umbro recently launched a limited-edition, soccer-inspired childrenswear collection in the US, featuring country-themed kits for newborns to age 14, priced around US$24–US$28 and sold in stores and online. This collaboration links Carter’s core focus on early childhood with Umbro’s soccer heritage, giving Carter’s a way to tap global football enthusiasm through sport-themed apparel for kids. We’ll now examine how this limited-edition soccer collaboration with Umbro could influence Carter’s broader investment narrative and growth drivers.
The future of work is here. Discover the 33 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
Carter’s Investment Narrative Recap
To be comfortable owning Carter’s, you need to believe its core baby and kids franchise can translate into steady earnings, even with slower forecast revenue growth and lower margins. The Umbro partnership fits that story but is unlikely to change the near term picture on its own, where the key catalyst is execution on efficiency and product initiatives, and a major risk is that rising costs and a low 3.1% net margin keep profit recovery constrained.
The most relevant recent announcement alongside Umbro is Carter’s capsule with Once Upon a Farm, which also targets young families through a focused, story driven collection. Taken together with Otter Avenue and other brand efforts, these launches sit against a backdrop of modest forecast revenue growth of about 1.8% per year and pressured margins, so investors may watch whether such collaborations support better sell through and help defend Carter’s value positioning.
Yet behind the appeal of country kits and cute farm prints, there is a real risk investors should understand around pricing power and…
Read the full narrative on Carter’s (it’s free!)
Carter’s narrative projects $3.1 billion revenue and $123.7 million earnings by 2029. This requires 2.0% yearly revenue growth and a $34.2 million earnings increase from $89.5 million today.
Uncover how Carter’s forecasts yield a $37.00 fair value, in line with its current price.
Exploring Other Perspectives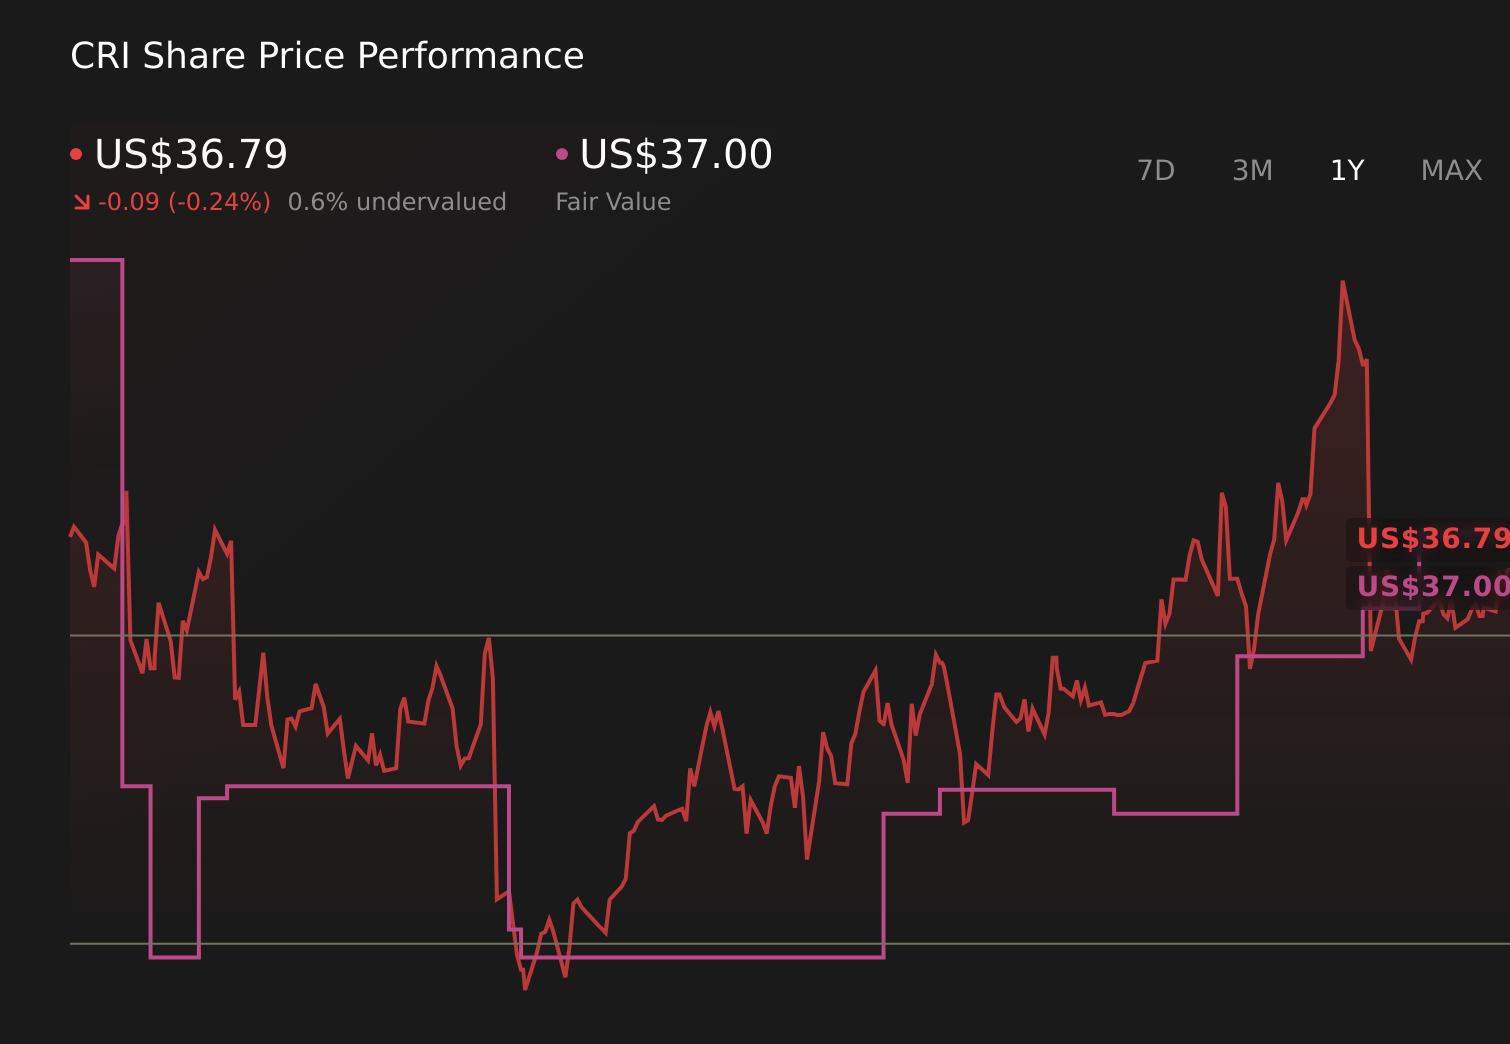 CRI 1-Year Stock Price Chart
Some analysts saw a more optimistic path, expecting revenue near US$3.0 billion and earnings of about US$108.2 million, but if wholesale weakness or tariff pressures worsen, that view could prove far more fragile than it looks.
Explore 4 other fair value estimates on Carter’s – why the stock might be worth less than half the current price!
Decide For Yourself
Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.
Want Some Alternatives?
Our top stock finds are flying under the radar-for now. Get in early:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com