
Pension funds have committed N241bn to infrastructure development under a new initiative by the National Pension Commission and FSD Africa, with the first tranche expected to be deployed by the second quarter of 2027.
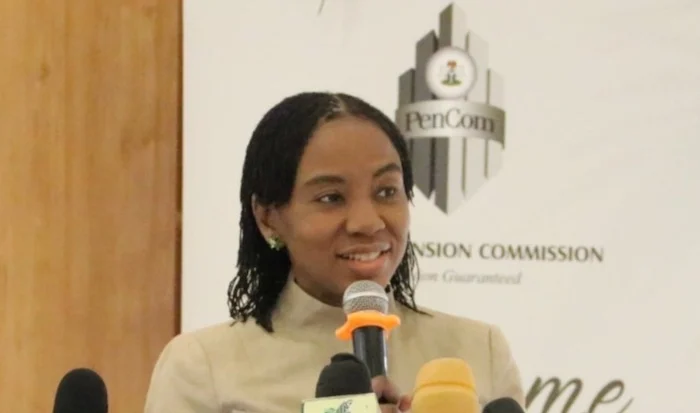
The Director-General of PenCom, Omolola Oloworaran, disclosed this on Thursday in Lagos while briefing journalists on the outcome of the fourth meeting of the Pension Industry Leadership Council.
She stated that the commitment was the first step towards mobilising long-term capital from the pension industry to support infrastructure development in Nigeria, adding that the amount was expected to rise to almost N300bn when outstanding commitments from an undisclosed participant are received.
Oloworaran clarified that the funds have not yet been invested in any infrastructure project, as the process of setting up the investment structure remains ongoing.
She noted that the industry still needs to conclude a framework with FSD Africa, sign a memorandum of understanding, and appoint a fund manager before investments can commence.
“We have the commitment. We are working with other partners. We haven’t invested any money just yet. This is just a commitment in terms of what the industry will do,” Oloworaran said.
She added that the first tranche of funds raised by the consortium is expected to be deployed by the second quarter of 2027, while development partners could potentially provide additional funding alongside the pension industry’s commitment.
The PenCom boss explained that specific infrastructure projects and asset classes have not been selected, stressing that discussions on allocation remain ongoing. Participation by Pension Fund Administrators in the initiative remains voluntary, with each PFA expected to make investment decisions in the best interest of pension contributors.
Oloworaran emphasised that infrastructure investments are attractive to pension funds because of their long-term nature and potential to provide returns as well as a hedge against inflation. She described the N241bn commitment as merely the initial phase of a broader effort to mobilise pension capital for national infrastructure.
The PenCom chief also announced the approval of an independent global benchmark maturity assessment for the pension industry as part of efforts to measure the sector against international standards and strengthen operating practices.
Additionally, the commission plans to host Pension Week from October 26 to 30, with further details to be unveiled at a subsequent media engagement.
Addressing the proposed Pensions 2030 transformation agenda, Oloworaran noted that the framework is currently at the conceptual stage and aims to formalise ongoing reforms while setting the industry’s strategic direction through 2030.
A strategy session is scheduled for December, with stakeholder engagements involving regulators and development partners expected to precede the finalisation of the agenda around December or January.
On the old Defined Benefit Scheme, Oloworaran said PenCom’s ongoing one-time enrollment exercise for employees who were in government service before 2004 is aimed at determining the total number of affected beneficiaries and the financial obligation required from the federal government.
While exact figures cannot be confirmed until the exercise concludes, she estimated that the last beneficiaries of the scheme could exit between 2035 and 2039.
She further highlighted efforts to expand pension coverage through accredited pension agents and outreach programmes targeting informal sector workers. The commission is also preparing to introduce the “I Am Alive” verification exercise, which will initially apply to retirees receiving programmed withdrawals and be accessible online or via PFA branches for retirees without mobile devices.
Oloworaran disclosed that additional details will emerge next month when the President is expected to announce a guaranteed minimum pension—a first for the nation, alongside a healthcare initiative providing free medical care for vulnerable retirees and low-income earners.