
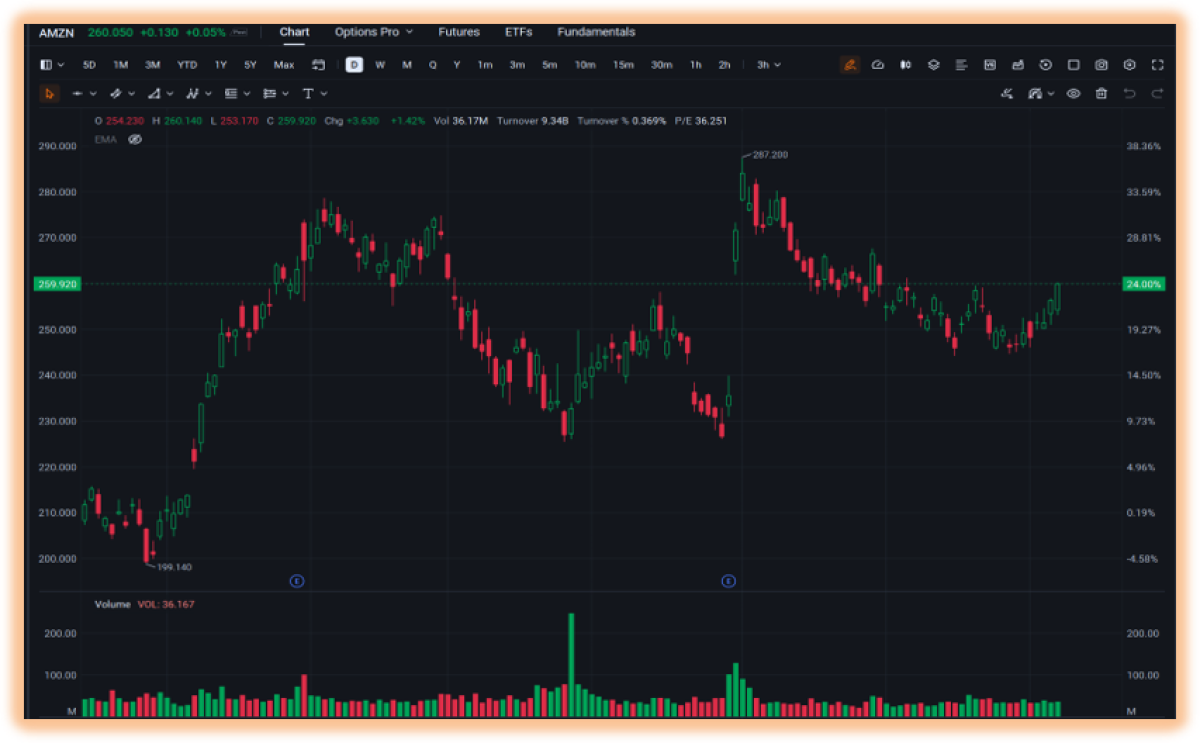
Amazon (AMZN) Founded in 1994 by Jeff Bezos, Amazon is a global technology and e-commerce company with operations spanning online retail, cloud computing, digital advertising, and subscription services. Its core businesses include Amazon Web Services (AWS), North America and International e-commerce, advertising, and Prime memberships. Growth is increasingly driven by AWS expansion, rising advertising revenue, and continued e-commerce growth, while investments in artificial intelligence, logistics, and automation are strengthening its long-term competitive position. Amazon continues to benefit from its massive customer ecosystem, global fulfillment network, cloud infrastructure, and growing adoption of AI-powered services.
Last: $259.92 | Volume: Strengthening the Uptrend
Catalyst: Amazon’s growth is driven by AWS expansion, rising digital advertising revenue, continued e-commerce growth, and increasing Prime adoption. Growing demand for AI and cloud computing is supporting AWS, while higher-margin advertising and improved fulfillment efficiency could strengthen profitability. Key risks remain heavy AI infrastructure spending, intense competition, regulatory scrutiny, and slowing consumer demand.
Amazon’s options market reflects moderate volatility expectations with a bullish tilt, with implied volatility at 41.44%, indicating expectations for some price movement in the near term. The put/call volume ratio of 0.37 shows that call trading activity significantly exceeds put activity, suggesting stronger demand for upside exposure. Overall, the options positioning points to positive investor sentiment, while the moderate IV suggests that traders anticipate continued but relatively controlled price movement.
AMZN Consensus Rating
Analyst View: Amazon remains constructive, supported by AWS growth, AI adoption, advertising revenue, and e-commerce expansion. Bulls cite strong cloud demand and improving margins, while bears highlight high AI spending, competition, and regulatory risks. Price targets: US$350–US$385. Bottom line: strong growth prospects, but execution and valuation remain key risks.
Bloomberg source: AMZN target price by analysts
Moomoo: Consensus Rating Graph (AMZN)
UWC Berhad is a Malaysian precision engineering and manufacturing group serving high-tech industries. It provides precision CNC machining, sheet-metal fabrication, advanced assembly and related engineering solutions, mainly for the semiconductor, life sciences and medical technology sectors. UWC is also expanding into front-end semiconductor equipment and other advanced manufacturing applications, positioning it to benefit from global AI and semiconductor demand.
Last: RM 8.04 | Volume: 4.13M
Catalyst: UWC’s proposed MYR384 million private placement could accelerate its transition into a full equipment manufacturer for a new US wafer fabrication equipment customer. The MYR200 million investment in a new factory and advanced machinery is expected to support MYR70 million–MYR100 million first-year revenue. Stronger net cash of MYR361 million also provides greater financial flexibility to capture broader WFE opportunities.
The following are the available warrants related to UWC, including warrants issued by financial institutions named RHB Investment, Kenanga and Ambank. The list provides the respective warrant symbols, prices, trading volumes, and key details for investors to compare and evaluate the available warrant offerings.
Morningstar views UWC’s quantitative rating stands at 1 star, with the stock trading 47% above its estimated fair value of MYR5.44. The valuation reflects relatively high expectations, while profitability metrics remain modest compared with global peers. Its earnings yield is 1.2%. The stock has also delivered strong momentum over the past year, supporting continued market interest.
Moomoo: Consensus Rating Graph (UWC)
Bloomberg source: UWC target price by analysts