
As artificial intelligence (AI) becomes part of the daily workflow at wealth management firms, the questions facing smaller, independent players are as much about control as capability. Confidentiality, regulatory expectations and the risk of uneven adoption within a firm all shape how the technology can be used safely and to best effect.
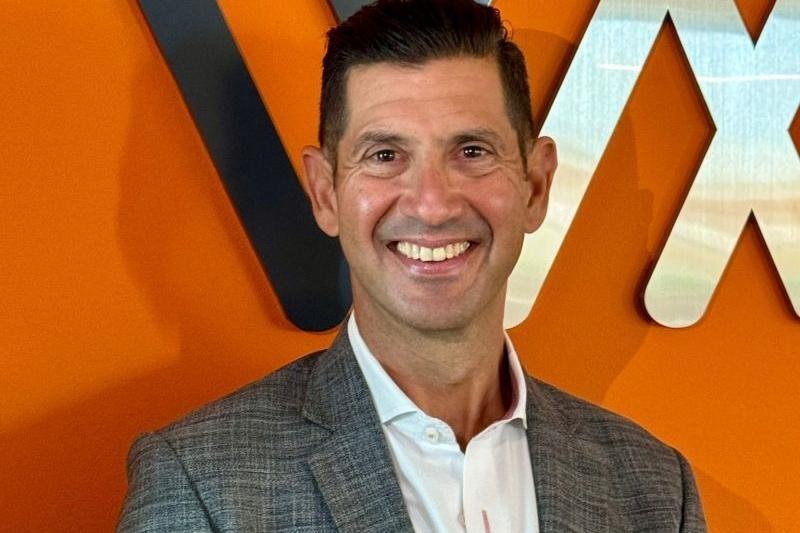
At a recent Hubbis webinar, More Clients, Better Served: Practical AI for Wealth Management in Southeast Asia, chaired by Michael Stanhope, Founder and Chief Executive Officer of Hubbis, a panel of industry leaders discussed how AI is being applied across the region’s wealth management industry. Steve Knabl, Managing Partner of Wealth Management Alliance, a wealth manager serving larger family offices in Southeast Asia, explained why his firm is putting a framework around its use of AI, the limits of AI output, and his reading of the latest regulatory guidance from the Monetary Authority of Singapore (MAS).
Key Takeaways
A framework is needed to use AI to its full potential, according to Knabl, who said his firm is looking to put protection and security around the technology rather than use it on a standalone basis.
AI can help filter information by priority, Knabl said, drawing on email, chat, to-do lists and calendars to produce a daily brief.
AI output still requires checking, with Knabl suggesting, as a personal assessment, that AI-generated results are roughly 80 percent of the way towards his requirements, leaving the remainder to human judgement and verification.
Regulatory expectations are becoming clearer, Knabl noted, pointing to the MAS Guidelines on Artificial Intelligence Risk Management and their risk-based approach to controls.
Security is the main challenge, in Knabl’s view, encompassing data confidentiality, regulatory compliance and risk management as firms develop AI capabilities in-house.
Building a Framework Around AI
Knabl explained that Wealth Management Alliance has an in-house investment team that carries out most of its research independently. He said using AI is becoming more complicated for the firm, particularly following the MAS guidelines on AI usage, and that navigating the framework from next year will become relatively more complex mainly because of security and confidentiality considerations.
He said the firm uses AI in many different ways and is currently looking at an enterprise version of one AI module. Knabl explained why the firm is resolved at putting a framework around its usage and not simply using AI on an individual standalone basis. “Anybody can do anything with it,” he said. “We think that we need to put a framework around it, protect it, put security around it, so that we can use the full power of AI at the company level and not only as individuals.”
Knabl noted that many people use AI in a similar way to a search engine. The question his firm is considering, he said, is how to use it so that everybody within the organisation benefits, “and not just one user or two users that are good at using it”.
Filtering the Information Flow
Asked how AI can help with information overload, Knabl said the more AI is used, the more information overload is likely to grow. How much AI can help, he suggested, depends on how agents are trained, the standing instructions you integrate and how guardrails have been implemented.
He said AI today can for example filter important elements by priority on a given day. Depending on how it is codified, Knabl explained, it can refer to meetings, notes, calendar, etc., and combine them into a daily brief. “Hey, this is what your day looks like, and this is what you need to get out the gate today,” he said, describing the kind of summary such a tool can provide. Knabl said this is particularly useful for people like himself who manage many different things in a single day. Another example is for analysts with a specific focus, he said, AI can be used extensively to analyse data, the market and parse all available information into a result that is precise, concise and actionable.
Eighty Percent There
Knabl noted that much of the time spent working with AI goes into cross-checking information input and output, depending on which metrics are being used. “The output is, I’d say, probably today, 80 percent there,” he said. “But that 20 percent remains still in our brains.”
Returning to his opening point, Knabl said guardrails are needed to ensure AI is given the right guidelines and the right access to the right data in a secure and confidential manner.
He added that, personally, he is spending more and more time harnessing AI to obtain the output he needs. “It’s not that it’s saving me a massive amount of time,” he said. “It’s making me more productive with qualitative outputs, and it’s most certainly making me change the way I’m actually working.” He suggested the same is likely true for many people.
A Clearer Regulatory Direction
Asked about the direction of regulation, Knabl said it is becoming clearer. He pointed to the MAS Guidelines on Artificial Intelligence Risk Management, released on 7 October 2026, which he compared to the regulator’s earlier technology risk management guidelines. In his reading, the guidelines are “extremely prescriptive, extremely clear” on what MAS expects the industry to implement for AI usage.
Knabl said the guidelines set out expectations for controls depending on how AI is used and the extent of that use, reflecting a risk-based approach. He highlighted their implications for activities such as investment advisory and portfolio construction, and the need for appropriate controls and safeguards. Published on 7 October 2026, the MAS guidelines take effect on 7 October 2027, with a phased implementation schedule extending certain requirements to October 2028. Depending on the approach taken, he noted, this may have consequences for headcount and for the cost of using, deploying and controlling AI.
Knabl also suggested that users of AI often do not realise the potential risks they may be placing on their firm. He noted that clients also use AI and frequently bring complex questions to their advisers. While understanding those questions is the firm’s job, he said, firms also use AI to respond quickly, particularly in writing. “We have to be very careful where we’re going with this,” he said, adding that firms need to keep pace with clients and investors, who are usually sophisticated but still needing human interactions.
From Individual Use to Enterprise Use
Knabl also raised a question with the panel about how firms can share AI expertise internally. He observed that a few individuals within a firm are often particularly creative in how they use AI, and asked how that creativity can be shared so that it produces results for the firm as a whole.
He said this is a challenge he sees internally and at many companies, where individuals tend to use AI within their own silo to improve their personal productivity. The question, Knabl said, is how to move from there to enterprise-wide use of good ideas and sharing of that productivity enhancing the deliverables of the firm across the board.
Security in Parallel
In his closing remarks, Knabl said the main challenge for the financial industry, alongside developing AI capabilities in-house, will be security. “That’s going to be our biggest challenge, managing that security around the AI within our firm,” he said, including the confidentiality of data.
He said he uses the word security broadly, to encompass regulatory and risk management considerations as well.