
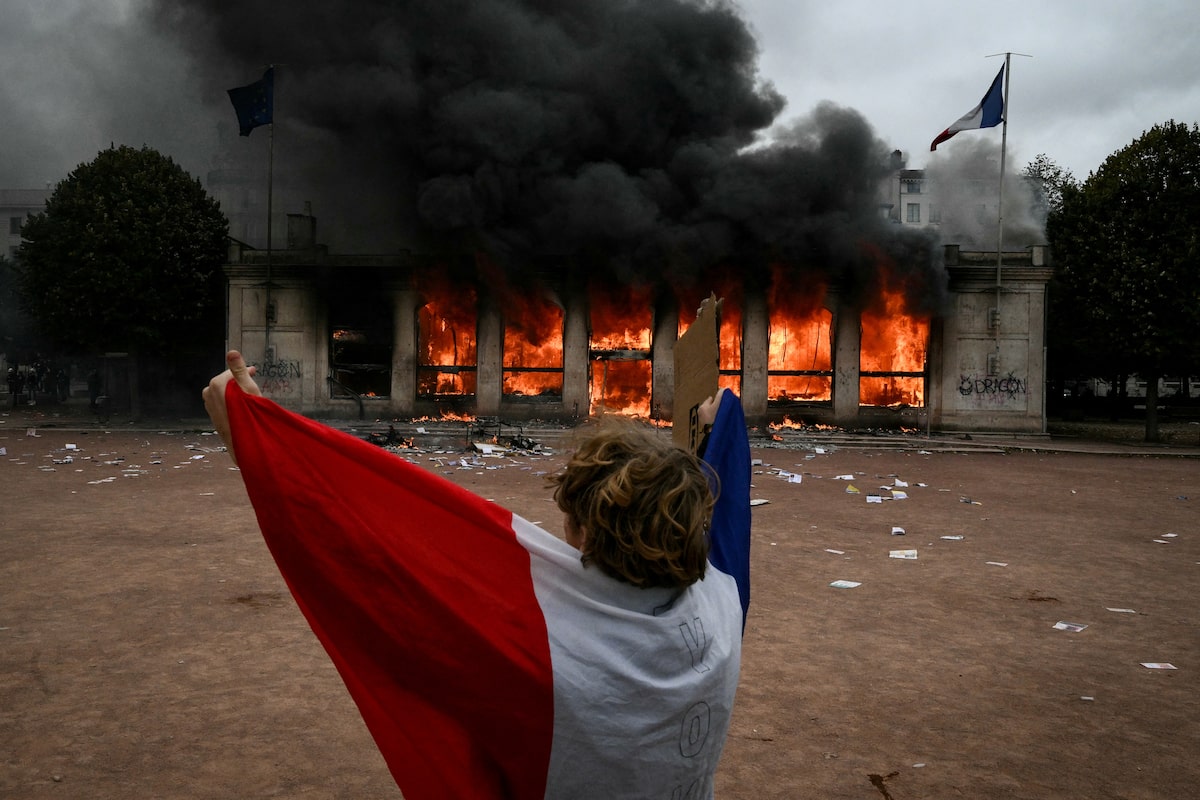
A protester wrapped in a French national flag stands in front of Lyon’s tourism office, set on fire during a demonstration to protest against the high cost of living, in Lyon, on Oct. 17.JEFF PACHOUD/AFP/Getty Images
Kevin Yin is a contributing columnist for The Globe and Mail and an economics doctoral student at the University of California, Berkeley.
French rioters are using national education protests as a pretext to burn government buildings and rob stores across the country. While the protests initially focused on improving poorly equipped schools, they have spiralled into broader grievances about the government and the cost of living. Meanwhile, French bond yields are soaring, growth has stagnated, and fiscally profligate far-right and left parties are ascendant. In other words, France is out of money, but the French are in no mood to make cuts.
Why does France burn while Canada forges ahead? And what does this imply about how other advanced economies should manage their finances?
Of course, cultural and historical factors have contributed to France finding itself in this position. But with regard to the economy, one key element drives French fiscal unsustainability, which in turn limits its ability to satisfy protester demands or calm bond markets. That element is the French pension system.
Parisians voiced mixed views on a second night of partial curfews on Tuesday, as police patrolled the capital after weekend riots and looting plunged France into one of its worst periods of unrest in years.
Reuters
Unlike Canada, France uses a pay-as-you-go, almost entirely public pension system, with only about 2 per cent of French pension spending being private. Pay-as-you-go means that today’s working French pay directly for today’s retirees with their contributions, with a limited role for investment income from pension reserves. Such a system is delicate because it depends on a stable ratio of workers to retirees, all else being equal.
At 13.4 per cent of gross domestic product, French state pension expenditure is also large compared with other public pay-as-you-go countries such as Germany (10.8 per cent) or hybrid public-private systems such as Canada (5.9 per cent), Britain (7.1 per cent) and the United States (7.3 per cent), according to recent figures from the Organization for Economic Co-operation and Development.
By contrast, Canada uses a partially funded public pension system with significant private supplementation. The public Canada Pension Plan has a much larger stock of invested assets relative to payouts, which provides investment income to pay for today’s retirees. Nearly 40 per cent of all Canadian pension spending is from other private, more sustainable sources. Old Age Security suffers from the same vulnerabilities as France’s program but plays a smaller role in Canada’s overall retirement system.
Pay-as-you-go in the absence of private support is a fiscal albatross. When a country’s birth rate and immigration (which France is also souring on) are not keeping its demographics sufficiently young, revenue falls below retiree claims. In Western democracies, aging populations are the norm; immigration is at best a temporary solution, and at worst a political quagmire. To make up the difference, France must borrow, raise the retirement age, increase taxes or cut spending.
Why is the French economy, and the country in general, in such a mess?
French taxes are already exceptionally high by OECD standards. Borrowing is how France has historically dealt with the problem, having not run a budget surplus since 1974. However, borrowing simply kicks the can down the road and, more recently, risks a genuine sovereign debt crisis. President Emmanuel Macron’s 2023 attempt to raise the retirement age has been suspended, after resulting in years of legislative gridlock.
Not only do pension expenditures limit the fiscal wiggle room for education spending, education costs also rise directly with the cost of pensions; more than a quarter of France’s 2025 education budget is actually pension spending on employees. Within a constrained budget, that eats up an enormous share of resources.
Canada sidesteps this problem by not making pension funding a constant political issue. Each person funds part of their own future, and a large chunk is paid from investments made decades ago on our behalf, making our fiscal health less vulnerable to demographic changes. This saves precious political capital for tackling other challenges.
Unfortunately, transitioning from pay-as-you-go to a partially funded system is brutally difficult, as Canada’s experience in the 1990s demonstrated. If France decided to switch over tomorrow, young French workers would have to continue funding existing retirees while simultaneously contributing to the investment stock that would only pay dividends later. France could mitigate the upfront cost by borrowing and spreading the burden across many generations. However, it is currently in no position to do so.
While France may be unique in both the magnitude of its pension outlays and its citizens’ fiscal demands, it represents a more general tale of caution for many advanced economies. Pay-as-you-go is a Band-Aid solution that must constantly be patched. But as bond yields rise and global debt-to-GDP ratios remain high, substantial sacrifices will be needed to achieve a more sustainable system.
On this issue, it is truly a relief to be Canadian.