
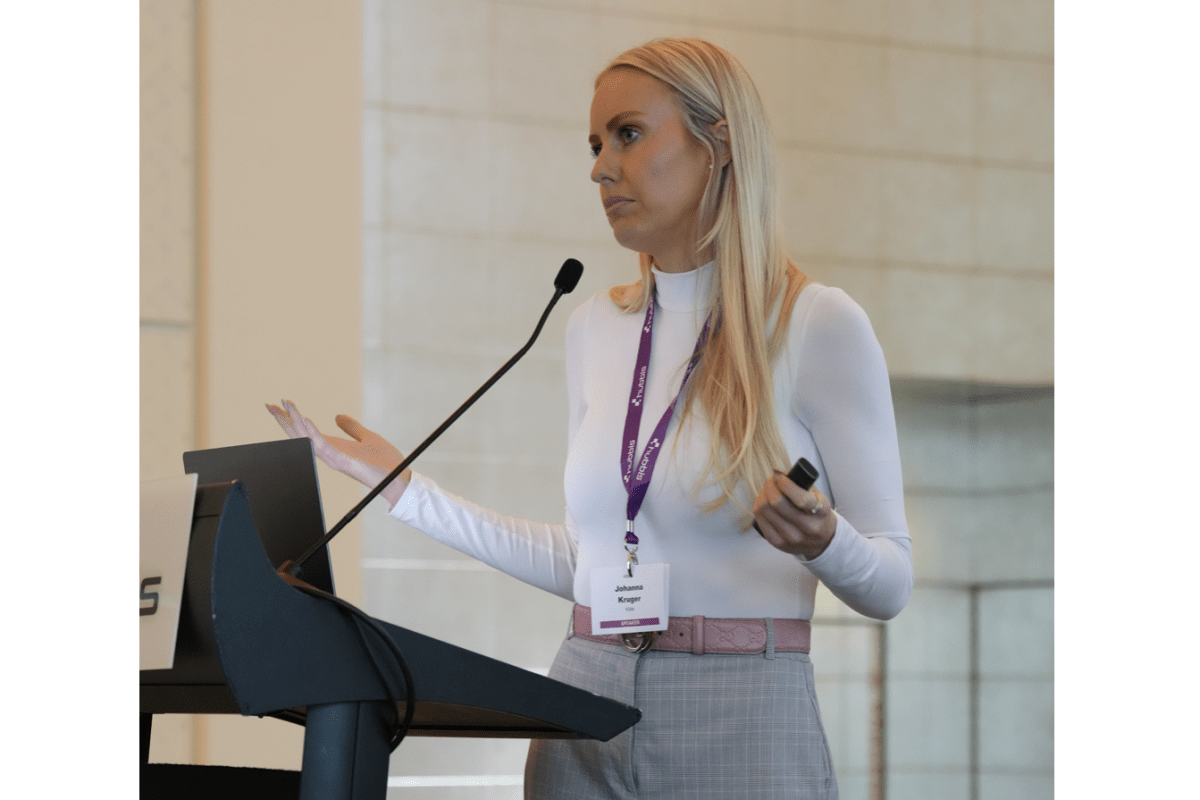
Kilde’s Johanna Krüger outlines private credit due diligence questions wealth managers should ask about underwriting, valuations, liquidity, leverage and fees.
At the Hubbis Middle East Private Capital Forum 2026, Johanna Krüger, Head of Institutional Investor Relations at Kilde, asked wealth managers to look beyond a private credit manager’s accepted deals and headline yield. The more revealing evidence may lie in the loans it rejected, the exceptions it allowed and the way it handled a borrower in difficulty.
Kilde is a Singapore-based, regulated private credit manager focused on senior secured, asset-backed finance for non-bank lenders. Krüger drew on questions from its investment and underwriting teams to build a practical due diligence checklist. The presentation addressed manager behaviour and fund structure as much as borrower credit quality.
Her central test was whether the reported return can be traced through actual cash repayments, fair valuation, leverage and every layer of fees. Private credit’s growth makes those questions more consequential, not less.
Key Takeaways
Proprietary Needs Proof: Ask which transactions a manager sourced through relationships and which were broadly marketed to competing lenders.
Rejections Reveal Discipline: The reasons a manager declined deals, and the frequency of investment committee exceptions, may say more than a list of approved loans.
Returns Need a Cash Test: Separate realised repayments from accrued or payment-in-kind interest and inspect outliers across the loan book.
Marks Need a Trail: For troubled credits, ask when and why values changed and whether an independent party reviews them.
Amendments Are Decisions: Extensions and covenant changes can protect recoveries, but repeated amendments need a clear explanation alongside any enforcement alternatives.
Liquidity Depends on Assets and Terms: Loan maturity, cash collections, redemption caps and gates must be reconciled with the fund’s promised dealing window.
Leverage and Fees Change the Outcome: NAV facilities, borrower-paid charges and affiliated-party fees should be visible in the investor’s net-return calculation.
People Matter Too: Underwriting-team departures and strategy drift can weaken the process on which an older track record was built.
Scale Is Not a Due Diligence Answer
Krüger began with private credit’s expansion to an estimated USD 3 trillion global asset class. Bank retrenchment after the financial crisis and investor demand for income helped non-bank lenders grow, but a broad asset-class figure says little about the loans in a particular fund. Corporate direct lending, receivables finance and other asset-backed strategies have different durations, security packages and loss mechanisms.
She challenged the vocabulary of manager presentations: proprietary sourcing, differentiation and discipline. If several large lenders bid for the same financing, the eventual winner should not present the deal as though it had exclusive access. In less familiar markets, a relationship may genuinely improve origination, but an allocator still needs evidence of the pipeline and the manager’s ability to repeat it.
The deals declined are equally instructive. Krüger urged investors to ask what the investment committee rejected, what non-negotiable collateral and covenant requirements apply, and how many holdings needed an exception. A manager can earn a higher spread by stepping outside its stated strategy; it should then account for the decision and any later loss in the full record.
Read the Track Record Beneath the Yield
An attractive aggregate return can conceal very different loan outcomes. Krüger suggested looking for unusually strong or weak transactions and asking whether they reflect the core underwriting process or a few exceptions. Investors should also compare realised cash returns with unrealised marks and accrued payment-in-kind (PIK) interest. PIK allows interest to be added to the balance rather than paid in cash now; the recorded income still depends on eventual repayment.
Valuation is another test. A troubled loan held at par until a sharp write-down deserves an explanation: when did information about the borrower change, who valued the loan, and why was an earlier adjustment unnecessary? A gradual markdown is not automatically more correct, but a documented valuation trail makes the judgment reviewable. Krüger asked explicitly, “Who marks the book?”
Her team’s phrase “amend and pretend” captured a further concern. A covenant breach may lead to an extension or amendment rather than immediate enforcement. That can be the commercially sensible route to recovery, but an investor should be shown the breach, the alternative remedies considered and the revised economics. Repeated changes that defer recognition of a weak credit warrant closer scrutiny.
Match the Liquidity Promise to the Loans
Fund dealing terms can be easier to understand than the assets that support them. Krüger asked what proportion of the portfolio could realistically be converted into cash within three or six months, not merely what a brochure says about redemption dates. Gates may protect remaining investors when requests exceed available liquidity, but the size of a quarterly cap and the treatment of queued requests should be known before subscription.
Kilde’s own underlying receivables can be shorter-dated than a long-term corporate or project loan; Krüger described typical periods around 90 to 120 days for some of its lending assets. A short loan tenor does not itself guarantee that a fund can honour redemptions. Collection performance, reinvestment, facility terms and the fund’s own liabilities still determine the available cash.
She also urged scenario analysis that reaches through to borrowers’ economies. Energy shocks, for example, may pressure consumers and lenders in an importing country while helping activity in an exporting one. A manager should show how those paths affect cash flows and collateral, rather than rely on a generic downside case.
Trace Leverage and the Investor’s Net Return
Leverage can sit with the borrower or at fund level. A net asset value (NAV) loan against fund assets may provide liquidity or finance distributions before the underlying loans repay. Because earlier distributions can lift an internal rate of return, investors need to know how much of the cash came from borrowers and how much from financing. They should also understand covenants, lender rights and the consequences of a facility being withdrawn.
Fees deserve the same look-through treatment. Management and performance fees are only part of the cost if a manager or affiliate also earns arrangement, monitoring or advisory charges from borrowers. Krüger proposed following one dollar of gross loan yield through every expense and incentive calculation to the investor’s net receipt.
Together, rejection records, valuation files, amendments, team continuity, gates and fee schedules test whether returns reflect durable underwriting.