
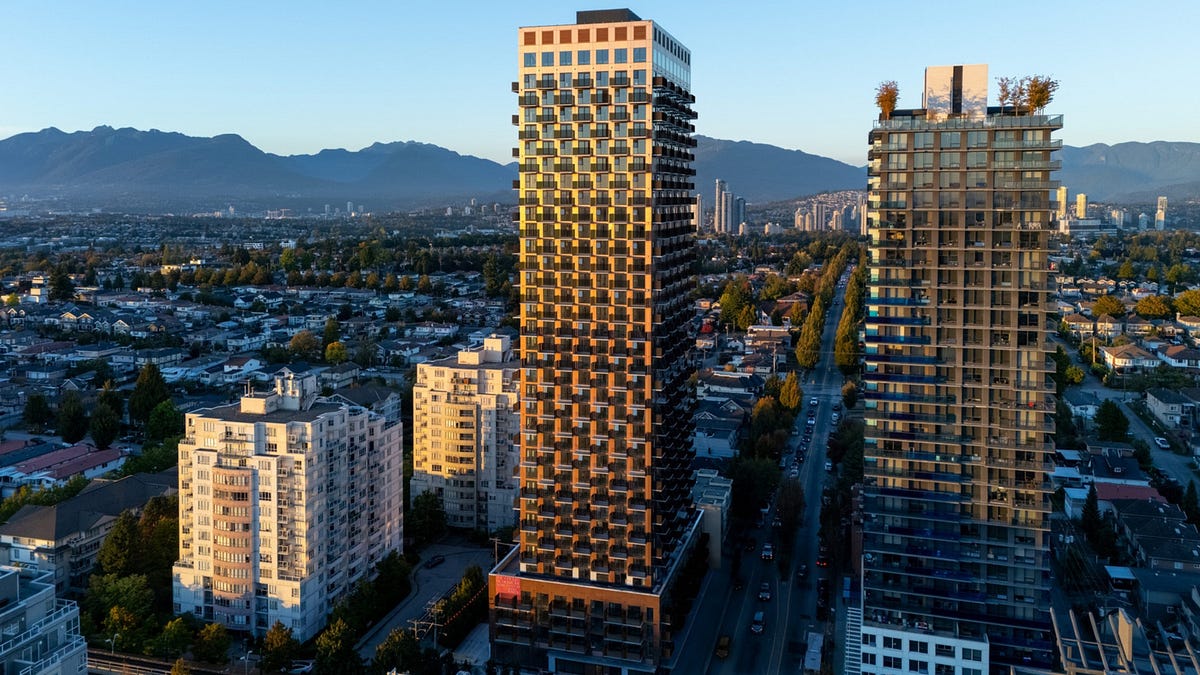
 The Joyce 2 rental tower at 5083 Joyce Street in Vancouver. (Westbank)
A substantially-completed rental tower by prominent Vancouver-based developer Westbank has been placed under receivership, according to filings in the Supreme Court of British Columbia, the latest instance of a completed or nearly-completed project becoming insolvent.
The 35-storey rental project is known as Joyce 2 and is located at 5083 Joyce Street in Vancouver, directly across the street from Joyce 1 at 5058 Joyce Street, a 29-storey condo project completed by Westbank several years ago, both of which are right next to the Expo Line SkyTrain’s Joyce Station. Joyce 2 consists of 360 rental units and 4,500 sq. ft of retail space and the property is held by Westbank under 5055 Joyce Property Inc.
The receivership application was filed by Toronto-based pension fund OPTrust, which bought out Westbank from Sen̓áḵw last year for an undisclosed price. Notably, however, OPTrust is the second-ranking mortgage holder and the first-ranking mortgage holder is National Bank.
“The appointment of a court-supervised receiver has been sought to ensure the project can reach final completion in an orderly and timely fashion,” said Westbank and OPTrust in a joint statement provided to The Realist. “This was undertaken cooperatively with Westbank and is consistent with shared objectives to facilitate the completion of the project.”
“Receivership establishes a court-supervised framework that provides independent oversight and keeps the project on track while remaining work is completed,” they added. “Building operations and leasing continue, and residents are not impacted. Once fully complete, 5083 Joyce will add new purpose-built rental housing supply to the community, including affordable rental units, in a transit-adjacent location.”
According to OPTrust’s receivership application, which was filed on March 26, 2026 and granted by the Supreme Court on April 27, the two sides entered into a loan agreement in May 2021 for the principal amount of $40,000,000. The amount was later increased to $85,000,000.
The interest rate was set at 5.25% per annum for the period up to September 10, 2024 before escalating to 11.0% thereafter and would further escalate to “the lesser of the highest rate permitted by law or the sum of 10% plus the Interest Rate” in the event of a default or the loan maturing. The maturity date was set as December 31, 2025 and the loan was guaranteed by Westbank, Abbey West Properties Inc., IGF Holdings Ltd., Ian Gillespie, and the Ian Gillespie Family (2014) Trust.
According to OPTrust, the loan matured on December 31, 2025 and they issued a formal demand for payment on January 13. Since then, OPTrust says they learned that at least five liens had been filed against the project and that National Bank issued a demand for payment on January 8 after at least six defaults, including failing to make interest payments and failing to comply with equity infusion obligations.
OPTrust also said that a report prepared by the project’s development cost consultant estimated cost overruns of $15.5 million, with $8.2 million related to hard construction costs.
As of March 19, OPTrust says it is owed $109,211,965, with interest now accruing at the default interest rate, which amounts to $60,136 per day.
OPTrust says National Bank, which is in support of the receivership, is not prepared to advance additional funds for the project and that the project is now “at a standstill due to a lack of available capital.” Legally, receivership allows additional funding to be borrowed in a way that is secure for the lender, providing a pathway for the project to be completed, and OPTrust says it is willing to provide further funding under a receivership.