

3D Systems recently reported first-quarter 2026 results showing revenue of US$95.54 million and a sharply reduced net loss of US$4.42 million, while guiding second-quarter 2026 revenue to a range of US$93 million to US$95 million.
Ahead of the 2026 Formula 1 season, the Cadillac Formula 1 Team disclosed it has deployed seven of 3D Systems’ large-format SLA printers and materials to accelerate wind tunnel testing and production parts, underscoring the company’s role in high-performance, time-sensitive manufacturing.
We’ll now examine how Cadillac’s adoption of 3D Systems’ printers and the improving loss profile might influence the company’s investment narrative.
We’ve uncovered the 12 dividend fortresses yielding 5%+ that don’t just survive market storms, but thrive in them.
3D Systems Investment Narrative Recap
To own 3D Systems, you need to believe its mix of healthcare and industrial additive manufacturing can translate into sustainable, profitable growth despite choppy capital spending and intense competition. The latest quarter’s narrower US$4.42 million loss and Q2 revenue guidance suggest some operational progress, but they do not yet remove the key near term risk that delayed customer capex and elongated sales cycles could still hold back any meaningful recovery in printer demand.
The Cadillac Formula 1 Team’s deployment of seven large format SLA systems is most relevant here, as it illustrates 3D Systems’ push into high performance, production grade use cases that support its end to end manufacturing narrative. While one program does not change the overall risk profile, it does give tangible evidence of how advanced applications in automotive and motorsports could reinforce the company’s industrial catalyst of moving beyond prototyping into real production parts.
Yet against this improving loss profile, investors still need to be aware of how prolonged customer capex weakness could…
Read the full narrative on 3D Systems (it’s free!)
3D Systems’ narrative projects $359.5 million revenue and $2.6 million earnings by 2028.
Uncover how 3D Systems’ forecasts yield a $3.62 fair value, a 20% upside to its current price.
Exploring Other Perspectives 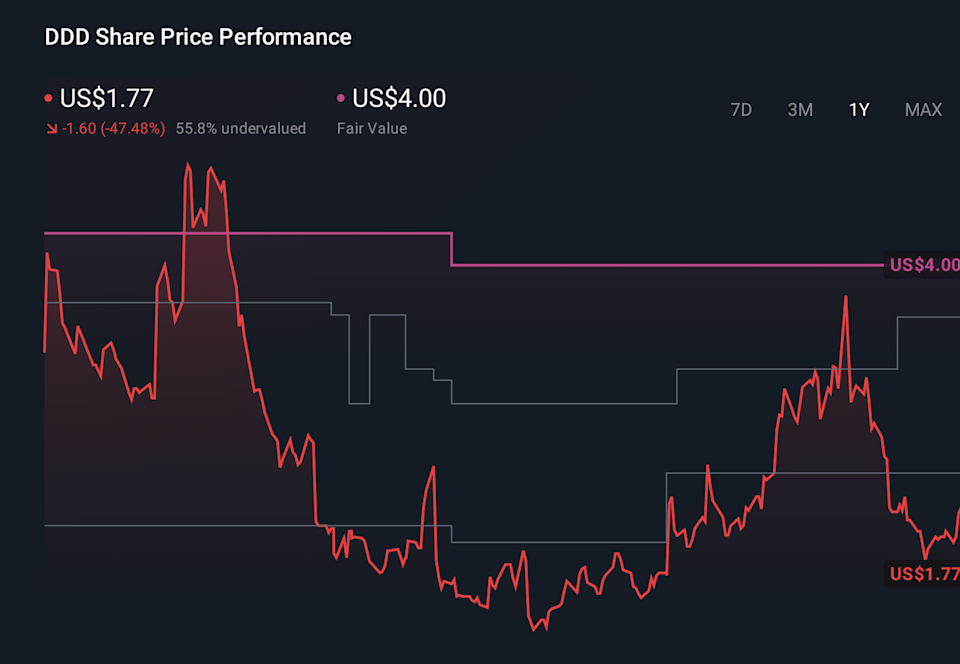 DDD 1-Year Stock Price Chart
While consensus sees modest revenue growth, the most optimistic analysts once projected about US$439.5 million of revenue and US$45.6 million of earnings by 2029, so this Cadillac win and improving loss profile could either support that upbeat view or prompt a rethink of how much execution and market risk you are willing to accept.
Explore 4 other fair value estimates on 3D Systems – why the stock might be worth 22% less than the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
Want Some Alternatives?
Early movers are already taking notice. See the stocks they’re targeting before they’ve flown the coop:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include DDD.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com