
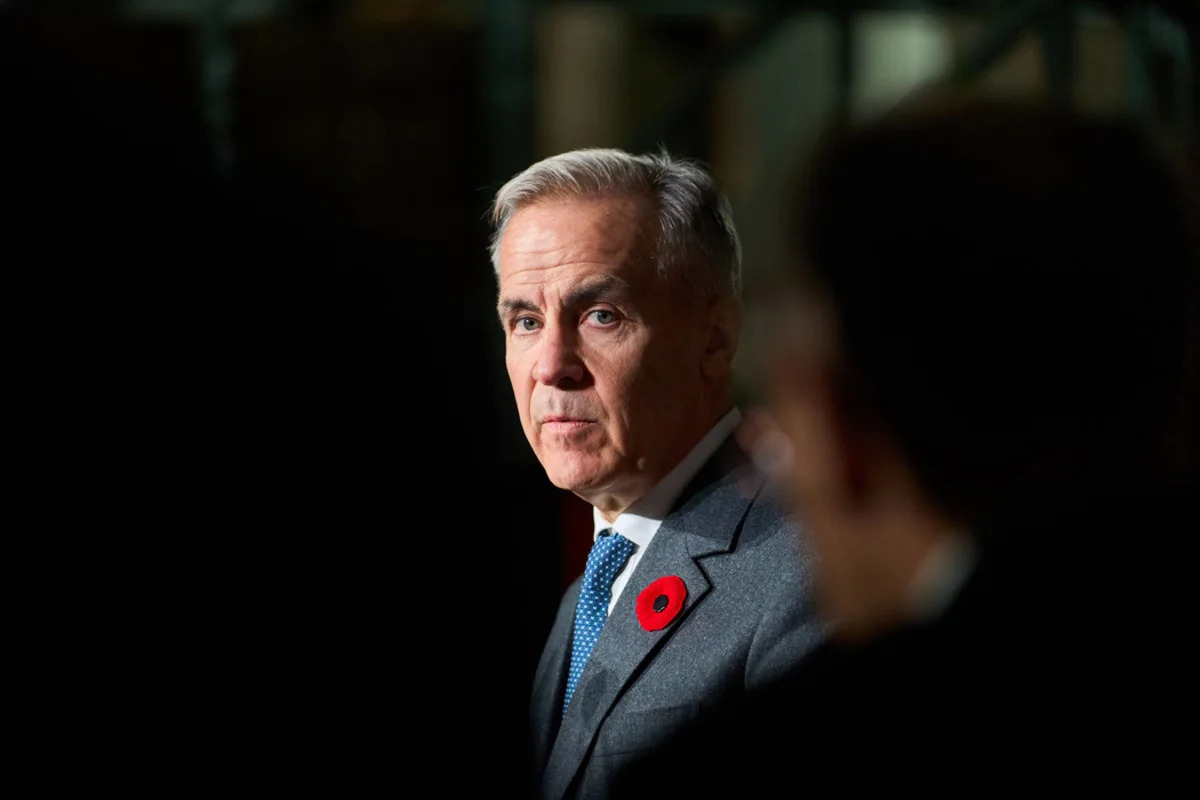
 Prime Minister Mark Carney speaks at a news conference at the development site of Wehwehneh Bahgahkinahgohn in Winnipeg, Nov. 6, 2026. (David Lipnowski/Postmedia)
This year’s federal budget promised to make life a little less painful for mortgage shoppers.
Admittedly, several of its headlining proposals belong in a museum of things that should have happened a decade ago — like digital income validation, transparency around mortgage penalties and private default insurance for the five-to-50-unit rental market.
Still, better late than never.
One of the brighter spots for homebuyers is a new set of rules for default-insured mortgages where the down payment is 20 per cent or more.
How it will work
Behind the scenes, lenders use what’s called “bulk insurance” to de-risk mortgages with at least 20 per cent equity (known in the industry as “low ratio” mortgages) right before bundling them off to investors.
On these low-ratio mortgages, today’s maximum amortization is 25 years, and the maximum purchase price is $999,999.99 — a number that buys detached home hunters a lovely garage in central Toronto or a damp shed in Vancouver.
The budget proposes bumping those low-ratio limits to 30 years and $1.5 million for first-time buyers and newly built homes.
(Side note: If Ottawa cared about the little guy, it would extend these exact rules to existing homeowners switching lenders at renewal — a move that would force the major banks to sweat more for your business. This iota of common sense was not included in this year’s fiscal release, but I remain hopeful.)
This change to low-ratio rules largely matches the current high-ratio insurance policy (for mortgages with less than 20 per cent down), which makes sense.
After all, why reserve maximum flexibility solely for borrowers with the least skin in the game?
This change should have happened two years ago when they loosened high-ratio rules, but foresight and policy don’t always go hand in hand.
In theory, this move lets non-bank lenders insure more low-risk mortgages, bundle them into securities and access cheaper funding. Cheaper funding means they can offer you a lower interest rate and actually give the Big Six banks a run for their money.
I’d like to emphasize the in theory part. Because right where the good news starts, government policy quietly pulls the rug out from under those small and mid-sized lenders who keep the big banks honest.
Stacking the deck
By expanding who qualifies for low-ratio insurance, Ottawa just created new demand for mortgage securitization. Yet the budget failed to increase lender access to the actual securitization programs required to fund those mortgages.
Without adequate securitization, smaller lenders simply can’t fund prime mortgages at competitive rates.
To compete, they rely on two things the government is rationing like wartime butter:
Right now, for example, a lender’s annual single-family-residential CMB allocation is pitifully small — at most about $500 million-ish.
To put that in perspective, that’s less than one-one-thousandth of the $500-billion-plus mortgage machine the Big Six banks run every year.
It gets worse. According to mortgage finance companies (MFCs), the bureaucratic masterminds setting quarterly limits for floating-rate mortgages — borrower’s favourite dish on the menu at the moment — are letting lenders fund a whopping $25 million or so, per quarter.
That’s like bringing an eyedropper to a five-alarm house fire.
And instead of fixing it, the Canada Mortgage and Housing Corporation (CMHC) has quietly let CMB allocations shrink over time.
Then there’s the aggregator trap. Smaller lenders often rely on third-party mortgage aggregators (investors who issue MBS) to pool and fund their loans. Shortsighted CMHC policy dictates that an aggregator only gets one MBS allocation, no matter how many small lenders it supports.
So, the big boy lenders (those who can issue MBS on their own) each get their own massive buffet, while all the smaller lenders have to split a single Happy Meal.
Adding insult to injury, each NHA-approved lender that the aggregator supports technically gets its own MBS allocation on paper, but CMHC’s Byzantine rules and economics make it impossible to fully use.
As a result, some aggregators refuse to even fund new lenders, hampering competition and innovation.
(The solution, while we’re on the topic, is to allow each lender access to one reasonable-sized CMB allocation and lift the aggregator restrictions that limit growth of fintech lenders. If only we had a Competition Bureau that cared about this sort of stuff.)
And as a final kick in the teeth, since 2016, lenders haven’t been allowed to use the crumbs they do get to fund low-risk refinances — only purchases and switches. That hands the Big Six, who sit on mountains of cheap deposit capital, an insurmountable monopoly (sorry, oligopoly) over anyone refinancing a home.
The result? True competition in Canada is a mirage for four out of five borrowers. Unless you have less than 20 per cent equity, most MFCs are effectively locked out of challenging big bank rates.
And it’s not because these smaller lenders are reckless cowboys. CMHC’s own data show these lenders had a 90-day arrears rate of just 22 basis points in the first quarter — making them 21 per cent safer than the big banks. (Granted, some of that is because big bank arrears are more heavily weighted toward eye-wateringly expensive big-city homes, but the point stands.)
As one industry veteran put it to me recently: “Name one failed MFC? I can’t. But I can name two recent almost-bank-failures.”
Big talk, limited action
Ottawa loves a good press release about “empowering consumers” and “encouraging lender competition.”
CMHC uses similar buzzwords about its securitization programs, publicizing that they promote “competition in the mortgage finance system.”
Problem is, CMHC’s tiny CMB and MBS allocations are a parody. They’re like tossing a single Timbit into an NHL locker room and calling it post-game catering.
There’s just no excuse for starving smaller lenders of funding, especially when federal mortgage securitization:
Promotes supply creation (more liquidity lowers funding costs, which increases mortgage demand and household debt, unless more supply offsets it)
Despite all this, Canada’s MBS guarantees outstanding (as a share of GDP) are 41 per cent lower than in the U.S.
One logical conclusion is that policymakers don’t actually want anyone competing too aggressively with their beloved banking oligopoly.
Whenever pressed, regulators mumble something about “financial stability” — the idea that if big banks make slightly less money, or smaller lenders grow, the earth might spin off its axis.
But that argument doesn’t pass the laugh test, since:
Prime mortgage default rates are a rounding error and have been for decades — including during market selloffs. Arrears could quadruple tomorrow and the government’s insurance and guarantee revenue would still keep taxpayers comfortably in the black over time.
The Big Six are wildly profitable fortresses that will survive having to trim their margins by 10 basis points.
Small lenders are supervised and audited by their bank funders who are supervised and audited by zealous federal regulators.
Even if small lenders tripled their volume tomorrow, they would still be a statistical speck next to the Big Six.
While Ottawa happily taxes the bejeezus out of us and backs bonds for every deficit-bloating pet project under the sun, it clutches its pearls over guaranteeing rock-solid Canadian mortgages where fewer than 30 in 10,000 borrowers are 90 days late.
Another favourite Ottawa excuse is that issuing more government-backed mortgage securities creates competition for regular Canadian government bonds, nudging up the country’s borrowing costs. But that didn’t stop them from establishing a covered bond registry, which helped big banks securitize their uninsured mortgages more cheaply.
Besides, if sovereign bond competition were a genuine crisis, the government could simply shift MBS allocations away from the major banks (who don’t need them) and give them to the smaller lenders (who do).
Ottawa needs to act
You don’t need a Harvard and Oxford economics pedigree like Prime Minister Carney to see how absurdly tilted this ice rink is.
And speaking of Mr. Carney, he could fix this bottleneck in a single afternoon meeting.
But, giving him and his finance minister the benefit of the doubt, maybe nobody has shown them how badly CMHC’s plumbing is choking out competition.
Consider this the memo.
If the government genuinely wants to make life more affordable for the three-quarters of Canadians who will need a mortgage in their lifetime, it needs to open the securitization taps a bit more.
Editor’s Picks
Foreign banks certainly aren’t coming to save us — every time one tries (RIP ING Direct and HSBC Canada), the Big Six just buy them out and swallow the competition like a python eating a goat.
None of this is a slight against the banks. They’re just doing what rational titans do — and hey, it’s a cozy little cartel if you can get into it.
And I wouldn’t dare imply the Canadian mortgage finance system is rigged. Let’s just agree that if it were any more fixed, it would come with a five-year term.
For the best national insured and uninsured mortgage rates, updated daily, please visit our mortgage rate page here.