UK borrowing costs rose to levels not seen since the 2008 financial crisis, while the pound faltered, as investors raised bets that Andy Burnham could succeed Sir Keir Starmer and usher in a shift toward looser fiscal policy.
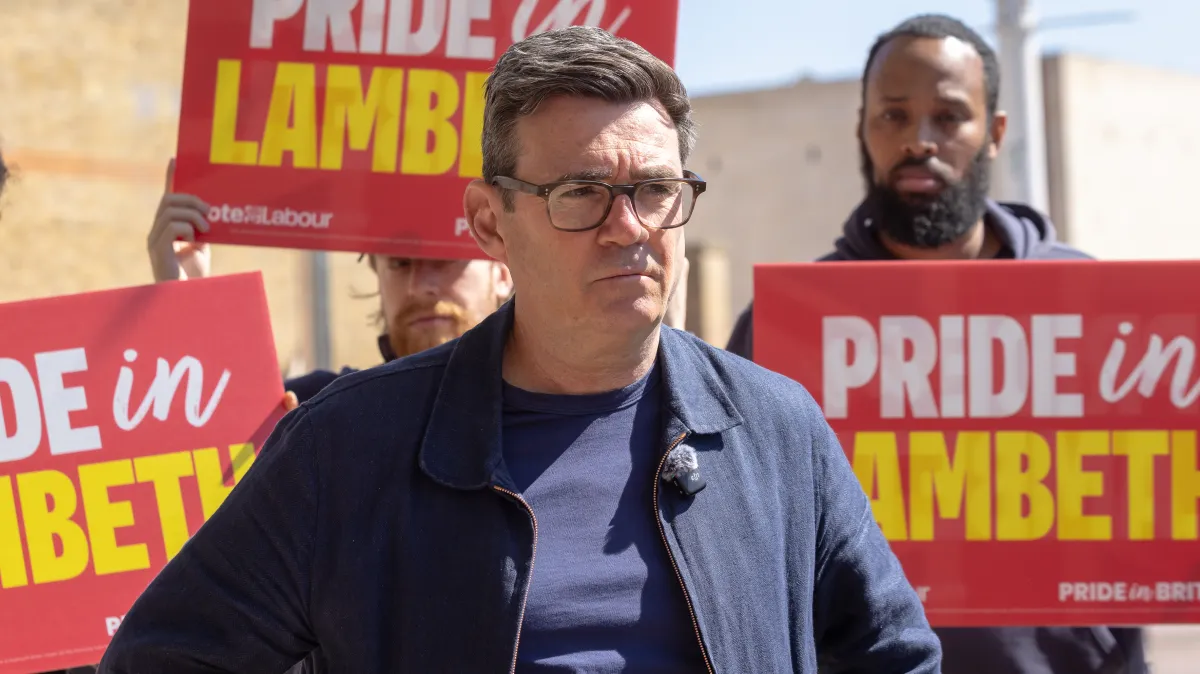
Traders sold government debt, the pound, and UK stocks after Burnham, considered by the markets as the most left-leaning challenger to the leadership, said he would run in the Makerfield by-election to become an MP.
The yields on ten-year gilts gained 18 basis points on Friday, hitting 5.18 per cent, the highest level since 2008. The yield on 30-year bonds, which are more sensitive to political uncertainty, gained 19 basis points to 5.85 per cent, the highest level this century.
Bonds across European markets all sold off on Friday but gilts were the worst-performing major asset class and on track for the largest weekly rise in yields in nearly two years.
“Investors are focused on the impact a leadership contest might have on Britain’s fiscal trajectory, gilt issuance over the next couple of years, and its interplay with inflation,” James Smith, an economist at ING, said.
The pound dropped to a five-week low against the dollar after weakening another 0.6 per cent to $1.33. Sterling also lost 0.21 against the euro to €1.16. Stocks on the FTSE 100 shed 1.7 per cent and FTSE 250 declined 1 per cent — in line with falls across the Continent’s equity markets.
Mark Dowding, chief investment officer at RBC BlueBay Asset Management, said the fund had increased its bets against the pound this week “given that we struggle to see the currency rallying against a weak economic environment”.
Gilts have suffered the most volatile moves after Labour’s resounding defeat in last week’s local elections triggered ministerial resignations and growing calls for the prime minister to resign. Bond investors are concerned that Burnham in particular will oversee a loosening in fiscal policy, raising borrowing and limiting tax rises.
The Greater Manchester mayor previously suggested that defence spending should be excluded from the fiscal rules and spooked markets last year when he said governments should not be “in hock” to financial markets.
“There is a desire to spend further but limited appetite for either higher taxation or further borrowing. Such economic realities may prove a constraint to any fiscal ambitions,” Callum McLaren-Stewart, an economist at Citi, said.
Bill Papadakis, a strategist at Lombard Odier, the Swiss bank, said any new prime minister “would be subject to the same constraints that the current government is facing. The memory of the short tenure of [the] prime minister Liz Truss in 2022 … that unsettled the market with large unfunded tax cuts, could also curb the spending enthusiasm of any new leader.
“Contrary to some pre-election fears, the current Labour government has also kept a prudent fiscal stance since taking office in 2024, sticking to its fiscal rules and narrowing the government budget deficit from 5.2 per cent to around 4.3 per cent currently. At the same time, the economy’s current account balance has also improved from a deficit of 3.6 per cent in 2023 to just 2.4 per cent last year.”