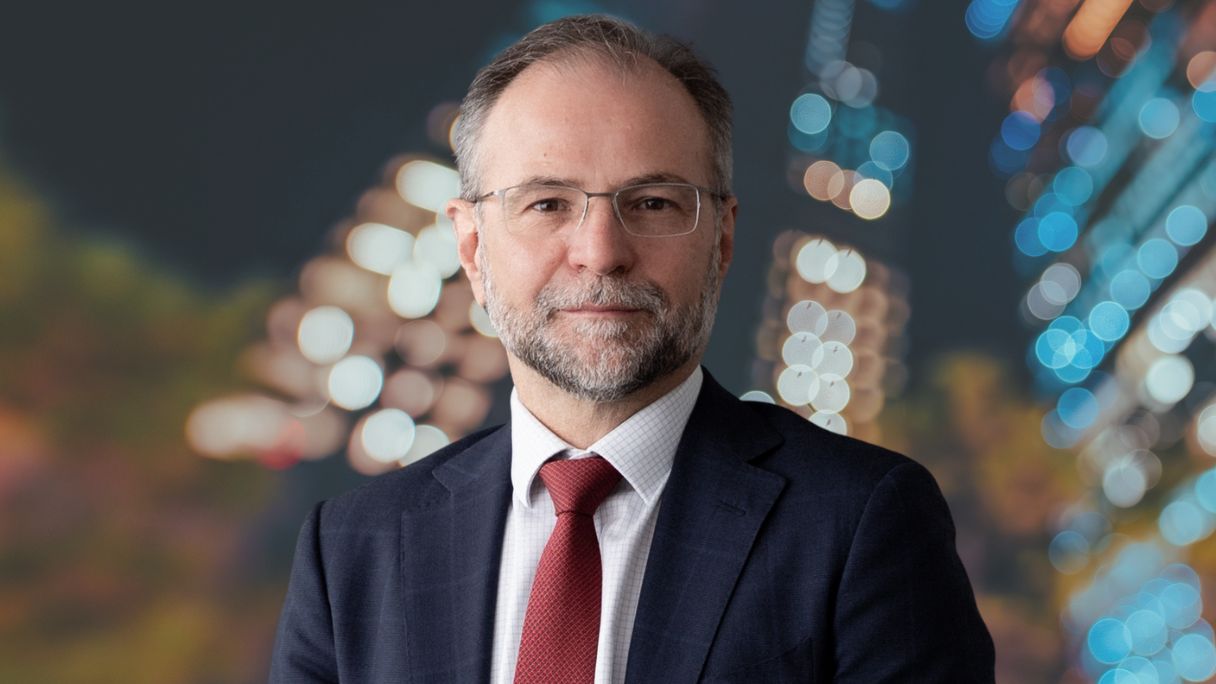
Bendigo Bank chief economist David Robertson expects the RBA cash rate to hold in August, but warns one more hike looms later this year, with 2027 cuts premature while core inflation stays stubbornly above target.
As the new financial year begins, David Robertson, chief economist at Bendigo Bank, expects the Reserve Bank of Australia to hold rates steady at its August meeting, buying homeowners a brief reprieve.
However, he argues the tightening cycle is not finished and dismisses talk of rate cuts in 2027 as premature while core inflation stays stubbornly above target.
“While the RBA held rates steady in June, it was clear they remain focussed on their dual mandate of price stability and full employment, issuing the blunt message they will do what it takes to achieve that outcome, including another hike to the cash rate,” Robertson says.
A pause in August is not the end of the story
Robertson’s central forecast has the RBA holding at its next meeting. Recent data, in his reading, supports a breather for borrowers after a run of tightening.
“It’s our prediction here at Bendigo Bank that Aussie homeowners will be able to catch their breath in August, with recent economic data pointing to a hold at the RBA’s next meeting,” he says.
That pause sits alongside an unresolved inflation problem. National unemployment holds at 4.4 per cent, evidence for Robertson that the labour market remains tight enough to sustain wage and price pressures.
Headline CPI eased to 4 per cent in the May data, a figure that alone might support a more relaxed stance. Core inflation tells a different story, rising to 3.6 per cent and likely, on Robertson’s assessment, to stay above target for at least another 12 months.
Core inflation, not oil, is the persistent constraint
Robertson separates the temporary from the structural. Oil prices have moderated as more shipping moves through the Strait of Hormuz, easing one source of imported inflation.
That improvement does not remove the case for further tightening, he argues.
“This doesn’t necessarily mean the RBA needs to tighten rates further, as oil prices have moderated and more ships make their way through the Strait of Hormuz. Our view remains the tightening bias will continue throughout the new financial year, with the risk of one more hike around year-end, with recent talk of rate cuts next year appearing premature,” he says.
That gap is consequential: market commentary treating softer headline inflation as an all-clear signal misses the point. Core inflation, stripped of volatile items, is the number the Reserve Bank actually targets, and it is moving the wrong way.
Rate cuts in 2027 need conditions that do not yet exist
Robertson sets out explicit prerequisites for any easing cycle, and none of them are close to being met.
“Rate cuts in 2027 would need several prerequisites: the underlying inflation rate would presumably need to be close to 2.5 per cent, and the RBA would need to form the view that the economy needs support.”
Compounding the case for patience, estimates of the neutral cash rate, the level at which policy is neither stimulatory nor restrictive, continue to rise and now sit around 4 per cent.
That implies the current cash rate is only mildly restrictive by the RBA’s own reckoning, leaving less room than headline numbers suggest for near term cuts.
The exception, Robertson concedes, is a sharper downturn bordering on recession, which would force the RBA‘s hand well ahead of schedule. It is not his central case, despite what he describes as several sources of pessimism both offshore and in local residential property.
Housing is cooling, but tight supply keeps a floor under prices
Robertson’s read on housing is one of divergence rather than a uniform correction. Auction clearance rates have fallen below 50 per cent across the capital cities, a level typically associated with a buyer’s market. Outright price falls, though, remain confined to Sydney and Melbourne. “There are concerns the slowdown may broaden,” Robertson says.
Bendigo Bank forecasts national dwelling prices flattening over the next 12 months, with risks skewed to the downside as recent tax changes work through the market.
Supply remains the offsetting factor: construction has not kept pace with softer demand, underpinning prices nationally.
Household resilience contrasts with a widening market gap
Household spending data still points to resilience, and with labour markets holding firm, Robertson assesses recession risk as low, provided the oil price has peaked. That domestic steadiness sits oddly against a stark divergence in equity markets.
The S&P500 gained 20 per cent and the Nasdaq more than 25 per cent last financial year, powered by optimism over a resolution to Middle East tensions and enthusiasm for AI investment. The ASX200 managed just 3 per cent over the same period.
Robertson expects Australia’s recovery from the 2026 slowdown to be linked to the same global technology investment theme driving offshore markets higher, though he cautions that “markets will be prone to corrections” along the way.
“In summary, the RBA cash rate may well plateau at or just above its current level for the rest of this year and for most of next, despite the economy decelerating,” he says.
What this means for portfolio positioning
For asset consultants and wealth managers setting positioning this financial year, Robertson’s framework points to a cash rate plateauing near current levels through most of 2027, not falling quickly.
That carries weight for fixed income duration calls, exposure to rate sensitive sectors such as residential property and retail, and the case for holding offshore equities while the ASX lags the AI led rally abroad.
Jobs, inflation and household spending data ahead of the RBA’s August meeting will be the figures that matter most, with Robertson expecting no change to the cash rate at that meeting.
Without a fresh global shock, he expects the stronger conditions evident at the start of this year to reassert themselves into 2027.