
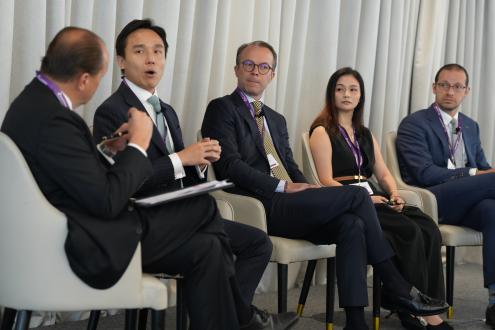
At the Hubbis Investment Forum – Hong Kong 2026, the third panel examined whether the recent growth of discretionary portfolio management (DPM) in Asia can become a durable and scalable business. Market shocks, concentrated portfolios and succession needs are increasing demand for professional management, but adoption still depends on trust, pricing and the ability of relationship managers to explain what clients retain control over.
The discussion favoured a hybrid model, with the portfolio core managed under an agreed mandate and advisory accounts retained for company shares, private investments and opportunistic ideas. Firms still have to personalise the service efficiently, align adviser incentives and use technology without weakening the human relationship.
Chair: Arjan de Boer, Managing Director, Head of Private Banks Coverage for Asia-Pacific, Financial Institutions Group Asia-Pacific, Crédit Agricole CIB
Panellists
Aleksey Mironenko, Global Head of Investment Solutions, Leo Wealth Global
Jack Siu, Head of Discretionary Portfolio Management, Asia, Lombard Odier
Jan Boes, Executive Director, Bordier & Cie Singapore
Jancie Wong, Head of Investment Solutions, Annum Capital
Key Takeaways
Demand for DPM has strengthened after market shocks exposed the cost of excessive cash holdings, concentrated portfolios and ad hoc trading.
Delegation does not remove client control when the mandate defines the risk budget, base currency, restrictions and permitted markets.
The most workable model is a discretionary core with advisory satellites for client-led ideas, company shares, private investments and tactical opportunities.
Adoption varies across Asia because clients have different concentrations, market experience, family circumstances and expectations of professional advice.
DPM can produce steadier long-term revenue than transaction-led activity, although it does not guarantee better performance or greater short-term profitability.
Relationship-manager training and incentives are central to scale. Advisers must understand the mandate and see DPM as support for the client relationship.
Artificial intelligence can improve research efficiency, but family context, mandate design, qualitative judgement and client reassurance still require people.
Market Shocks Exposed the Cost of Inaction
Several years of disruption changed how some Asian clients viewed delegation. The Chinese property downturn, trade tensions and sharp market moves encouraged clients who had previously managed their own portfolios to retreat into cash. The response reduced immediate discomfort, but left portfolios poorly positioned when conditions stabilised.
One panellist described the scale seen among some clients: “At the peak of uncertainty, 50% to 80% of the portfolio was sitting in cash. That was not strategic asset allocation; it was risk paralysis.” The figures were presented as client examples rather than a market-wide estimate, but they illustrated the behavioural problem that DPM was being asked to solve.
A managed mandate can keep capital invested within agreed risk limits while still allowing exposure to themes such as artificial intelligence and semiconductors. Clients may return to self-directed trading when markets appear calmer, yet the longer-term case for DPM rests on consistent portfolio construction and risk management rather than the outcome of a few individual trades.
Demand Comes from Different Client Problems
Panellists reported double-digit growth in discretionary business at a number of banks, external asset managers and wealth managers, although no industry dataset was cited. At two firms represented in the discussion, speakers said discretionary mandates accounted for roughly 60% to 80% and around 90% of assets, respectively. Those figures describe individual businesses rather than the Asian market. DPM remains less established across much of the region than in North America, Europe and Australia. Differences in adviser remuneration and the continued appeal of transaction-led revenue were offered as part of the explanation.
Clients familiar with discretionary management from time spent abroad were among the quickest to adopt it. Demand also came from people whose confidence in an advisory relationship had been damaged, sometimes through leverage or products they no longer understood. One participant recalled the complaint that ended such a relationship: “You convinced me to buy these investments and use margin, and now you are asking me to put in more cash.”
The need also differs by market. Panellists encountered Taiwanese clients seeking diversification away from concentrated technology exposure, Japanese clients focused on loss control and Chinese families looking beyond domestic assets after losses in high-yield debt. Entrepreneurs approaching an intergenerational transfer added another layer, because the portfolio had to reflect both investment objectives and family arrangements.
Control Is Being Recast as Governance
The reluctance to delegate often begins with a fear of losing control. Panellists said this concern frequently came from treating control as approval of every transaction rather than authority over the design of the mandate.
A panellist described the distinction this way: “The client keeps control of the total asset allocation but does not have to approve every trade.” In practice, the client sets the portfolio objective, risk budget, base currency, restrictions and permitted markets. The manager exercises discretion only inside those boundaries.
That distinction becomes more important as portfolio size and family complexity increase. A sizeable mandate should not automatically lead to an off-the-shelf portfolio. Panellists favoured tailoring the permitted exposures and constraints to the client’s circumstances, including concentrated business interests, liquidity needs and the intended purpose of the assets.
The Scalable Model Is Hybrid
The panel separated an ongoing investment strategy from a client-led transaction. A family whose business wealth is concentrated in Asian technology may use DPM to build a liquid portfolio with different sources of risk. If the same client later wants a particular private fund or a tactical semiconductor position, that idea can remain advisory.
This division supports a discretionary core with advisory satellites. The core handles asset allocation, diversification and rebalancing, while the satellites accommodate company shares, private-market holdings and opportunities the client wants to pursue directly. The models can coexist without forcing every asset or decision into the same service.
Firms can share research, portfolio construction and execution across mandates while tailoring client limits. Scale does not require identical portfolios; advisory holdings and client-specific constraints remain visible alongside the managed core.
Economics Favour Relationships over Transactions
The panellists did not claim that discretionary management always produces better returns than advisory services. Results depend on asset allocation, fees, product selection, manager skill and client behaviour. The economic difference lies more in how the relationship earns revenue and how often a trade is needed to generate it.
One participant argued that DPM can be less profitable for a wealth manager in the short term, but steadier over a longer period because revenue is linked to assets under management (AUM) or a fixed fee. As the panellist put it, “We do not start 1 January asking how we will generate revenue that year. The fee is already based on the assets entrusted to us.”
The model may also help clients remain invested during a drawdown, when advisory activity can slow as clients avoid decisions or move into cash. Revenue still falls when markets decline or assets leave, and a discretionary mandate cannot remove investment losses. Its commercial attraction is a more stable asset-management relationship rather than a promise of higher returns.
Distribution Begins with the Relationship Manager
Investment capability alone will not make DPM scalable. Relationship managers (RMs) must be able to explain the service, show how the mandate limits discretion and identify which client problem it addresses. Many RMs have spent years working within product-led or transaction-led models, so the change requires more than a new presentation.
One panellist reduced the issue to a simple rule: “An RM will not sell something they do not understand.” Training must cover the portfolio’s purpose, decision process, restrictions and likely behaviour in difficult markets. It must also give the adviser enough confidence to answer concerns about control, fees and the manager’s authority.
If advisers view DPM as a threat to their value or compensation, they have little reason to introduce it. Several participants described the investment team as operating support that handles the portfolio continuously, giving the RM more time to understand the family, maintain the relationship and find new business. Experience through the global financial crisis and the Chinese property downturn had also shown some RMs how quickly transaction-led relationships could weaken when clients were under pressure.
AI Improves Efficiency While Advisers Retain Judgement
Artificial intelligence (AI) is already changing parts of the investment workflow. Panellists said it could summarise research, extract relevant points and help teams build portfolio views more efficiently. Used carefully, those gains can lower costs and give investment professionals more time for analysis and client work.
Research summaries are only one part of the job. A DPM team must understand whether a portfolio supports intergenerational transfer, how it relates to a family’s core business holdings and what degree of loss the client can tolerate. One panellist also questioned whether an AI system listening to a management meeting would recognise the significance of an executive repeatedly mentioning another company. That kind of interpretation depends on context as well as the words recorded.
Client reassurance remains another human responsibility. When markets fall, a model cannot replace the adviser who explains the mandate, tests whether the family’s circumstances have changed and prevents a fearful decision from undermining the plan. The panel treated AI as decision support rather than a substitute for the investment team or the relationship.
The Next Generation Will Scrutinise Value
Younger clients were described as receptive to discretionary management but more demanding about what they receive for the fee. Greater familiarity with markets, technology and financial information makes them willing to challenge expected yields, portfolio design and the cost of each layer.
Fee layering is a particular concern. A client may pay for the mandate and then incur further charges through underlying funds or bank-owned products. Even where the gross performance is acceptable, the arrangement becomes harder to defend if proprietary holdings or multiple fees leave the client with little evidence of additional value.
A standardised 60/40 core-satellite portfolio may therefore face more resistance than a mandate offering access or expertise the client cannot obtain elsewhere. One panellist found greater receptiveness to portfolios built around selected private transactions and said some clients would accept a performance fee when the source of potential net return was clear. That remains a firm-specific experience, but it shows why personalisation and transparent pricing are linked.
Conditions for a Durable DPM Market
The panel left open whether the current growth will become structural. A stronger test will come when markets calm and clients again feel confident trading for themselves.
Inside firms, RMs need to explain governance and fees clearly. Investment teams must personalise mandates at a viable cost, while technology should improve research without weakening human advice. The quality of that execution will determine whether recent growth lasts.
Disclaimer: This article summarises a panel discussion and reflects information available as at 21 September 2026. It is provided for general information only and does not constitute, and must not be construed or relied upon as, tax, legal, financial, investment or other professional advice, guidance or a recommendation. The information may not apply to individual circumstances, particular products or every jurisdiction. Hubbis accepts no responsibility or liability for any action taken, or not taken, in reliance on this article. Readers should obtain independent advice from appropriately qualified professionals before making any decision.