
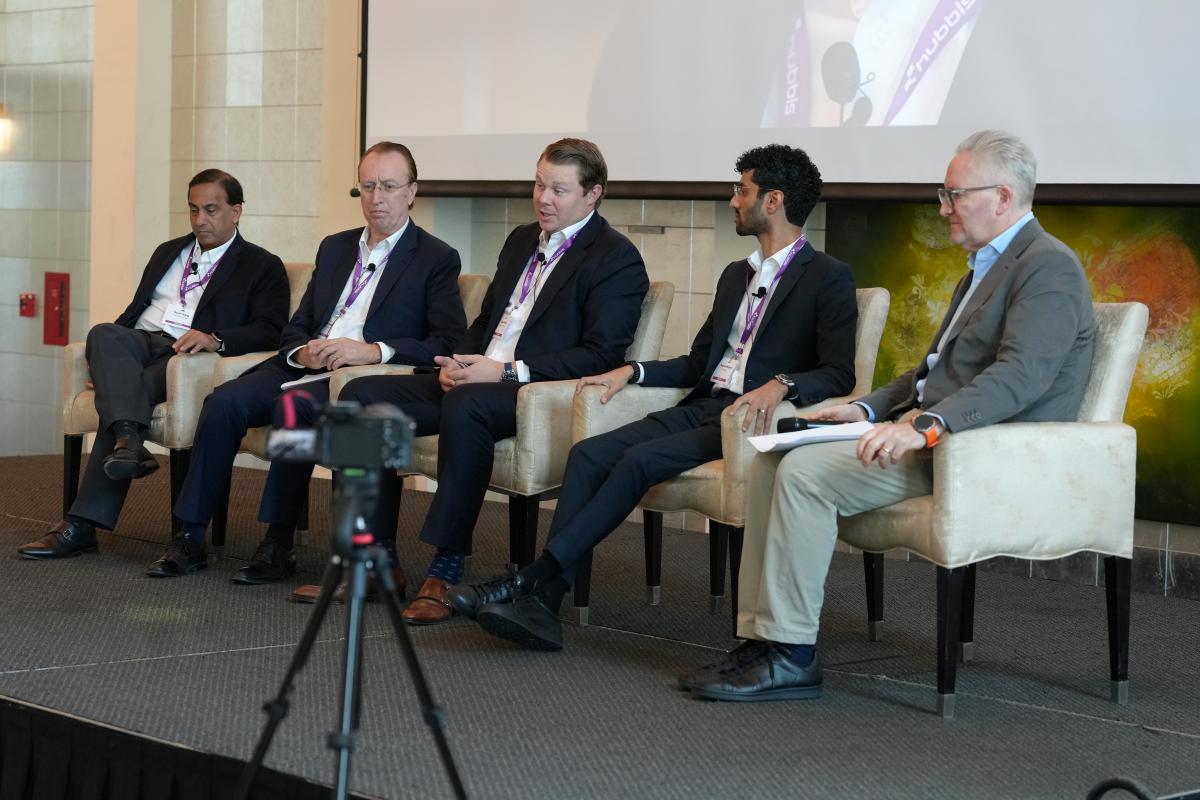
Artificial intelligence (AI) is making information and routine analysis cheaper to obtain. That changes the standard by which wealth managers must prove their value. The second panel at the Hubbis Middle East Private Capital Forum 2026 examined whether faster research, broader data and more scalable advice lead to better decisions for clients, rather than simply more output.
The firms represented were already using AI to compress preparation and build tools around their own workflows. The discussion moved beyond adoption itself to consistency, risk, trust and the economics of advice. An adviser remains responsible for the judgement and relationships behind a recommendation, even as the machinery for producing it changes.
Chair: Michael Stanhope, Founder and Chief Executive Officer, Hubbis
Panellists
Sunil Garg, Managing Director, Chief Investment Officer, Lighthouse Canton
Gary Dugan, Chief Executive Officer, The Global CIO Office
James Haller, Founder and Chief Executive Officer, Vesper Wealth Advisors
Raaed Sheibani, Country Manager, UAE, StashAway
Key Takeaways
AI can reduce the time spent assembling a client’s financial picture and turn scattered market information into tailored research, but speed matters only if it improves the decision.
Shared data, testing and risk frameworks can make advice more consistent across advisers and markets. Experience is still needed to interpret and challenge the output.
Digital visibility gives clients control and helps them understand portfolio gaps. Complex family needs, succession and private-market access continue to depend on people.
Client confidentiality, source quality, numerical checks and due diligence become more important as firms put AI into everyday workflows. Responsibility for the result stays with the adviser.
As routine allocation and information tasks become easier to automate, fees and roles built around those tasks face pressure. Freed-up time must produce more valuable advice.
Investing in AI requires a view of sustainable earnings and where the technology moves margins, rather than a verdict based on headline valuation multiples alone.
From More Information to Better Decisions
AI is already changing the amount of work an adviser can do before a client conversation. In one workflow, gathering a client’s financial information and forming a usable picture has fallen from days to hours. Other applications bring together holdings, research and market updates that would otherwise sit across separate platforms. A chief investment officer can survey unfamiliar developments quickly instead of working through each source in turn.
One panellist reduced the test to accuracy, speed and scale: “If a technology doesn’t meet those criteria, it’s useless.” The ability to build a customised internal platform relatively quickly is useful, but a polished dashboard is only the first step. Data must lead to a clearer view of the client’s circumstances and a decision the adviser can explain.
The same gains extend to testing strategies and processing large data sets. They do not make the resulting analysis self-validating. AI can surface an argument, assemble evidence or expose a missing question; an investment professional still has to decide which information is relevant and whether the conclusion follows.
Consistency and Risk Become Part of the Proposition
A repeatable investment process matters when several advisers serve clients in different markets. Similar mandates should not receive conflicting answers simply because the meeting took place with a different person or on a different day. Common data, portfolio construction rules and a risk framework can narrow that gap without requiring every family to hold the same portfolio.
Real-time information can make exposures easier to monitor and help a team respond when conditions change. Risk modelling received less attention than investment ideas in the discussion, but it is central to whether a firm can deliver against its mandate. Faster research has limited value if the adviser cannot see how a proposed position changes the risks the client already carries.
The most useful role for AI is therefore to widen the field of inquiry while making the process more disciplined. One panellist likened it to “a super library”. The professional task is to interrogate what it returns, bring experience to bear and put the conclusion into the context of a particular portfolio.
Digital Control Does Not Resolve Family Complexity
A digital platform can give clients an accessible view of holdings, choices and potential gaps in a portfolio. That visibility may prompt better questions and make an advisory conversation more productive. It also allows a firm to serve more people without making every interaction a manual exercise.
Larger or more complex relationships demand something further. Family dynamics, succession and unspoken concerns can alter what a client needs even when the figures are unchanged. “People want the comfort, people want the conversation, people want the depth,” a panellist said. Those qualities are especially relevant when a family is deciding who should control assets or how the next generation will participate.
Technology can organise follow-ups and prepare an adviser for that meeting. It cannot create a trusted relationship through a screen alone. Nor does it manufacture access to private-market opportunities, where networks and relationships with the people behind an investment remain part of the service.
Trust Requires Ownership of the Output
The easier it is to generate research or a client note, the easier it is to pass along a plausible error. Figures, sources and the reasoning between them need to be checked before advice reaches a client. An AI review of a lengthy investment document may suggest useful due-diligence questions, but it can also miss an issue that matters. “You’ve got to take ownership of the output,” a panellist said.
Confidentiality is equally practical. A system that aggregates family holdings or drafts personalised material must protect the information entered into it and control who can use the result. Panellists expected greater scrutiny of data security, inputs and AI-assisted due diligence as the technology spreads. Firms need controls over those workflows, as well as accountable review of what they produce.
Human review is more than a final spelling check. It means testing whether a number is correct, whether a source is suitable, whether an apparent pattern has been overread and whether the recommendation fits what the adviser knows about the client. That scrutiny is part of the value a professional still claims to provide.
Automation Raises the Bar for Advisers
Clients can increasingly obtain basic information and asset-allocation suggestions themselves. A firm that charges primarily for producing those outputs will have to defend the fee as the cost of production falls. AI also changes the staffing question: people who once spent much of the day gathering material need the judgement and technical fluency to use the time it releases.
“The lazy won’t last,” one panellist said. The point was blunt, but the commercial logic is clear. Automating a mundane task creates capacity; it does not automatically create value for the client. Advisers must use that capacity to challenge an investment case, construct a better solution, interpret risk or handle a family problem that a generic output cannot settle.
For clients, the test remains the outcome. They may appreciate a faster answer or a transparent digital interface, but neither proves that a mandate has been met. Consistency, appropriate risk taking and a useful response to the client’s actual needs are firmer grounds for differentiation than the mere presence of AI in the process.
Investing in AI Is a Separate Judgement
Using AI in a wealth business and buying companies exposed to it are different decisions. High valuations may be justified if earnings grow into them, but that depends on the durability and distribution of future profits. The panel’s investment discussion focused less on declaring the entire theme expensive than on asking which businesses will capture the gains.
In software, for example, AI could put pressure on established pricing and margins without removing the need for the underlying products. Some value may move to new providers or customers; others may be able to defend their position. Private AI companies add another difficulty because public-market comparisons and reliable financial information may be limited. An impressive growth forecast is therefore a case to examine, not a substitute for valuation discipline.
The same demand for evidence runs through the operational discussion. Whether a firm is paying for an AI tool, reorganising its advisers around it or buying an investment linked to it, the relevant question is where the economic benefit appears and who ultimately keeps it.
**
Disclaimer: This article summarises a panel discussion and reflects information available as at 28 September 2026. It is for general information only and is not tax, legal, financial, investment or other professional advice or a recommendation. Its contents may not apply to individual circumstances, products or jurisdictions. Hubbis accepts no responsibility or liability for actions taken or omitted in reliance on it. Readers should obtain independent advice from qualified professionals before making any decision.