In a market where every wealth manager claims to offer alternatives and every fund house insists its strategy deserves a place in the portfolio, the real test may not be access to product but the ability to distinguish genuine opportunity from diminishing returns dressed in structural complexity. The institutions that allocate well are not those with the longest approved lists but those with the clearest view of where value is genuinely being created and whether their own teams can articulate it to clients.
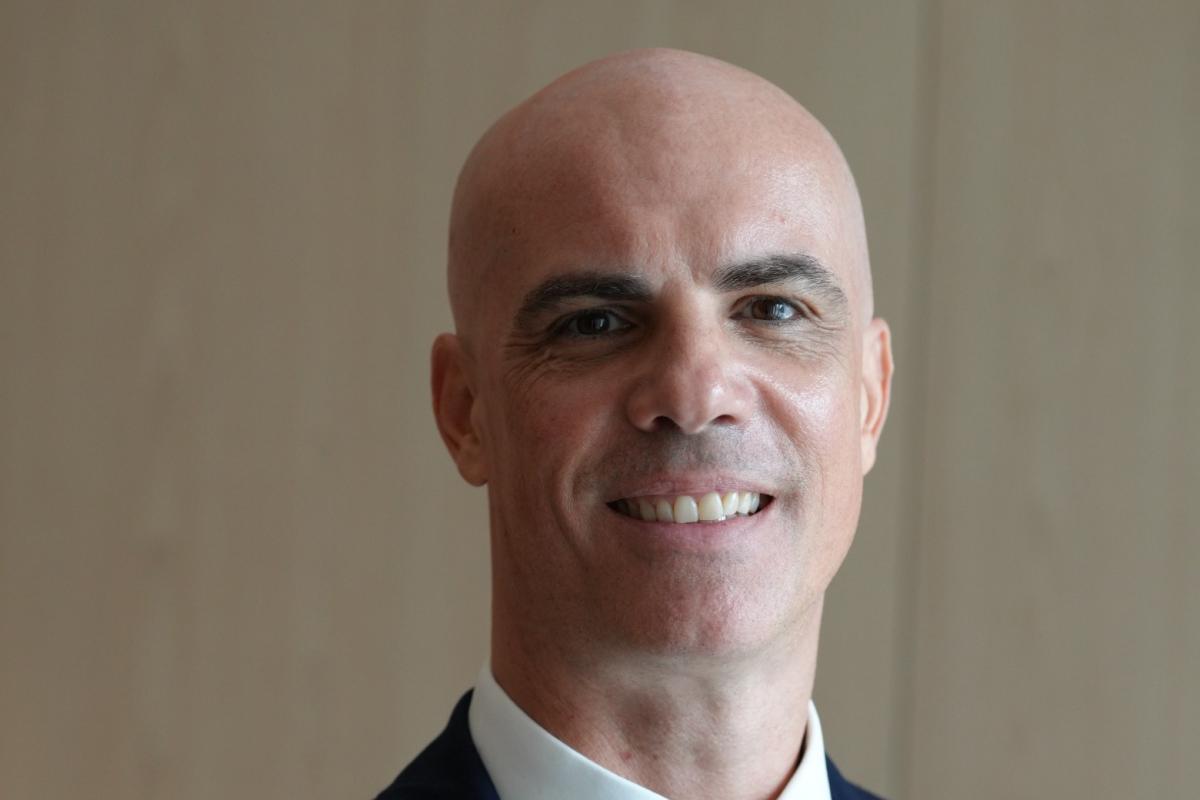
At the Hubbis Investment Forum – Hong Kong 2026, the second panel discussion of the day examined what is actually entering private client portfolios across Asia and what continues to languish on the shelf. Juan Aronna, Chief Executive and RBC Hong Kong Branch Head, Investment Solutions and Products, Asia, at RBC Wealth Management, offered a direct and conviction-led account of how the economics of alternatives are shifting, where the real premium now sits, and why the gap between approval and allocation remains one of the industry’s most persistent and self-inflicted problems.
Key Takeaways
Capital is flowing most strongly into illiquid alternative strategies, with recent market volatility reinforcing client demand for exposures that sit outside conventional public market allocations.
The traditional illiquidity premium has been substantially eroded by layered fee structures and elevated borrowing costs, particularly in highly leveraged strategies.
Aronna sees a “complexity premium” remaining in niche areas where specialist knowledge and limited investor participation can make opportunities more attractive, even as the traditional illiquidity premium is eroded.
Due diligence red flags that immediately end the conversation include an inability to explain value creation in simple terms, conflicts of interest, excessive leverage, and dependency on a small number of key individuals.
Approved products that fail to gain traction with front-line advisers do so primarily because relationship managers may fear appearing uninformed, and because platforms launch too many strategies without allowing adequate time for training and absorption.
Where the Capital Is Moving
Aronna was clear about where the momentum sits. The alternative allocations attracting the most capital at RBC Wealth Management in Asia are concentrated in illiquid strategies rather than liquid alternatives, reflecting a client base that is willing to accept longer lockup periods in exchange for what it perceives as a differentiated return stream. Recent market dislocations, he noted, have accelerated that trend, with volatility prompting clients to seek exposure to asset classes that behave differently from public equities and fixed income.
On the traditional side of the portfolio, the shift is equally pronounced. Aronna identified fixed income as a major source of funding for alternative allocations, while also pointing to strong demand for structured products. He said the shift was already visible in revenues from the traditional fixed-income business.
From Illiquidity Premium to Complexity Premium
Aronna emphasized in the discussion his reframing of where the genuine premium in alternatives now resides. The concept of the illiquidity premium, he argued, remains valid in theory but has been heavily diluted in practice. Subscription fees, management fees, and performance fees collectively erode the return that investors receive for locking up their capital. When leverage is added to the equation and borrowing costs remain elevated, the net benefit of illiquidity narrows further still.
“We are seeing that the illiquidity premium somehow has disappeared,” Aronna said. “But what is still there is the complexity premium.”
The distinction is important. The complexity premium, as Aronna described it, is not about structural opacity for its own sake. It is about scarcity. Strategies that involve small company lending, specialised real estate workouts, or niche infrastructure assets are inherently harder for investors to access and evaluate. That difficulty creates a natural barrier to entry, and in sectors where few investors are willing or able to commit capital, the pricing dynamic favours those who do. The return, in other words, is a function of the capital scarcity that complexity produces rather than the lockup terms themselves.
The implication for portfolio construction is that the assessment framework must shift. Evaluating an alternative strategy purely on the basis of its liquidity terms and headline return misses the question that matters most: whether the strategy operates in a space where genuine scarcity of investor capital creates a durable pricing advantage.
Red Flags That End the Conversation
Aronna was equally direct about the due diligence criteria that disqualify a fund from consideration regardless of its historical performance. His first test is one of communicability. If the value a strategy generates cannot be explained in simple terms, the conversation is already over.
Beyond that threshold, he identified three structural red flags. Conflicts of interest represent an immediate concern. High leverage, particularly in an environment of elevated borrowing costs, raises the risk profile beyond what the return can justify. And dependency on a small number of key deal makers introduces a fragility that no amount of past performance can offset.
“The past performance tells you that the fund is great,” Aronna said. “But these red flags tell you what still can go wrong.”
The framework is deliberately binary. A strategy either passes these tests or it does not, and no strength in one area compensates for a failure in another. For asset managers seeking access to the RBC platform, the message is clear: structural integrity and transparency are preconditions, not differentiators.
Bridging the Knowledge Gap
On the question of why approved products see limited uptake with advisers, Aronna offered a diagnosis that was both candid and uncomfortable for the industry. Investment counsellors, he noted, are primarily focused on supporting clients with advice, rather than study fact sheets. When a product sits unused on the shelf, the explanation is rarely that the strategy lacks merit. It is that the people responsible for recommending it may not feel fully prepared to do so.
Aronna identified two root causes. The first is largely psychological. He observed that most relationship managers across the industry tend to gravitate toward strategies they can explain with confidence. This creates a natural preference for familiar products over new ones. When new or complex products are launched, the hesitation isn’t the merit of the product, it’s about unfamiliarity.
The second cause is operational. Private banks, Aronna argued, may routinely launch too many products in too short a period, overwhelming the front line with new strategies before the previous batch has been properly absorbed. Without adequate time for training, question-and-answer sessions, and genuine comprehension, most relationship managers default to what they already know.
“If they feel that this is outside of their range of knowledge, it stays on the shelf,” Aronna said.
The implication is that the implementation gap appears largely structural. It represents both a communication opportunity and a pacing consideration, and the responsibility sits as much with the platform as with the asset manager.