
Free Newsletter
Get the hottest Fintech Singapore News once a month in your Inbox
Digital lenders across the Asia Pacific tend to face the same set of pressures. In some countries, large populations remain unbanked and still need formal access to credit. Lenders also face customers who expect access to credit within the same superapps they use for payments and everyday spending.
Couple this with the need to constantly launch new products without spending months rebuilding the underlying technology each time, and it makes one thing clear: that in lending, speed and flexibility matter as much as reach and accessibility.
How can your lending business scale responsibly and effectively, especially when speed to market is critical? The answer lies in pairing a configurable, cloud-native lending core with deep knowledge of the local market it serves.
GCash, the leading finance superapp operated by Mynt (Globe Fintech Innovations, Inc.), has built a lending business through Fuse Financing Inc., which now serves more than 11 million borrowers across the Philippines, with Mambu as its lending core.
To explore how this plays out in practice, we spoke with David Becker, the Managing Director and Head of APAC Sales at Mambu, and Maribeth Tiu, the Chief Technology and Operations Officer at Fuse Financing Inc.
Built Lending Products for Varying Financial Needs
Fuse’s lending business started with one simple aim: to give Filipinos access to credit. Borrowing needs in the Philippines were far from uniform.
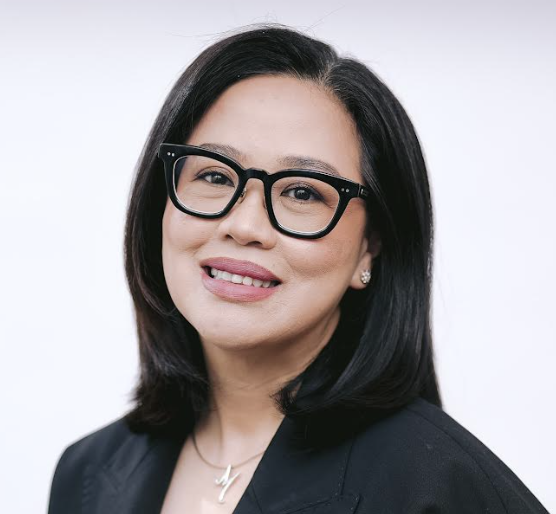 Maribeth Tiu
“We wanted the right type of credit for different moments in the customer’s financial life, because most of them already have access to credit,” Maribeth said.
Mynt moved to Mambu’s cloud-native platform back in 2017, after its previous setup became a constraint.
Product changes required heavy customisation, and building a new lending proposition could take months as it ran on a legacy platform that required slow and manual processes.
“The biggest thing Mambu established was flexibility,” Maribeth said.
Rather than hardcoding every lending product into the core, Fuse’s team could configure different products and connect the core to other capabilities through APIs. This allowed the company to build experiences on top of a stable, reusable foundation.
“With Mambu, we moved towards a much more configurable model. Development, which once took us months, switched to weeks.”
This enabled GCash to build different experiences on top of Mambu.
“It gave our team room to keep changing the proposition around a stable lending foundation. At our scale, that separation became increasingly important,” she added.
Becker credited the same shift from the Mambu side.
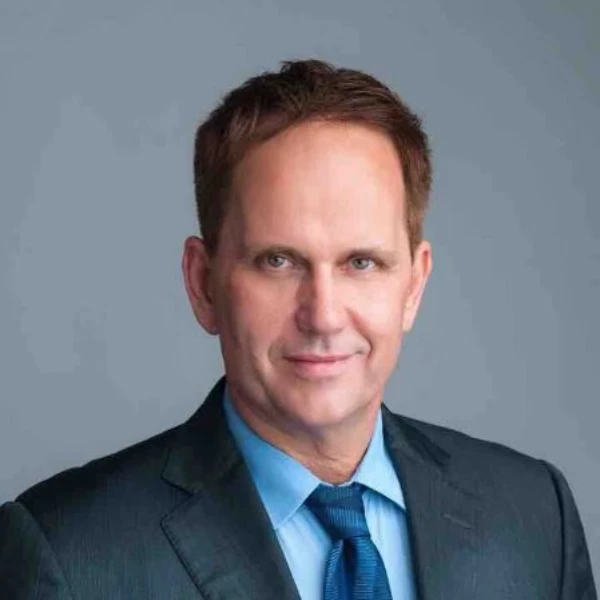 David Becker
“We’re able to get our clients, like Mynt, within their expected timeframes, so that they can get to market and win a new customer base. GCash saw a strategic plan of growth, and the composable banking optionality that Mambu has, open APIs and the cloud-native infrastructure, really worked well together to see that growth through.”
That range of needs has scaled into a business serving more than 11 million unique borrowers, with around 406 billion pesos in loans disbursed by the end of 2025, according to Maribeth.
The Right Product for the Right Customer, at the Right Time
Some Philippine lending customers needed a small amount for transportation, others for groceries or paying off an appliance in instalments.
Maribeth gave an example of GLoan Sakto, a nanoloan product built around a local borrowing habit. Sometimes, a person needed only 100 or 300 Pesos for transport or a mobile reload, and that traditionally meant borrowing from friends, family, or worse, an informal lender.
“Rather than starting with what lending product can be built, the conversation started with what financial gap our customer was actually experiencing,” Maribeth said.
Eligible GLoan Sakto customers can now receive loan offers starting from as low as 100 pesos with a short repayment period, directly through the GCash app.
“The technology has to make that practical,” she elaborated. “So our customer experience eligibility and decision capability work together with the lending core, which runs underneath all our products.”
GCash’s scaling needs played into that same precision. While the company had the structure and team to support the business as they innovated more products, they still needed to protect the trust and safety of their customers.
This is critical as GCash manages multiple products, integrations, and servicing requirements as they continually adapt their lending portfolio.
“Mambu has out-of-the-box webhooks or APIs that we can use,” Maribeth explained. “We also have additional capabilities, like creating new reminder collection actions, also powered by Mambu’s capabilities.”
Maribeth zeroed in on the volume of transactions GCash processes on a daily basis. The company focuses on creating an experience where they process all those transactions and give those necessary reminders.
It took several brainstorming sessions with Mambu to figure out how to solve that challenge. Mambu was always by their side, even in those challenging moments.
“They didn’t actually quit until we solved the problem. That’s a wow factor for me.”
Day-to-day, GCash now handles most new product and service builds independently, since it knows Mambu’s capabilities well after years of working together.
“If there are innovations, Mambu has an architect we can brainstorm with for these. Should we need additional support, that’s when we tap Mambu.”
What Will it Take for a Lending Business to Succeed in APAC?
Speaking more broadly on what a bank, fintech, or digital platform should assess when choosing a core lending partner, David said that firstly, coordination is always crucial, and that partnership is key.
“It’s also understanding the requirements to customise, to give them that market edge. We pride ourselves on speed to market and being able to respond with those enhancements. Regulatory and compliance are also always top of mind.”
Next, he pointed out that service reliability is the bedrock of any successful lending operation. David elaborates,
“Service reliability, consistency, and resilience are always crucial. We (Mambu) pride ourselves on our SLAs, our service level standards, and making sure we correct any development as it happens.”
Beyond operational excellence, several critical competencies distinguish winners from the rest. Cybersecurity, for one, has become an absolute imperative, especially as lending platforms expand their reach.
David also named credit risk infrastructure and funding diversification. He pointed to Mynt as a key example, offering solutions spanning nano loans to larger loan sizes.
The next inflexion point lies in how lending businesses deploy AI.
“Mambu is focused on the agentic core, going beyond just being able to retrieve data,” David shared. “How can you deploy AI agents that can allow for a deeper analysis to create new business opportunities? We are rolling that out in the market now.”
This is where Mambu’s Intelligent Core builds on the composable foundation financial institutions already use today.
Through Mambu Agentic, its agentic AI layer, AI can connect more closely with core banking and payments, enabling institutions to move beyond retrieving information and towards agents that can analyse data, support decisions, and take action within banking operations.
For lenders, this creates opportunities to use intelligence closer to where products, customer data, and financial decisions come together, while retaining the flexibility to adapt products and experiences as customer needs change.
 Source: MambuEmbedded Finance and the Discipline Behind the Opportunity
Embedded financing within superapps is a trend that’s driving growth globally and regionally too, David shared, particularly in large markets like the Philippines and Indonesia where substantial unbanked populations represent untapped opportunity.
The model extends into Islamic banking, a key driver across Indonesia and Malaysia, as well as BNPL solutions that have seen elevated growth in Australia and New Zealand.
“You’ve got to tick all the right boxes to be well-positioned in the marketplace, and the demand is there. The expectations of users, particularly younger generation users, who are very familiar with the availability of competitive superapps in the market. You’vegottobeabletoretaintheir attention.”
GCash already has that attention to work with. Lending was built into an ecosystem customers already used for bills, purchases, insurance, and everyday payments, and that activity feeds GScore, the company’s trust score.
“GCash activity contributes to GScore, alongside other eligibility criteria that are used for our credit product, but we have to use that advantage carefully,” Maribeth explained. “The objective isn’t to lend more money, simply because we can reach them (GCash customers).”
The aim is a product matched to what a customer needs and can manage in their broader financial journey.
Designing Lending Infrastructure That Scales With You
The most resilient digital lending businesses will be those that hardwire flexibility into their technology from the start, ensuring that their lending infrastructure can absorb greater scale.
“Choose an architecture that lets you change a product channel and experience without having to replace the core every time,” Maribeth shared. “You may not need that flexibility on day one, but if you succeed, you’re definitely going to need it.”
For GCash, that next stretch of growth sits alongside a bigger corporate milestone.
Mynt, the parent company of GCash, has been approved for IPO by the Securities and Exchange Commission (SEC) of the Philippines for up to PHP 92.32 billion.
Maribeth was clear that she does not see an IPO as an end point, describing it instead as one stage in a much longer growth journey.
The work does not change: to keep making GCash capable of serving more customers and more financial needs, and supporting increasingly sophisticated products, without making the platform harder to operate.
“The next milestone for us isn’t simply lending more,” Maribeth said. “It’s becoming better at deciding when, how, and what we sell.”
Keen to know more? Explore how Mambu Intelligent Core is enabling lenders across APAC to move faster and adapt more freely.
Featured image edited by Fintech News Hong Kong based on an image by Who is Danny on Magnific