In 2025, the Generative AI mobile apps market reached an all-time high, generating $3B in revenue by the end of the year. It also demonstrated the fastest growth out of all the app segments, with revenue going up 273% YoY (year-over-year) and downloads growing by 178% YoY. While these figures alone suggest that the market is highly attractive to enter, it’s worth completing a deeper analysis to confirm this hypothesis.
In the recent Mobile Market Landscape 2026 report, AppMagic dives into Generative AI’s global and regional market dynamics, reviews the fastest-growing genres and their leading apps, and analyses the most effective monetization models.
Is the Generative AI app market entering its maturity phase?
One of the key success factors in launching a highly monetizable app is entering the market early enough—before it becomes overly saturated, when entry barriers are still relatively low, there are no dominant monopolizers, and the market itself is showing promising growth.
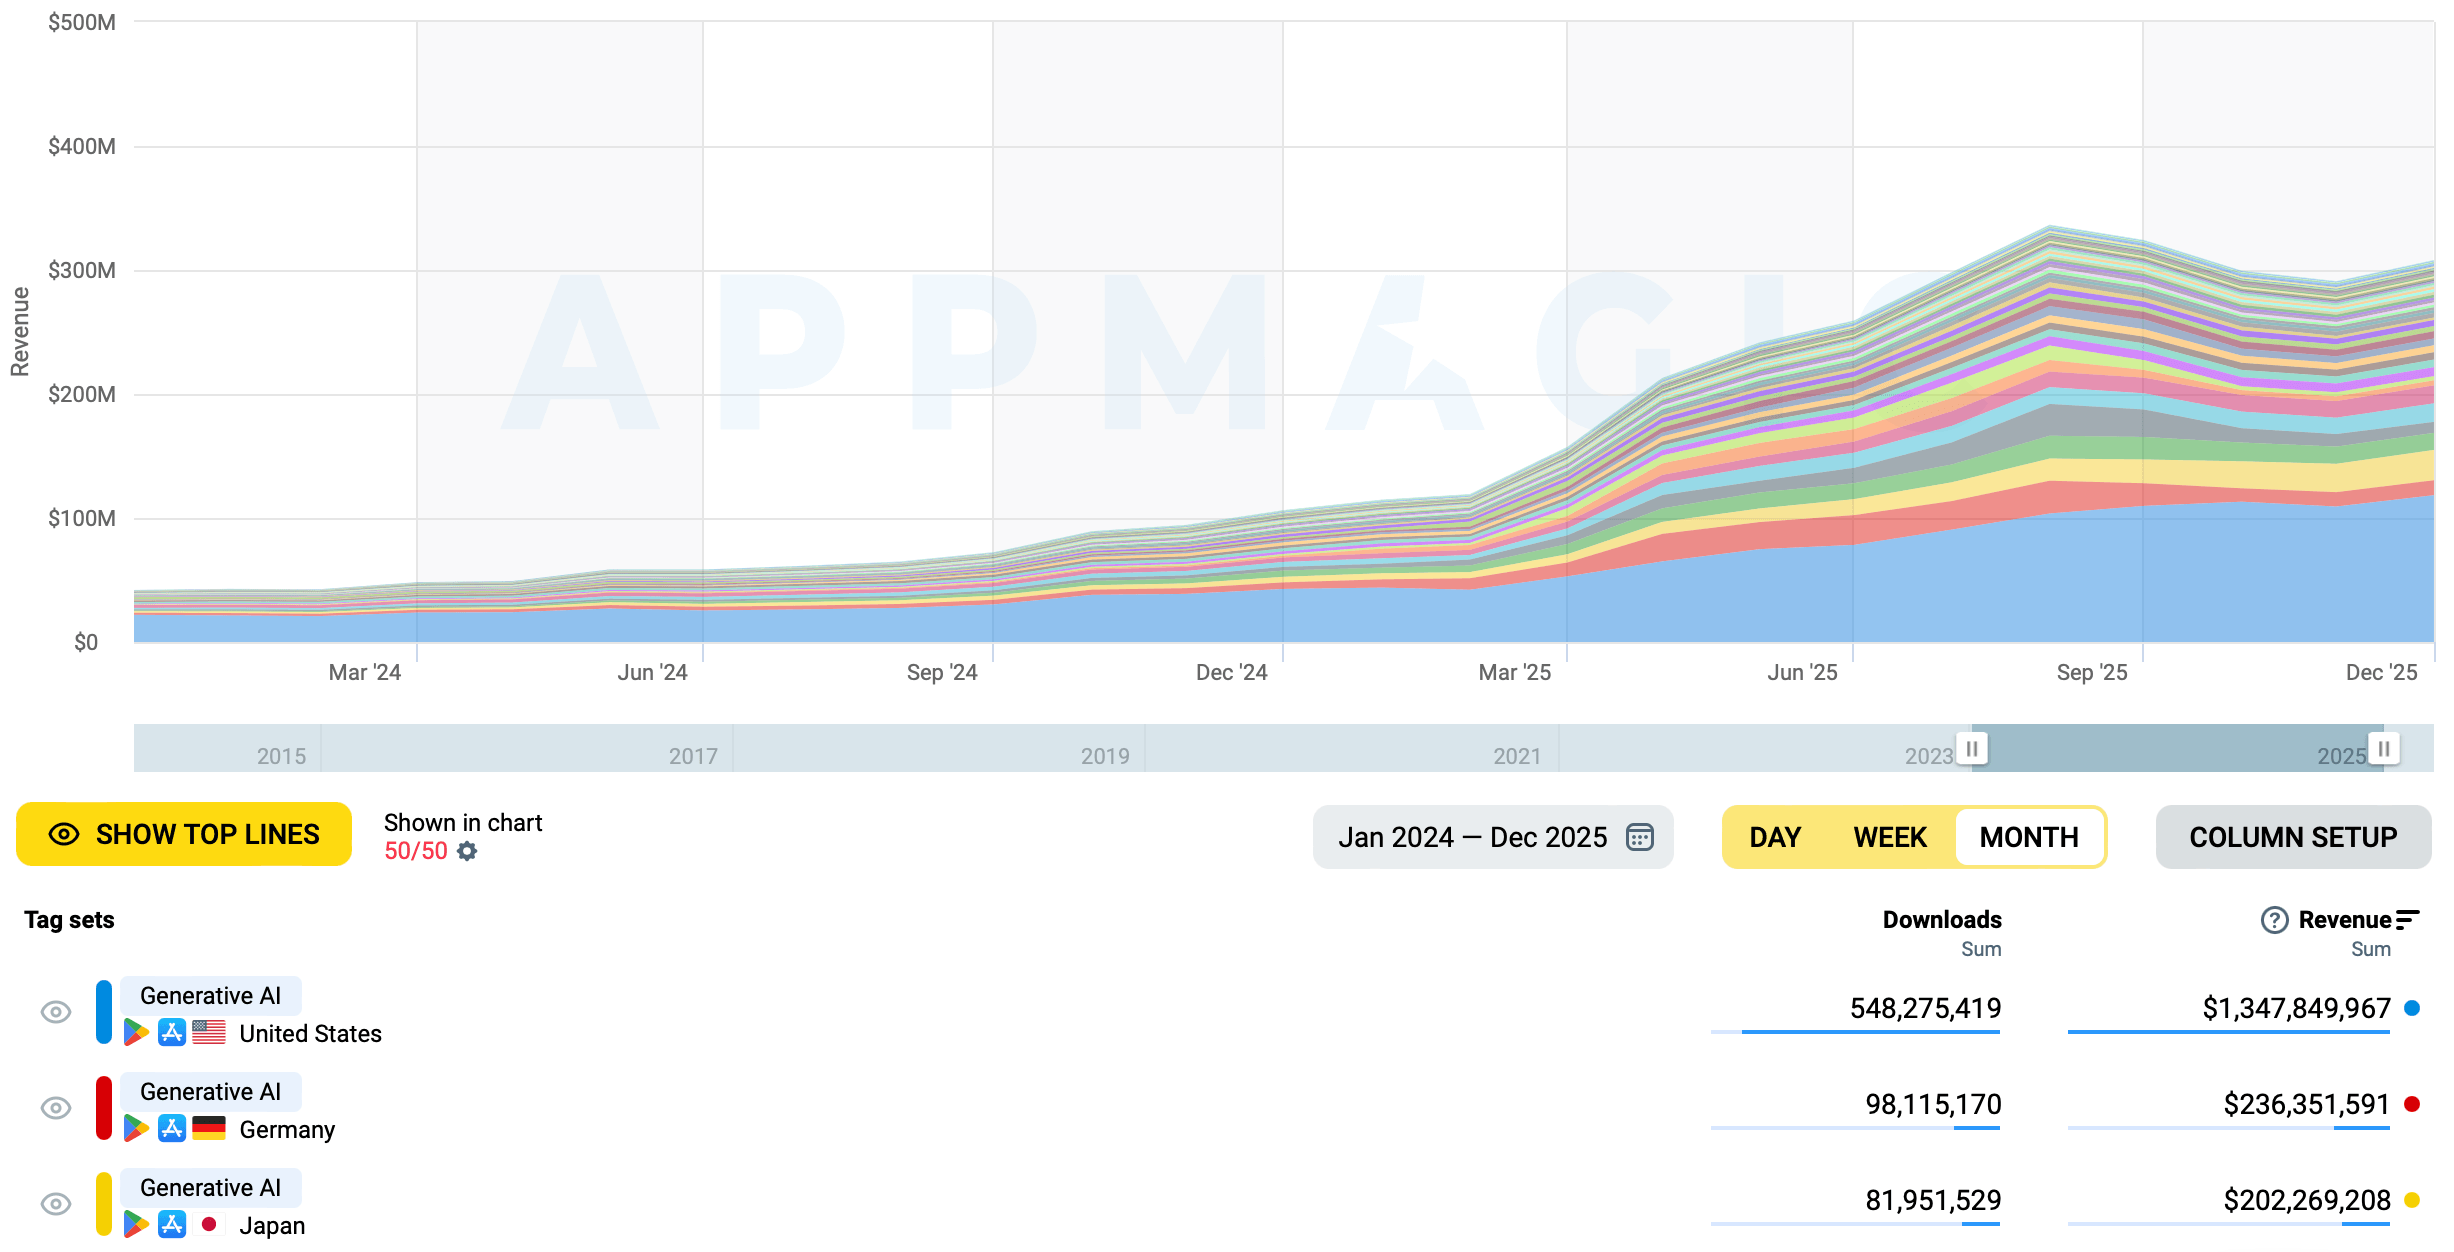
We have already confirmed that revenue in the Generative AI market continues to accelerate. Although category revenue in the United States grew by 189% YoY, accounting for over a third of the market, the US share of global revenue, in fact, declined. This is due to the rapid growth of earnings in other countries. For example, revenue in Japan increased by 452%, and Germany is up 410%.
Generative AI market’s revenue split by countries
Source: AppMagic
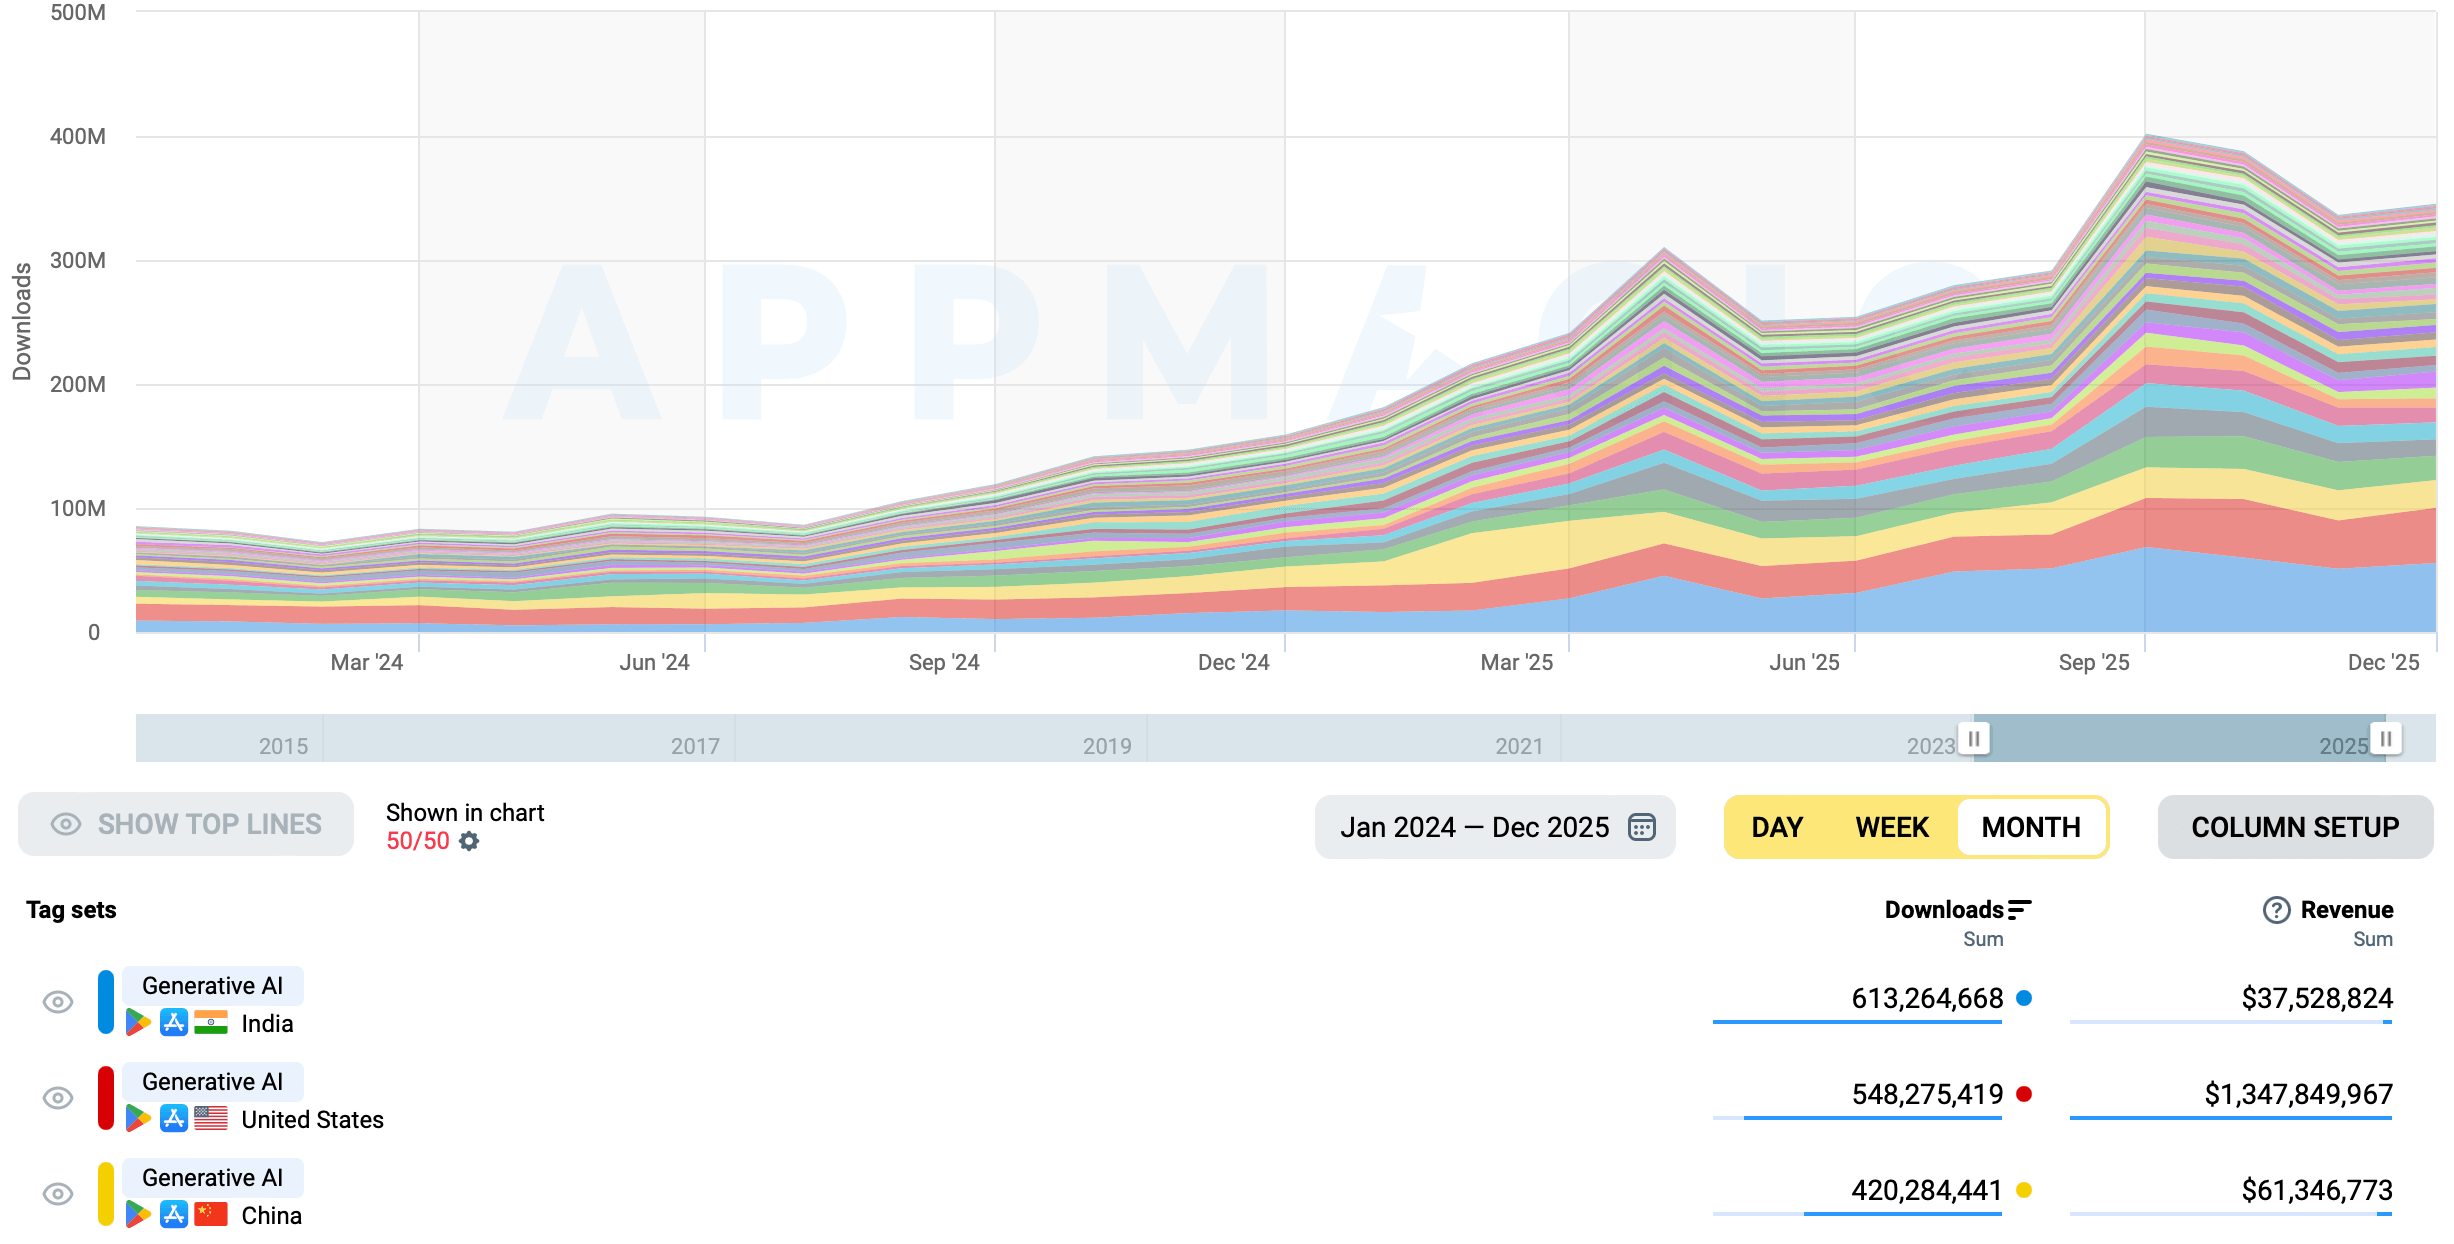
Downloads are also showing a steep upward trend, with the top three countries remaining unchanged from 2024. In 2025, India’s growth picked up the pace, with downloads increasing by 338% YoY and allowing the country to claim a bigger share of the global market. Meanwhile, despite strong downloads growth in the United States (+111% YoY) and China (+165% YoY), both countries saw their overall market share decline.
Generative AI market’s downloads split by countries
Source: AppMagic
Notably, in 2025, revenue grew faster than downloads. User behaviour shifted from initial curiosity to a more regular app use, signaling that Generative AI is entering a more mature and scalable phase.
The number of new releases returned to growth in 2025 after the 2024 drop, increasing 27% YoY, although the total number remains more than twice as low as in 2023.
The fastest growth in new releases is in the AI Art Generator category with a 53% YoY increase, followed by AI chatbots with 31% YoY growth. Notably, while new AI chatbot releases are starting to pick up again, they are still more than four times lower than in 2023. AI Music Generators, on the other hand, saw a major spike in new releases in 2024, growing 330% YoY, before slowing down to just 39% YoY growth.
Against the backdrop of explosive growth in downloads and revenue, as well as an increase in the total number of apps, retention in the segment declined. The drop can be observed across the entire user lifecycle. The largest decrease occurs in the first days of user activity (–6.2%), while mid- and long-term retention declined by 3.9%–4.5%.
Overall, the Generative AI market continues to grow rapidly as it gradually enters a more mature and scalable phase. The US market remains dominant, particularly in revenue, but its share is declining as other regions catch up in GenAI adoption and monetization, with India rapidly expanding its user base. Although new releases returned to growth in 2025, especially in AI Art Generators, the number of launches remains far below the 2023 peak.
Can new apps still make it in the Gen AI market?
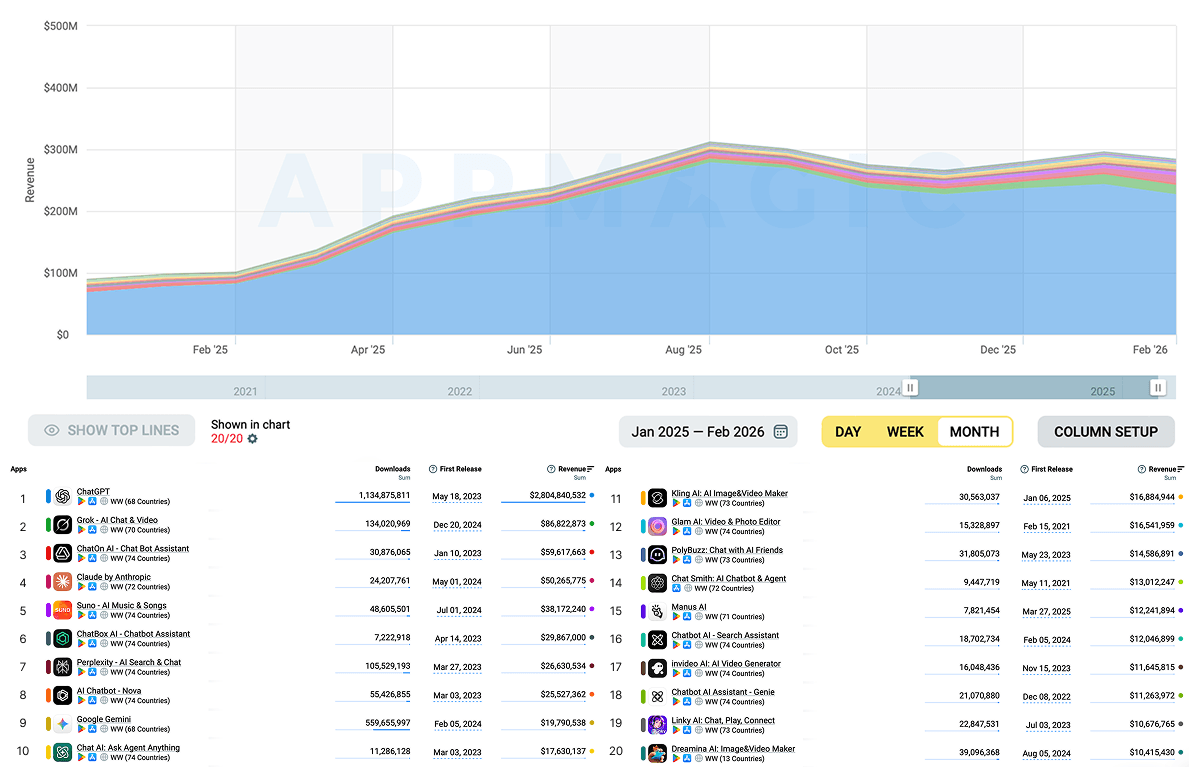
In 2025 and into Q1 2026, ChatGPT accounts for 77% of the Generative AI mobile apps market in terms of revenue, outperforming the market’s overall growth nearly twice.
Top 20 Generative AI apps by revenue
Source: AppMagic
However, the market is still evolving rapidly. In January 2025, Grok launched its mobile app and quickly became the second-largest app by revenue. In February 2026, shortly after the release of the Mobile Market Landscape 2026 report, Claude by Anthropic saw nearly twice the previous month-over-month growth following the launch of its new model, which brought the app close to Grok’s monthly revenue. Google’s Gemini has been growing strongly since November 2025, with its monthly revenue increasing by 120% over the past four months. In February 2026, its monthly earnings surpassed ChatOn AI, one of the leaders of 2025, by 45%.
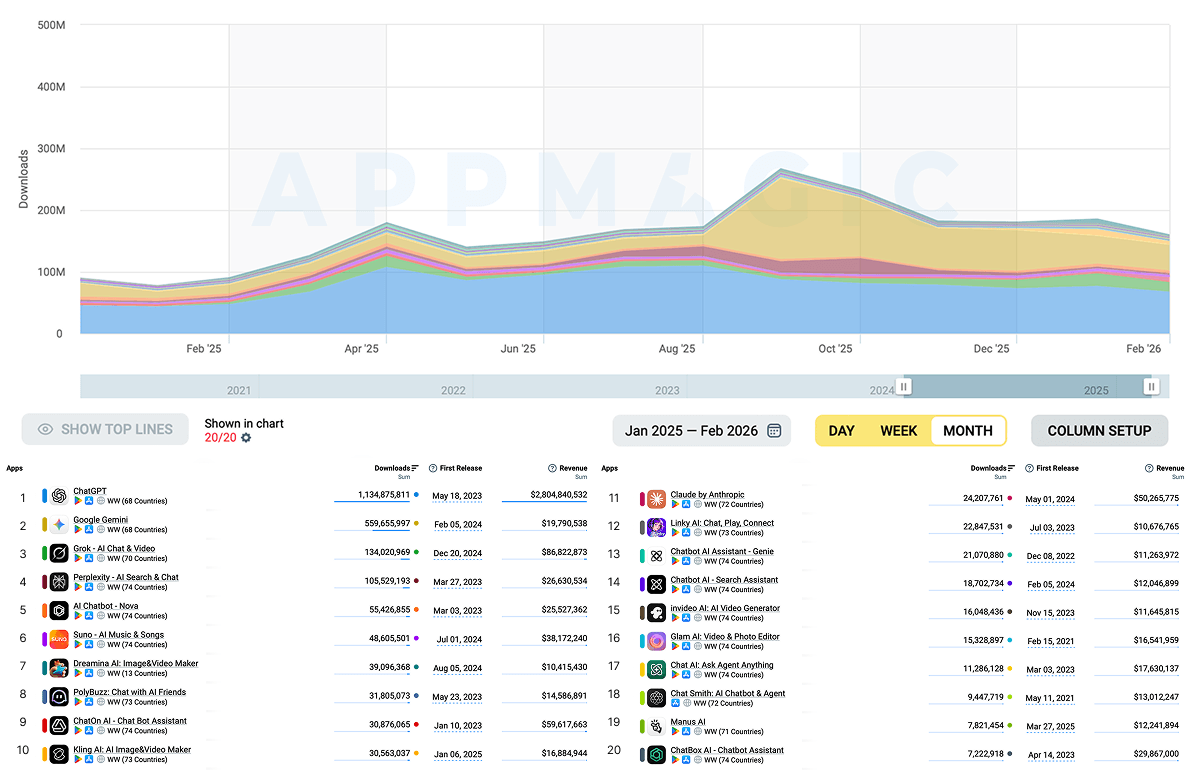
In terms of downloads, the market appears more saturated. ChatGPT accounts for 27% of total installs, growing slightly faster than the overall market.
Top 20 Generative AI apps by downloads
Source: AppMagic
Gemini follows with a 13% market share. The app experienced strong downloads growth driven by its viral image generation and editing model, Nano Banana. This momentum briefly shifted the competitive dynamic in the fall of 2025, when Gemini surpassed ChatGPT in monthly installs for the first time in the market’s history.
From the standpoint of the Top 10 apps by revenue, none of the 2025 releases have entered the rankings yet. However, two recent players appear in the Top 20: Kling AI: AI Image & Video Maker and the Manus AI chatbot. Kling AI experienced a spike in both revenue and downloads in January 2026, followed by a slowdown in growth, while Manus AI has been demonstrating a steady upward trend since the end of 2025.
Overall, the Generative AI market remains highly concentrated revenue-wise, with ChatGPT maintaining a clear lead while continuing to scale both its user base and monetization. However, the competitive landscape is evolving rapidly as new models from players such as Gemini, Claude, and Grok attract large audiences and demonstrate strong monetization potential. The appearance of newer apps in the Top 20 rankings further suggests that the market remains open to new entrants, even though their scale still lags behind the current leaders.
Where are the opportunities beyond AI chatbots?
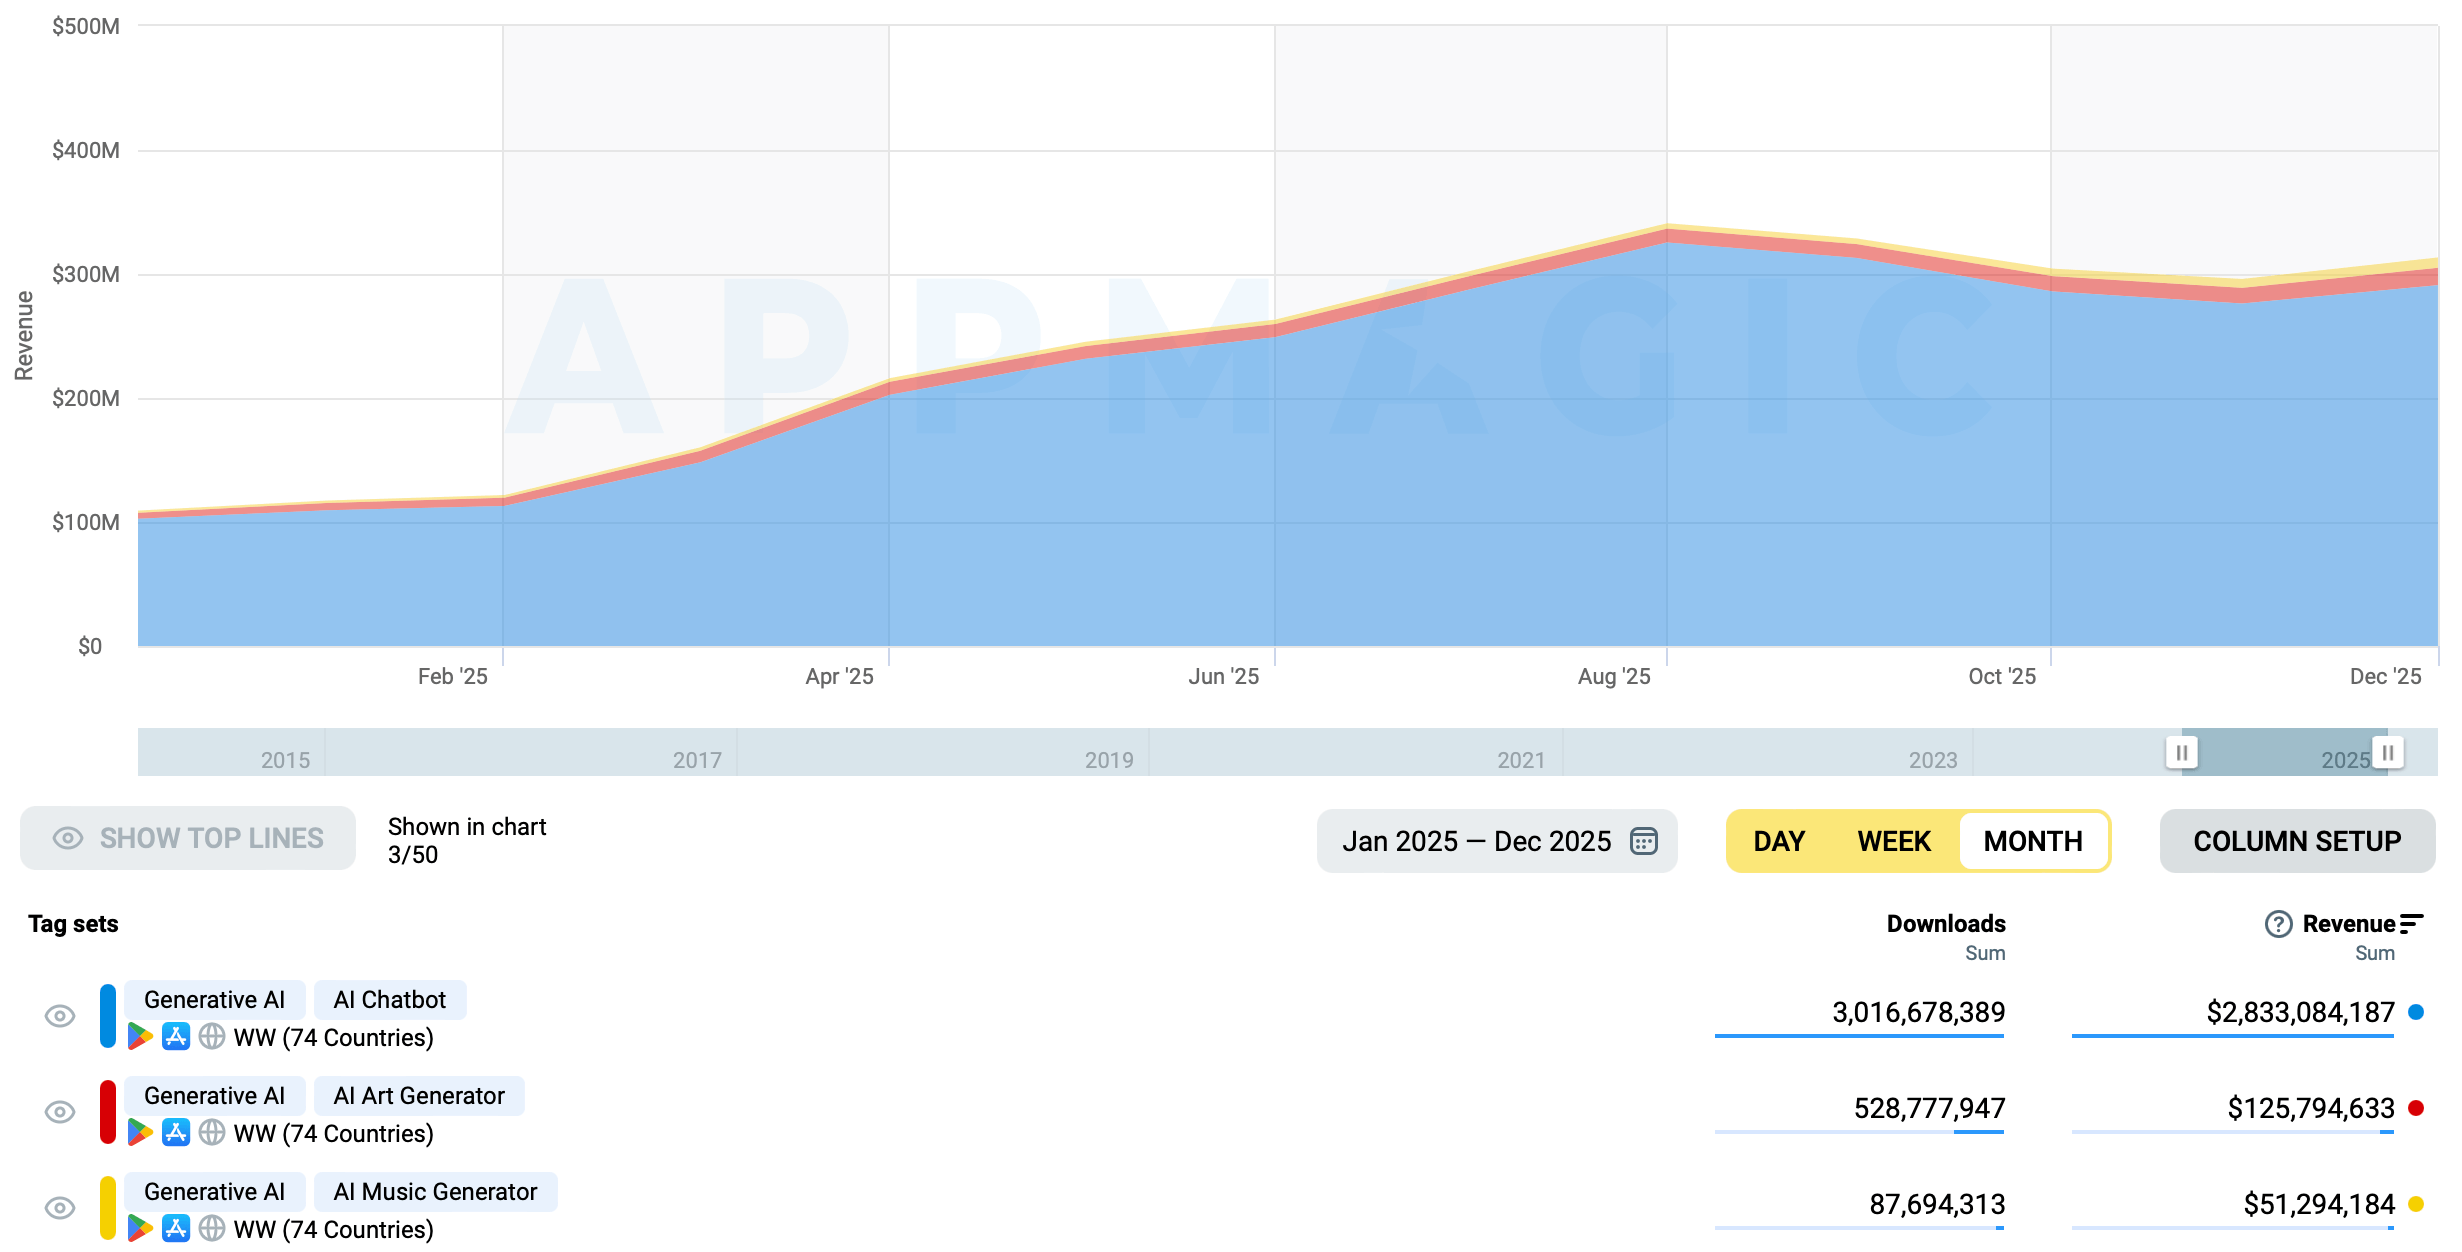
Looking at the Top 20 apps by both revenue and downloads, we primarily see AI chatbots. The category dominates the Generative AI market, accounting for 93% of revenue and 83% of downloads in 2025. Chatbot revenue grew 281% YoY, while downloads increased by 173% YoY, making the category the main growth driver of the Generative AI market.
Generative AI subcategories
Source: AppMagic
Chatbots also strengthened their monetization dominance, increasing their revenue share from 67% in 2024 to 76% in 2025 (+8.9 p.p.), even as their share of downloads declined from 74% to 64% (−10.1 p.p.). This suggests that, while chatbots remain the market’s primary monetization engine, other GenAI categories are starting to attract new users at a faster pace.
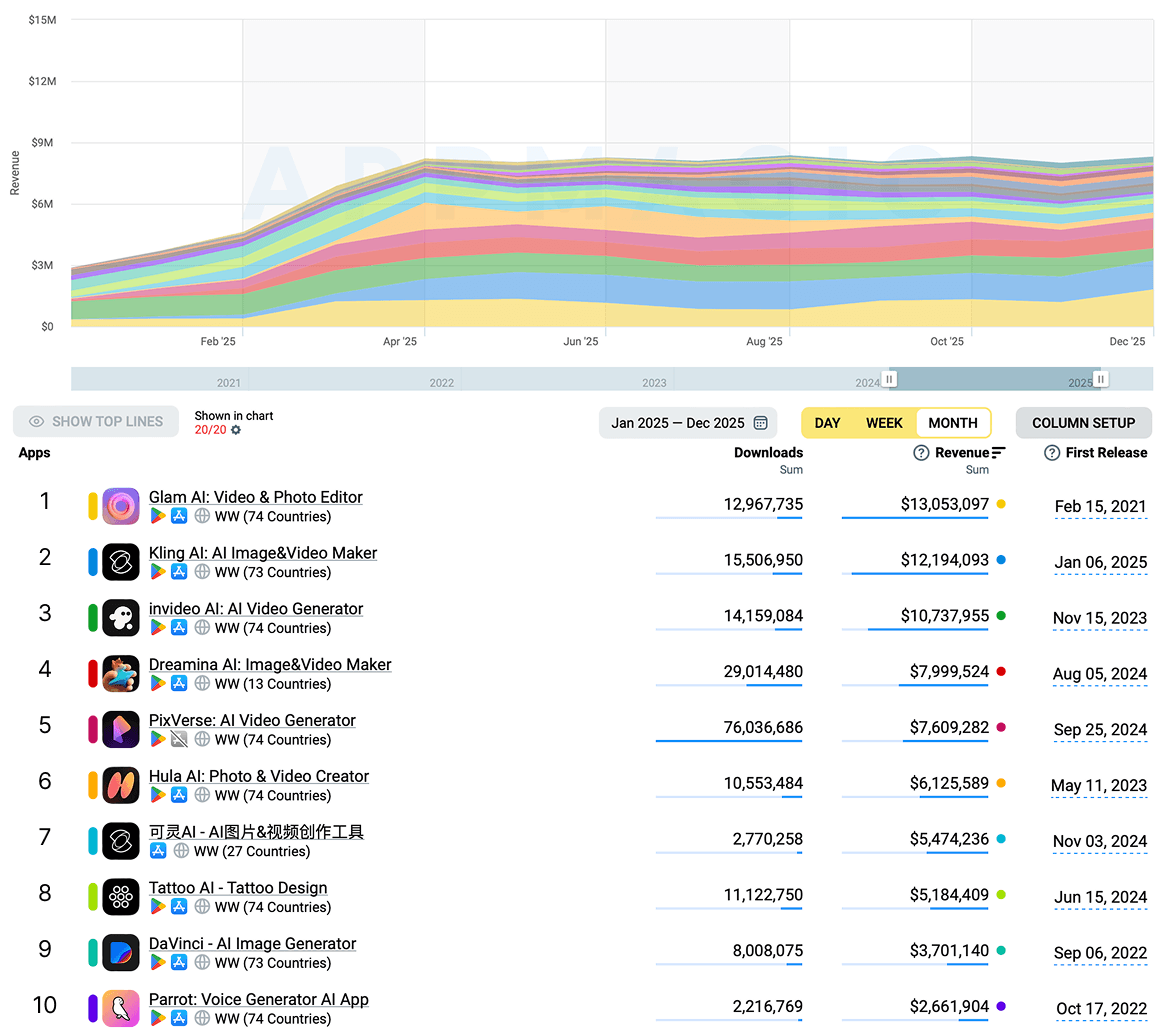
One of them is the AI Art Generator segment, which grew 100% YoY in revenue and 236% YoY in downloads. However, its revenue growth still lags behind the overall Generative AI market, resulting in a 3.6 p.p. YoY decline in revenue share, even as the segment’s downloads are now claiming 2.4 p.p. more. The competitive landscape here looks relatively fragmented, with no clear leader and a fairly even distribution across the main apps.
Top 10 AI Art Generator apps by revenue
Source: AppMagic
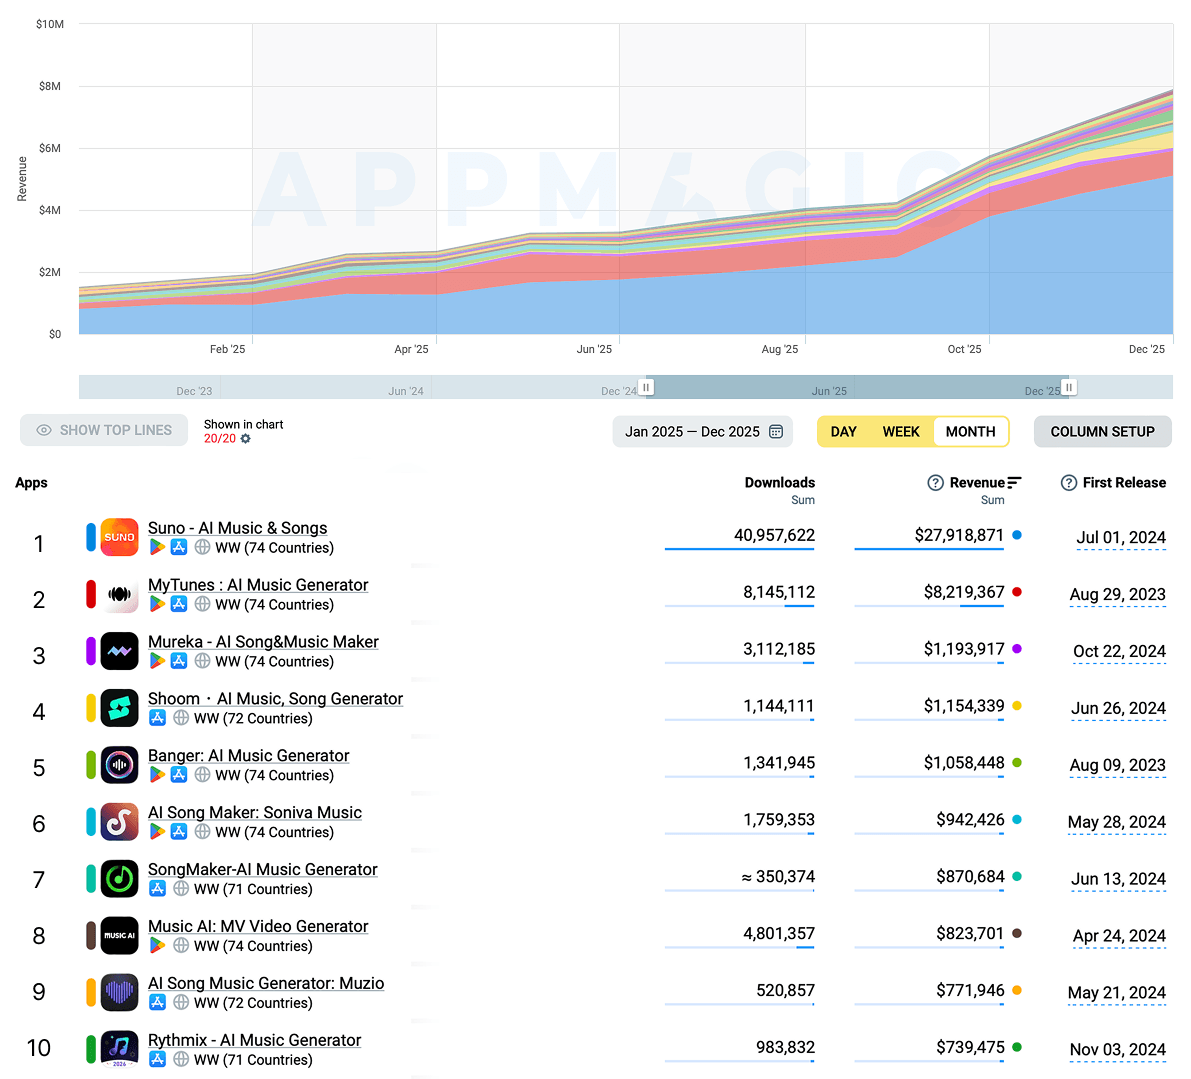
The AI Music Generator segment is growing even faster, with revenue up 410% YoY and downloads up 418% YoY. Unlike AI Art apps, however, this market is much more concentrated. Suno – AI Music & Songs clearly leads the segment, accounting for 55% of revenue and 47% of downloads in 2025, while the next competitor, MyTunes: AI Music Generator, holds 17% of revenue and 9% of downloads, with all other apps performing significantly below these levels. However, if we look at market change excluding the top five leaders, we still see the uptrend, with revenue up 203% YoY and downloads up 225% YoY.
Top 10 AI Music Generator apps by revenue
Source: AppMagic
Overall, chatbots remain the backbone of the Generative AI app market, dominating both revenue and downloads. However, adjacent segments are beginning to expand: AI Art apps are attracting new users, remaining fragmented and less monetized, while AI Music apps are emerging as a fast-growing niche with a clear market leader. Together, these trends suggest that, while chatbots will continue to anchor the market, the next wave of GenAI growth may increasingly come from specialized creative tools.
Where the Generative AI app market stands today
As it continues to expand rapidly, the Generative AI app market reached new highs in both revenue and downloads in 2025. At the same time, several signals suggest that the market is gradually entering a more scalable maturity phase, as user behaviour shifts from initial experimentation toward more regular use and monetization.
At the same time, the market is beginning to show clearer structural patterns. Chatbots remain the core of the ecosystem, accounting for the vast majority of both revenue and downloads, with ChatGPT firmly dominating monetization.
Despite this concentration, the market is not fully closed to new players. New apps are still managing to scale and land high in the rankings, although the gap between them and the leaders remains substantial. This suggests that, while entering the market is still feasible, catching up with its current top performers remains a significant challenge.
At the same time, adjacent segments are beginning to gain momentum. AI Art and AI Music generators are attracting users and demonstrating strong growth, suggesting that the next wave of Generative AI apps may increasingly come from specialized creative tools alongside dominant chatbots.
Download the full Mobile Market Landscape 2026 report here.