Seeing Machines Limited (LON:SEE) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. Seeing Machines Limited, together with its subsidiaries, provides driver and occupant monitoring system technologies in Australia, North America, the Asia Pacific, Europe, and internationally. The UK£222m market-cap company posted a loss in its most recent financial year of US$25m and a latest trailing-twelve-month loss of US$29m leading to an even wider gap between loss and breakeven. As path to profitability is the topic on Seeing Machines’ investors mind, we’ve decided to gauge market sentiment. In this article, we will touch on the expectations for the company’s growth and when analysts expect it to become profitable.
According to the 3 industry analysts covering Seeing Machines, the consensus is that breakeven is near. They expect the company to post a final loss in 2025, before turning a profit of US$18m in 2026. Therefore, the company is expected to breakeven roughly a year from now or less! At what rate will the company have to grow in order to realise the consensus estimates forecasting breakeven in under 12 months? Using a line of best fit, we calculated an average annual growth rate of 53%, which is rather optimistic! Should the business grow at a slower rate, it will become profitable at a later date than expected.
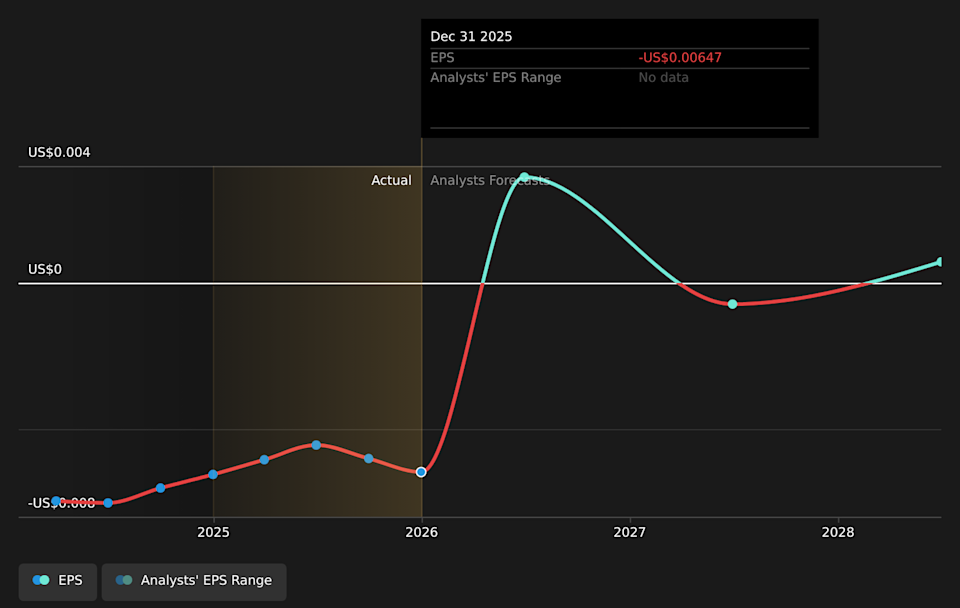 AIM:SEE Earnings Per Share Growth June 6th 2026
Given this is a high-level overview, we won’t go into details of Seeing Machines’ upcoming projects, however, take into account that typically a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
Check out our latest analysis for Seeing Machines
One thing we would like to bring into light with Seeing Machines is its debt-to-equity ratio of over 2x. Generally, the rule of thumb is debt shouldn’t exceed 40% of your equity, which in this case, the company has significantly overshot. A higher level of debt requires more stringent capital management which increases the risk in investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on Seeing Machines, so if you are interested in understanding the company at a deeper level, take a look at Seeing Machines’ company page on Simply Wall St. We’ve also put together a list of important factors you should look at:
Valuation: What is Seeing Machines worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Seeing Machines is currently mispriced by the market.
Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Seeing Machines’s board and the CEO’s background.
Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.