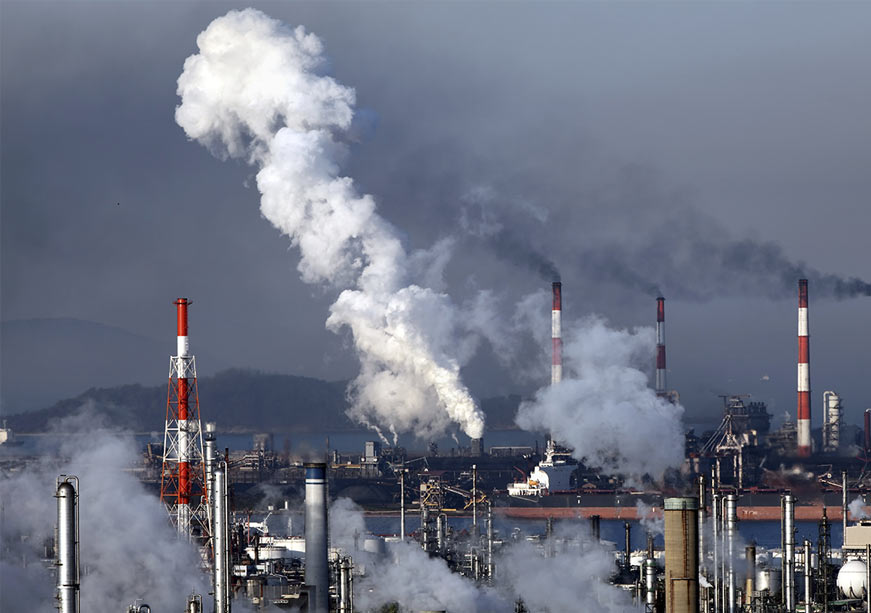
Image Source: Getty Images
Since the concept of an Emissions Trading System (ETS) emerged, the detrimental effect of carbon emissions on society has informed the purpose of carbon markets: to establish a system of limited ‘rights to emit’ that reduces overall emissions harmful to society. The carbon market, in its functioning, must seek to reduce the total cost to society by assigning a carbon price equivalent to the current value of the damages caused by an additional tonne of emissions. Intuitively, a carbon price that captures not only the economic costs borne directly by emitters but also the associated external costs is consistent with the underlying market premise. Yet, carbon prices in existing ETSs largely reflect only the costs of abatement. The exclusion of the Social Cost of Carbon (SCC) thus creates a price–value mismatch that, in conventional economic markets, would amount to market failure. Examining how this mismatch operates in carbon markets—which were arguably created to serve a social rather than purely economic objective—helps explain why ETSs often fail to deliver their intended outcomes.
The exclusion of the Social Cost of Carbon (SCC) thus creates a price–value mismatch that, in conventional economic markets, would amount to market failure.
What is the Social Cost of Carbon?
The SCC represents the present monetary value of all the costs that society will bear in the long run due to one additional tonne of carbon emissions. These costs often include long-term health effects, property damage resulting from climate events, effects on agricultural output, and more. Given the aim of a carbon market, the price placed on the ‘right to emit’ must reflect the total cost of an additional tonne of emissions borne by society. This total cost includes the economic cost of abating emissions and the social cost of unabated emissions. Only when the total cost is fully accounted for do the producers of carbon emissions adequately internalise the damages they impose on society as a whole. This, however, does not appear to hold in practice.
Social costs often go unaccounted for because they present themselves as ‘externalities’, usually negative in nature. These effects on society are outside the purview of the emitter, often abstract, long-term, and non-monetary. As private actors are primarily focused on profit maximisation, the external costs of their emissions on third parties are often deemed immaterial and left unaccounted for. This explains why private players tasked with addressing issues of public interest often lead to market failure. To understand how these market failures affect the primary mechanism for emission reduction, it is necessary to explore the dissonance between the profit-maximising private actor and the social-cost-minimising regulator.
The Case of a Private Player
In a compliance carbon market, obligated entities are required to remain within a certain emission limit and trade their remaining ‘rights to emit’ with players that may need to emit beyond their allocated limits. Naturally, the purpose of a private player is profit maximisation or cost minimisation within the constraints imposed upon it. Therefore, when a private player estimates the cost of abating emissions in terms of present value, it only takes into account the economic cost associated with employing different technologies to reduce one additional tonne of carbon emissions. In a market with only private players, this additional economic cost, called the marginal cost of abatement, is captured in the price of the ‘rights to emit’ traded in the market, whereas the cost of emissions borne by society is not.
As private actors are primarily focused on profit maximisation, the external costs of their emissions on third parties are often deemed immaterial and left unaccounted for.
These marginal abatement costs act as the determining factors in a private entity’s decision to buy or sell. If abatement costs are low, the willingness to pay is also low, since the private player can simply emit less than its allocated limit and sell surplus ‘rights to emit’. With a low willingness to pay across the market, prices eventually settle at lower levels, leading to lower incentives to abate, and the market ends up with more sellers than buyers. In such a market, prices do not accurately represent the total cost and therefore remain low, resulting in the market failing to incentivise emission reduction at the required levels.
The Case of a Social Regulator
In contrast, a social planner seeking to maximise social welfare would value the total future costs in today’s terms. For this social planner, the focus is on optimising social welfare and reducing total cost. Therefore, a social planner would value the current cost of emitting at a higher level than a private player would.
Here is where the fundamental difference lies. The marginal abatement cost is no longer the sole deciding factor in choosing to buy or sell. The total cost represents the social planner’s maximum willingness to pay. Since the total cost is higher than the marginal abatement cost, the social planner’s willingness to buy one additional ‘right to emit’ is higher than that of the private player. In such a market operated by social planners, the price would settle at a higher level than in a market with only private players. This market would see prices converge closer to the total cost borne by society as a whole. The higher price and economic cost differential in this market, compared with one operated by private players, would encourage greater emission reductions and higher sales of ‘rights to emit’.
The Real Life Consequences of an Absent SCC
When one examines the carbon market today, it is evident that the price of one tonne of carbon emissions tends to trade lower than the estimated social cost of carbon, currently valued at US$ 185 per tonne of CO₂ emitted. This shortfall shows a clear sign of the absence of social cost accounting in the price discovery mechanism. As a result, the market’s integrity in achieving its prime objective has been consistently undermined.
To offset the private outlook in a ‘society-first’ market, market regulators must be socially inclined and establish operating mechanisms that incorporate social costs artificially.
Devaluation does not manifest as a slight deviation from the optimal path of emission reduction. Quite often, markets that do not account for social costs operate at the lowest possible carbon prices. In the absence of a floor price, the value of a ‘right to emit’ very well might tend to zero. In a market with the lowest possible price, trading is stagnant and unengaging. This often occurs due to asymmetric information between the profit maximisers and social regulators, causing prices not only to plummet into crashes but to remain there. The CER price crash, the EU oversupply problem, and even the Perform, Achieve and Trade (PAT) scheme trading at floor price are routine phenomena in ETSs globally, showcasing the extremes of failing to account for SCC. And yet even with trading at floor prices, the price and value differential remains positive, and SCC remains unincorporated.
Then, the way to incorporate SCC into the market is to recognise that private market participants cannot be left to operate the market on a laissez-faire basis. Their profit-maximising interest cannot be aligned with the market’s goals, but they can be regulated via social cost-minimising mechanisms.
To offset the private outlook in a ‘society-first’ market, market regulators must be socially inclined and establish operating mechanisms that incorporate social costs artificially. Economists call this ‘internalising the externality’. This can be done by setting the floor price at a level equivalent to the SCC of the market’s jurisdiction. Therefore, even if markets operate at the floor price, the emission reduction induced by that price level sufficiently addresses the effects of emissions on society
Incorporating SCC into the carbon price in this manner allows for a price–value match whereby the future costs borne by society are reflected in their present-day value. If the SCC is built into the price of a tonne of carbon emissions, at a higher carbon price, private actors are more likely to pursue abatement rather than offset their emissions by purchasing ‘rights to emit’ from the market. Overall, this would result in greater abatement, enabling the carbon market to better serve its intended purpose.
Indeed, this is most relevant to countries that regularly bear the brunt of emissions that do not necessarily emit. Pricing carbon while accounting for SCC would mean that the Global North is being charged with the costs that others are paying for them, bringing in the idea of common but differentiated responsibilities.
Diya Shah is a Research Assistant with the Centre for Economy and Growth at the Observer Research Foundation.
The views expressed above belong to the author(s). ORF research and analyses now available on Telegram! Click here to access our curated content — blogs, longforms and interviews.