
United Airlines Holdings (NasdaqGS:UAL) is reportedly weighing a potential merger with American Airlines. CEO Scott Kirby has discussed possible deal scenarios with administration officials. As an alternative, United is said to be considering an acquisition of JetBlue to expand with fewer regulatory hurdles.
United Airlines operates a large global passenger and cargo network, and any move toward a merger with American Airlines or an acquisition of JetBlue would sit at the center of how the US airline industry is structured. Investors are already watching how carriers respond to shifting travel patterns, capacity decisions, and cost pressures, so possible large scale deals add another layer to that picture.
For you as a shareholder or prospective investor, potential combinations of this size could influence everything from market share and route networks to regulatory scrutiny and integration risks. It is worth tracking how formal these discussions become, what regulators signal, and whether United ultimately pursues a transformational deal or opts to remain independent.
Stay updated on the most important news stories for United Airlines Holdings by adding it to your watchlist or portfolio. Alternatively, explore our Community to discover new perspectives on United Airlines Holdings.
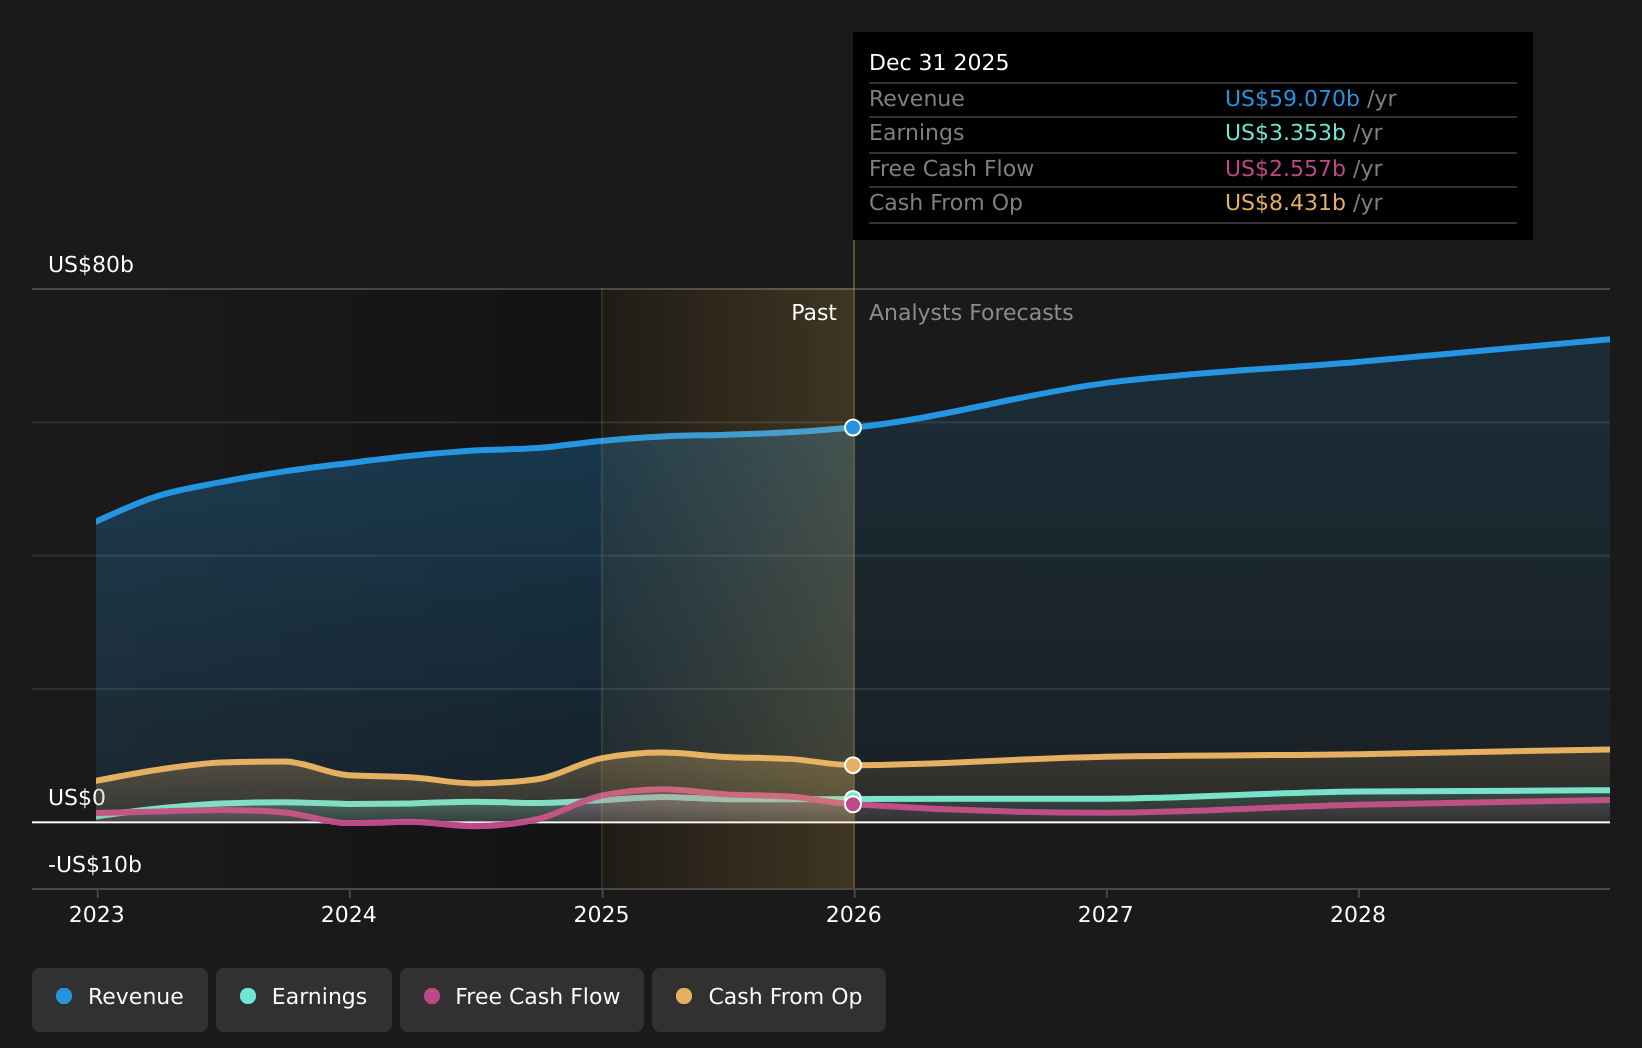 NasdaqGS:UAL Earnings & Revenue Growth as at Apr 2026
4 things going right for United Airlines Holdings that this headline doesn’t cover.
Quick Assessment ✅ Price vs Analyst Target: At US$97.20 against a consensus target of about US$130.17, the stock sits roughly 34% below analyst expectations. ✅ Simply Wall St Valuation: Currently assessed as undervalued, trading about 66.2% below the estimated fair value. ✅ Recent Momentum: The 30 day return of 7.7% shows positive short term price momentum.
To assess whether it could be the right time to buy, sell or hold United Airlines Holdings, visit Simply Wall St’s
company report for the latest analysis of United Airlines Holdings’s fair value.
Key Considerations 📊 A potential merger with American Airlines or an acquisition of JetBlue could reshape United’s competitive position and network reach, so position sizing may need to reflect that uncertainty. 📊 Watch any updates on regulatory feedback, deal structure, and financing plans, especially given the current P/E of 9.4 versus an industry average of about 9.9. ⚠️ High debt is already flagged as a risk, so adding a large transaction on top of that could increase financial and integration pressure if a deal proceeds. Dig Deeper
For a fuller picture, including more potential risks and rewards, check out the
complete United Airlines Holdings analysis. You can also visit the
community page for United Airlines Holdings to see how other investors believe this latest news may affect the company’s narrative.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com