
Earlier in June, Stealth Group Holdings Ltd. issued FY26 guidance calling for record sales of at least A$165 million and net profit after tax of A$5.8 million, underpinned by the integration of its November 2025 acquisition of Hardware & Building Traders (HBT).
The company also reiterated its ambition to reach A$500 million in annual sales by FY28 with an 8%–12% EBITDA margin, supported by a significantly enlarged 1,200‑store network and ongoing investment in digital, omni‑channel and logistics capabilities.
We’ll now examine how this FY26 guidance upgrade and reaffirmed FY28 A$500 million sales ambition may reshape Stealth’s investment narrative.
The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 14 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
Stealth Group Holdings Investment Narrative Recap
To own Stealth Group Holdings today, you need to believe in its plan to scale a capital‑light industrial and hardware distribution platform, now anchored by the HBT acquisition. The upgraded FY26 guidance to at least A$165 million in sales and A$5.8 million NPAT sharpens the main near term catalyst: proof that Stealth can turn a much larger 1,200‑store footprint into higher margins. The flip side is integration and execution risk, which now matters more than ever.
The most relevant recent announcement here is Stealth’s reaffirmed FY28 ambition of A$500 million in annual sales with an 8%–12% EBITDA margin, supported by the enlarged store network and ongoing investment in digital and logistics. Against the new FY26 targets, that long term goal now serves as a measuring stick for how quickly HBT volumes and rebate opportunities are being converted into reported revenue and earnings, and how much operational strain the group can absorb.
Yet behind the upbeat FY26 targets, investors should be aware that integration costs, slower HBT buy in and higher capex could still…
Read the full narrative on Stealth Group Holdings (it’s free!)
Stealth Group Holdings’ narrative projects A$297.8 million revenue and A$26.6 million earnings by 2029.
Uncover how Stealth Group Holdings’ forecasts yield a A$1.60 fair value, a 36% upside to its current price.
Exploring Other Perspectives 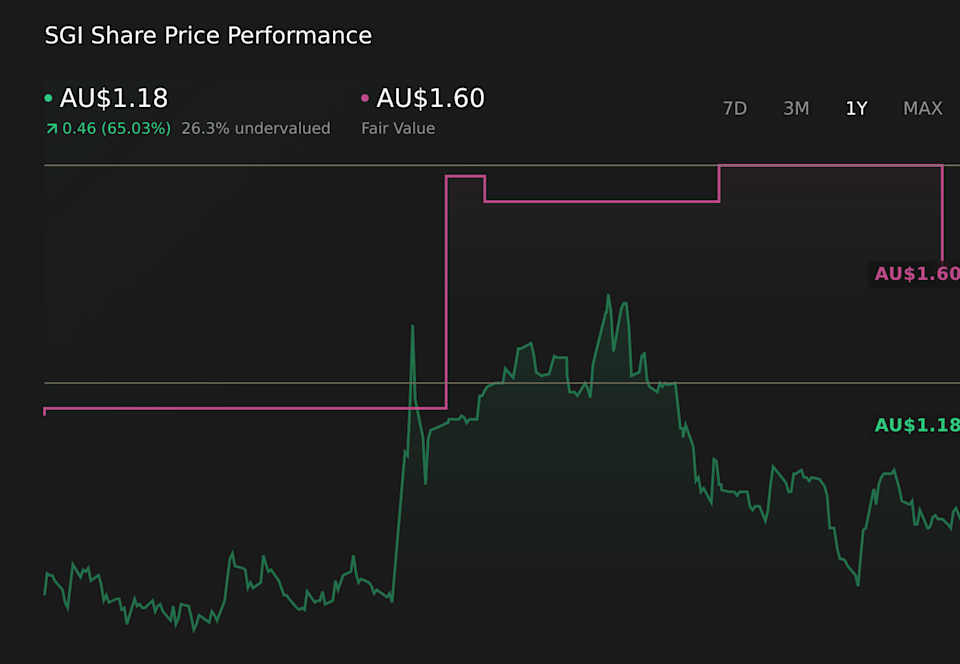 ASX:SGI 1-Year Stock Price Chart
Some analysts were already very optimistic, assuming revenue could reach about A$382 million and earnings A$42 million by 2029, so compared with those bullish expectations the new FY26 guidance may either reinforce that optimistic view or prompt you to question whether the heavy reliance on rerouting HBT volumes and expanding H Hardware can really deliver, which is exactly why it is worth weighing several different viewpoints before deciding what this latest update means for you.
Explore 3 other fair value estimates on Stealth Group Holdings – why the stock might be worth less than half the current price!
Decide For Yourself
Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.
Seeking Other Investments?
The market won’t wait. These fast-moving stocks are hot now. Grab the list before they run:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include SGI.AX.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com