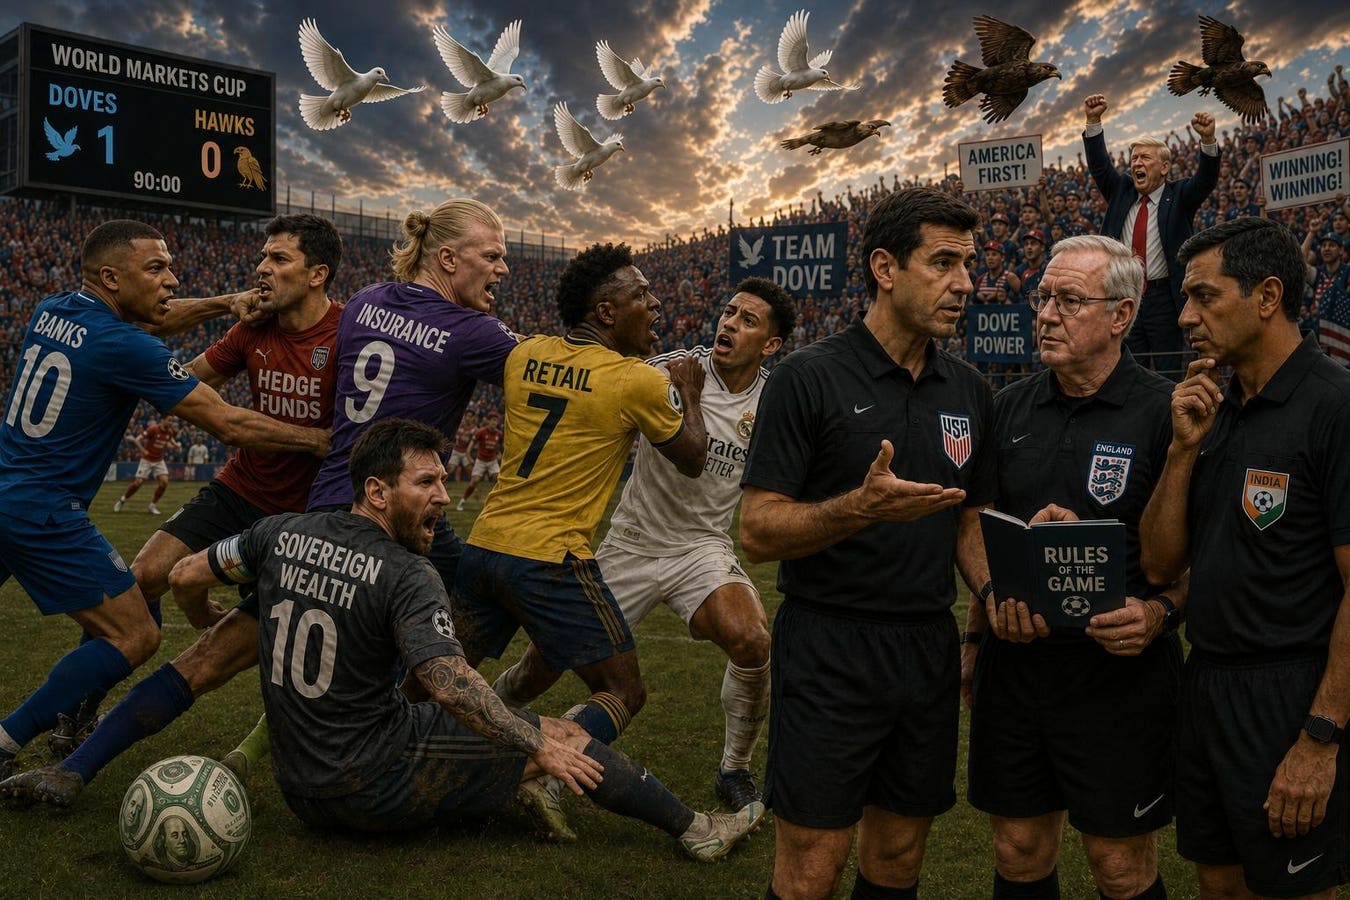
Huddling referees on the sideline
Author
The Federal Reserve (Fed) has underwhelmed the public in its efforts to control the inflation side of its dual mandate for over five years (see red bars in the chart below). After Kevin Warsh’s second meeting as Fed Chair concluded in July, the U.S. Dollar Index declined while the yield curve steepened. Furthermore, the 30-year Treasury yield reached a 30-year high.
Fed policy rate vs. policy gap
Author, FRED
Such dramatic market reactions reflect investors’ growing belief that the Fed under new Chair Warsh may not be nearly as hawkish as he appeared during Act One of his tenure, at the FOMC meeting in June. They also portend a gloomy future for long-term U.S. Treasuries at a time when the US public debt to GDP ratio remains near the all-time high reached during the pandemic.
US national debt
usdebtclock.org
A popular defense of Warsh’s apparent indifference toward an above-target inflation environment is that we need to be more patient and await the findings of his five monetary policy task forces. Indeed, Warsh has acknowledged that “the impatience that households and businesses feel have been going on for 63 months,” as if to remind the public that he’s only been in office for two months. But no matter how long a societal problem has existed, leaders should address it with urgency. Furthermore, based on Warsh’s recent public comments, the task forces’ eventual findings could potentially provide support for an even more dovish agenda.
Fed Monetary Policy Task Force Summary
Author
Communications:
Warsh has floated the idea of holding six instead of eight Fed meetings per year, declined to participate in the Statement of Economic Projections, and opposed unnecessary forward guidance as well as frequent public speeches by Fed officials. All three members of the Communications task force appears to favor communicating with less precision and greater discipline. Such a retreat from transparency may help markets focus less on the Fed, but it could also leave the Fed with greater discretion while giving markets with less insight into the Fed’s reaction function.
Balance Sheet:
Warsh is unequivocal about the benefits of a smaller Fed balance sheet. For example, shifting the Fed’s portfolio toward short-term Treasury bills and away from long-term bonds or mortgage-back securities could reduce market price distortion and limit the government’s role in allocating capital across sectors. However, operating a smaller balance sheet may require changes to bank liquidity regulations, since banks have to meet minimum liquidity requirements. A smaller balance sheet could also leave more room for a lower policy rate when the Fed buys fewer securities from the market. Both effects could raise financial stability concerns.
Data Sources:
Warsh has voiced a preference for median inflation measures or real-time indices like Truflation, which registered just 1.75% on July 1, 2026 compared with a June CPI inflation rate of 3.5%. President Trump most likely referenced this rather low inflation reading back in his State of the Union Address in February when he said fourth quarter inflation in 2025 was only 1.7%. Though less volatile, median measures are relatively slow to respond to inflation shocks. Real-time indices, meanwhile, may suffer from inadequate representation across CPI categories. Furthermore, real-time measures may be difficult to reproduce and lack long historical datasets, making them more vulnerable to methodological changes or selective interpretation.
Productivity & Jobs:
This task force is probably the least likely to help the Fed justify a dovish turn in the short-run. Due to its demand for computing power and related infrastructure, Artificial Intelligence (AI) may initially be inflationary. Overtime, however, it could become deflationary by expanding the economy’s capacity to produce goods and services. AI may also displace jobs that involve repetitive tasks, but could eventually create new job families that allow for higher productivity. The challenge is that the short and long-run effects may point to opposite policy directions.
Inflation Framework:
Despite Warsh saying that he will not revisit the 2 percent inflation target until the Fed has regained its credibility in fighting inflation, this task force could be a wild card.
Greg Mankiw is known for being a moderate economist and as the author of one of the most widely-used textbooks.William White is known for emphasizing the role of financial asset prices in gauging inflation, which may be conducive to a discretionary approach.Thomas Sargent, a Nobel Laureate known for Rational Expectations theory, is against unconstrained discretion but does not explicitly advocate for a mechanical approach.
A mechanical approach like those of Bennett McCallum (Nominal GDP targeting based on monetary base and money velocity) or John Taylor (policy rate formula based on inflation and GDP output gap) is unlikely. However, Stephen Miran-Trump’s appointee to the Fed Board of Governors to fill a 9-month term that ended in May 2026-recently coauthored an excellent paper advocating for monetary aggregates targeting. Indeed, the Fed’s statutory mandate includes the objective of maintaining “long run growth of the monetary and credit aggregates commensurate with the economy’s long run potential to increase production.” However, such a fundamental shift in the Fed’s reaction function could provide the Fed with more discretion to overlook supply-induced inflation, especially as it enters a communication-light regime.
Conclusion
Whatever the task force findings may be, they are not even due until the end of the year, shortly after the November midterm elections. In the meantime, Warsh’s analogy of letting the market “play the ball and not the referee” while the referees consult the rules on the sideline is akin to the referee letting the ball game go on without blowing the whistle. It may backfire as the game evolves into a brawl and long-term rates rise more than they would have under a more disciplined and timely Fed.