
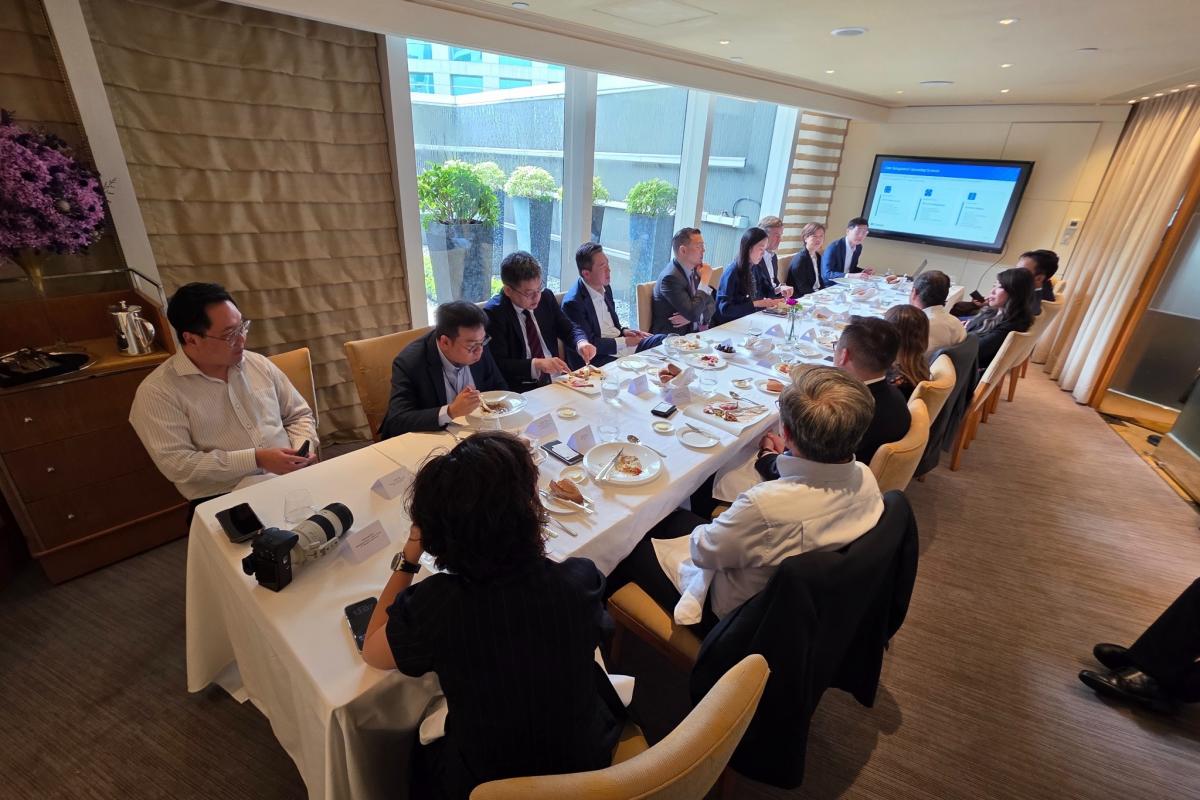
Access to alternative investments has widened considerably, but making them a routine part of private wealth portfolios requires more than a larger product shelf. During a visit to Hong Kong in October 2026, Lawrence Calcano, Chairman and Chief Executive Officer of iCapital, joined private banking CEOs and senior investment gatekeepers for an exclusive roundtable lunch hosted by Hubbis in partnership with iCapital at the Conrad Hong Kong. He outlined how the firm is addressing that challenge, exploring the infrastructure, information and product structures needed to help advisers incorporate alternatives across their client base. His account of iCapital’s development connected that operational work with a broader ambition: to make specialised investments easier to understand, transact and manage, while strengthening the adviser’s relationship with the client.
Key Takeaways
Access is giving way to implementation. Calcano described a market in which obtaining alternative investments is no longer the principal obstacle. Advisers increasingly need tools to assess their role in portfolios, explain them to clients and manage the investment through its lifecycle.
Infrastructure determines whether adoption can scale. Repeated data entry and disconnected systems make alternatives difficult to administer. iCapital’s approach centres on connecting the existing participants, with distributed ledger technology supporting more consistent information and fewer subscription errors.
Artificial intelligence can strengthen the advisory relationship. Calcano rejected the idea that advisers must choose between technology and personal service. He saw artificial intelligence (AI) as a way to improve parts of the client experience, while preserving the trust and judgement that advisers provide.
Portfolio structures can broaden participation. Single-ticket multi-manager vehicles, built primarily from evergreen funds, are intended to give advisers a more familiar way to implement alternatives. Growth, income and multi-asset approaches can be tailored to the needs of distribution partners.
Tokenisation depends on the surrounding infrastructure. Calcano distinguished the current use of distributed ledgers from the wider adoption of tokenised funds. Digital wallet availability, payment arrangements and information security remain important conditions for that next stage.
Execution and culture underpin the business. iCapital’s ambition extends across alternatives, structured investments and annuities, including professionally managed retirement portfolios. Calcano linked its ability to deliver that breadth to client focus, collaboration and an entrepreneurial culture that survives as the firm grows.
View the photos from this discussion HERE.
From Private Equity Access to a Broader Investment Platform
Calcano was joined by Brooks Entwistle, Head of International, Tuan Lam, Head of Asia Pacific, and Edwin Chan, Head of International, iDirect and Head of Strategic Development, Asia Pacific. The discussion drew on the firm’s experience across markets, but its central concern was practical: what wealth managers need to bring a wider investment universe into their clients’ portfolios.
iCapital began by creating access to private equity for advisers’ wealthiest clients. Feeder vehicles allowed those clients to invest in funds that had traditionally been difficult to reach. As demand developed, the firm added private credit, real estate, infrastructure and hedge funds, alongside structures suited to different regulatory environments.
That expansion also required a broader view of the client base. Calcano wanted advisers to be able to serve more than the small group of clients who had participated in the first wave of alternatives. Product availability, investment structures and the supporting technology had to accommodate additional tiers of wealth.
The platform subsequently extended into structured notes, annuities and data management. These businesses shared operational requirements with alternatives: investors needed education, transactions could involve complicated subscription processes, and the provider had continuing responsibilities after the initial investment. Calcano’s focus was on supporting the whole journey, from learning about an asset class to buying and managing a specific holding.
Moving Beyond the Product Shelf
Calcano recalled approaching former colleagues who had established private equity or hedge fund businesses when iCapital was starting out. Some questioned why they needed private wealth capital when institutional investors already provided the funding they wanted. That initial scepticism contrasted with the attention private wealth now receives from investment managers.
For Calcano, the change in demand has shifted the problem advisers need to solve. Access across strategies is much more widely available. What matters increasingly is whether an adviser can use that access effectively within a client’s portfolio.
He described iCapital’s operating system through three connected elements: products, infrastructure and information. A broad range of investments need technology that supports their administration, together with research, education and portfolio tools that help advisers decide how to use them. Extending the product menu without addressing those other requirements leaves much of the implementation burden with the wealth manager.
Education remains part of that process. Calcano stressed that advisers and clients should understand an investment before committing to it, rather than encountering its characteristics partway through ownership. The firm’s adviser surveys also pointed to demand for better reporting and tools to support client advice. As participation expands beyond experienced alternatives specialists, those capabilities become more important.
Connecting the Existing Investment Infrastructure
“We’re not actually disruptive; we’re enabling,” Calcano said, recalling how he responded to early descriptions of iCapital. His ambition was to help the existing investment infrastructure work together more efficiently, with asset managers, administrators and wealth platforms connected through the investment lifecycle.
The difficulty is familiar to private banks. Different parties use separate systems, and the same subscription information may be entered repeatedly as it passes between them. Each additional hand-off creates work and the possibility of an error, making a growing alternatives business harder to support.
Calcano used iCapital’s distributed ledger technology (DLT) to illustrate how that can change. He reported that subscriptions into a private markets investment available through a global wealth management platform had recently passed US$1 billion through the firm’s DLT infrastructure. An administrator connected to the ledger could receive information in real time and populate its systems directly, rather than re-entering data from a subscription file.
The aim was to reduce submissions classified as not in good order, a persistent source of delays and additional work. The example gave substance to his argument that greater adoption depends partly on improving the connections between firms already involved in the process.
His longer-term ambition was equally broad. Calcano compared the infrastructure he wanted to build for alternatives, structured notes and annuities with the role of the New York Stock Exchange in equities. Delivering that ambition required participation from major firms across investment management, issuance, insurance and distribution.
Using AI to Support the Adviser
Calcano approached AI through the relationship between advisers and clients. He recalled similar predictions a decade earlier that robo-advisers would replace financial advisers, and rejected the suggestion that technology and personal advice were competing choices.
Some elements of service can be delivered more effectively through technology; others depend on a personal relationship. Advisers who understand that distinction can improve the client experience without weakening the trust on which their business rests. In Calcano’s view, the opportunity is to combine those strengths deliberately.
That position also reflects iCapital’s business-to-business model. The firm develops tools for wealth managers and their advisers to serve clients, rather than seeking to take over the underlying relationship. Its technology priorities follow from that role.
Calcano highlighted iCapital’s involvement in Anthropic’s Claude for Financial Advisors initiative and described approximately 30 AI products and projects within the firm, around 10 of which were already in production. He also said roughly 75% of its new code was being written using Claude, with AI contributing to quality assurance and testing. These examples reflected adoption within iCapital itself, alongside the development of services for advisers.
Why Tokenisation Is a Longer Putt
Calcano was more measured about the near-term role of tokenisation. “Tokenisation is a longer putt,” he said, distinguishing the use of distributed ledgers to improve subscriptions from the wider changes needed to transact in tokenised funds.
The central constraint was the availability of digital wallets among major buyers of alternatives. Tokenising a fund does not necessarily simplify the investment process if subscriptions are managed through a ledger but payments still have to move off-chain. In that situation, the arrangement can add complexity to an already functioning process.
He expected tokenisation to develop, but saw broader wallet adoption and the ability to keep payments on-chain as important conditions. Private banks’ information security assessments would also influence the pace. How wallets are managed, secured and distributed is part of the infrastructure question, rather than a detail to address after the product has been created.
The distinction helped explain iCapital’s current emphasis: improving connectivity where it can already remove operational friction, while recognising that other technologies depend on changes across the wider market.
Making Alternatives Easier to Implement in Portfolios
A broader adviser population brings a different implementation challenge. Calcano observed that alternatives activity still tends to be concentrated among a smaller group of advisers. He had previously described an 80/20 pattern, although he no longer considered that ratio as stark. Bringing more advisers into the business requires a way for them to incorporate investments they may have less experience using.
Many already build client portfolios through models. iCapital has therefore developed single-ticket multi-manager vehicles that offer a more familiar allocation format. Built primarily from evergreen funds, these can be designed with a bank’s platform to provide an alternatives allocation that looks and feels closer to the models its advisers already use.
At the time of the lunch, Calcano described around five such vehicles already in production, with approximately 10 more expected by year end. He outlined multi-asset, growth and income versions, with variations shaped by distribution partners’ requirements. The firm also builds vehicles for multi-strategy investment managers seeking to bring their products together. He saw these structures as a way for major banks to engage a wider part of their adviser base in alternatives.
Information about the rest of the client’s wealth is another part of portfolio construction. Calcano noted that advisers regularly face the problem of assets held elsewhere, limiting their ability to give a complete account of the client’s financial position. Aggregated reporting can support both a more informed investment discussion and the adviser’s role as the client’s principal point of advice.
A Global Business with Similar Client Needs
The geographical breadth of iCapital’s business reinforced Calcano’s view that demand for alternatives is a global development. Entwistle described the international operation across Asia Pacific, Europe, the Middle East, Canada, and Latin America. Lam highlighted the expansion of the Asia Pacific team, particularly in functions supporting existing clients and developing new relationships.
Calcano reported approximately US$1.2 trillion serviced across the platform, including nearly US$350 billion in alternative investments. Around US$65 billion of those alternative assets came from investors outside the United States. He also cited more than US$250 billion in structured investments, over US$60 billion in annuities and close to US$600 billion in client assets covered by reporting services.
Those figures illustrated the scope of the platform rather than a single pool of assets under management. The business extended across investment access, transaction infrastructure and information services, with nearly 4,000 wealth management firms and more than 150,000 financial advisers having used its technologies over the preceding year, according to Calcano.
The conversations themselves were becoming more similar across locations. He described comparable discussions in Brazil, Singapore and Hong Kong, with advisers seeking ways to bring alternatives into client portfolios. Local structures and regulation still mattered, but the questions about education, implementation and infrastructure increasingly travelled across borders.
Broadening the Structures and the Investor Base
Calcano also described investment exposures appearing in different forms as product boundaries evolve. Hedge funds could be held within life insurance contracts, while structured investment exposures could be delivered through exchange-traded funds (ETFs). These arrangements gave clients additional choices about how to own an exposure, with the structure influencing its use within a portfolio.
Retirement investing was another area of development. Calcano discussed a recent collaboration to provide private markets capabilities for professionally managed retirement solutions. iCapital’s relationship with Great Gray Trust Company, a provider of collective investment trusts (CITs), supports that work through manager evaluation, due diligence, portfolio construction and investment lifecycle services.
The proposed approach supplies alternative investment building blocks, including multi-asset, growth and income strategies, for use by professional fiduciary managers. Those managers decide the allocation and the mix of underlying exposures. iCapital supports the investment selection and ongoing administration, including reporting and changes in holdings.
Calcano drew a comparison with defined benefit schemes, where professional managers make investment decisions on behalf of retirees. His emphasis was on equipping those responsible for retirement portfolios to incorporate alternatives in the proportions they considered appropriate, supported by the necessary investment and operational capabilities.
Preserving Culture as the Business Grows
Calcano linked iCapital’s ability to execute its strategy to the culture behind the business. The firm’s phrase “humble and hungry” described expectations that he wanted to preserve as the organisation expanded.
Humility began with the client. “Your success will only ever follow the success of your customers,” he said. He warned against the tendency for growing companies to regard their own work as more important than that of the organisations they serve.
It also meant working across the whole firm. Teams building technology, designing investment structures or developing retirement solutions need expertise beyond their immediate office or function. Calcano described collaboration across locations as essential to delivering services in a complicated global market.
Being hungry meant retaining entrepreneurial habits alongside the processes needed to manage a larger organisation. He wanted colleagues to keep questioning how work was done, remove unnecessary steps and look for better ways to deliver an outcome. Execution gave those ideas their value. “Good ideas are only as good as their implementation,” he said, pointing to the importance of understanding banks’ operational, compliance and information security requirements when building something they can actually use.
That practical emphasis ran through his account of the business. Calcano saw a gap between the alternatives allocations private banks consider appropriate and those clients actually hold. Closing it requires suitable products, greater understanding and infrastructure that makes ownership manageable. He recalled that mutual funds and ETFs also took time to become familiar and straightforward to use. Alternatives retain their own complexities, but his objective was to make them easier for advisers to explain and incorporate into their practice, with the investment decision supported throughout its lifecycle.
Around the Table Perspectives from Private Banking Leaders
The opening exchange brought a client-facing perspective to the challenges of expanding alternatives. Private banking CEOs and senior investment gatekeepers described differing investment appetites, the importance of trust and the practical demands of introducing new products and technology. Their observations highlighted where broader access needed to be matched by a clearer investment rationale and a more manageable experience for advisers and clients.
Trust Remains the Starting Point
For one private banking CEO, the institution’s value rested on the confidence clients placed in it. “Trust is our main asset,” the participant said. New technology could change operations and create investment opportunities, but reputation and confidence in the people providing advice would remain fundamental. The same contribution expressed enthusiasm about the possibilities ahead while emphasising the need to look beyond the excitement around AI and examine investment fundamentals.
A fund specialist approached the issue through advisory discipline. Amid uncertainty about where and when to invest, the priority was to “stay invested with discipline and portfolio allocation”. Selecting ideas suited to the client remained central to the adviser’s role. Technology could improve the efficiency and quality of that work, while clients continued to value a personal relationship and advice delivered by people who understood their circumstances.
Looking Through the Portfolio to the Underlying Exposure
Investment sentiment was less uniform. An alternatives due diligence professional described clients whose consistently bullish stance had been rewarded over several years, alongside others becoming more cautious. A senior discretionary portfolio management professional acknowledged that the AI-led bull market had supported wealth management business in Asia. Those observations helped explain why advisers could be serving confident investors and more hesitant clients at the same time.
An investment platform head raised a different concern: the breadth of the market and the concentration of positions within it. “We are a bit nervous about how narrow the market breadth is,” the participant said. That concern extended beyond listed equities. Private equity and private credit could also be closely connected to technology, prompting questions about where genuinely uncorrelated returns might be found.
Another investment professional described interest in market-neutral and multi-strategy hedge funds as ways to participate while reducing market sensitivity. An equity specialist, meanwhile, reported frequent client questions about moving between computing infrastructure and software, with valuations influencing that debate. Together, the contributions showed why an alternatives allocation needed to be assessed through its underlying exposures and intended portfolio role, rather than through the asset-class label alone.
Making Wider Participation Work in Practice
Broader access brought its own questions. A private banking head asked about suitability and investor risk as alternatives reached a wider US investor base. A senior fund selection professional wanted to understand the educational hurdles encountered when introducing private equity and private credit. The emphasis was on how investors came to understand those products, alongside the opportunity to make them available.
An equity specialist also asked how digital platforms could serve both the wealthiest clients and the mass affluent. That raised the practical question of how access could be extended across different client segments. A managed investment solutions head was interested in how platforms would maintain their advantage as competition increased, while other participants sought a global perspective on investment flows and developments beyond funds.
A fund selection professional also questioned whether alternatives could complement or partly replace fixed income, leaving open how that role should be evaluated in a client’s portfolio.
Operational confidence mattered too. An investment platform head asked about smoother fund onboarding and greater transparency as ways to strengthen client trust. Separately, a senior private banker distinguished enthusiasm for AI investments from the harder task of getting advisers and clients to adopt digital tools. Education about using those tools remained a challenge. These contributions brought the discussion back to implementation: access had to be accompanied by the understanding and day-to-day support needed to put it to use.
About iCapital
Founded in 2013, iCapital is a global financial technology company supporting access to alternative investments, structured investments and annuities. Its platform connects wealth managers and asset managers, combining investment access with research, education, portfolio tools, transaction processing and ongoing reporting. Through its technology and data services, iCapital helps financial advisers incorporate these investments into client portfolios and manage them throughout their lifecycle.
For more information, visit www.icapital.com.