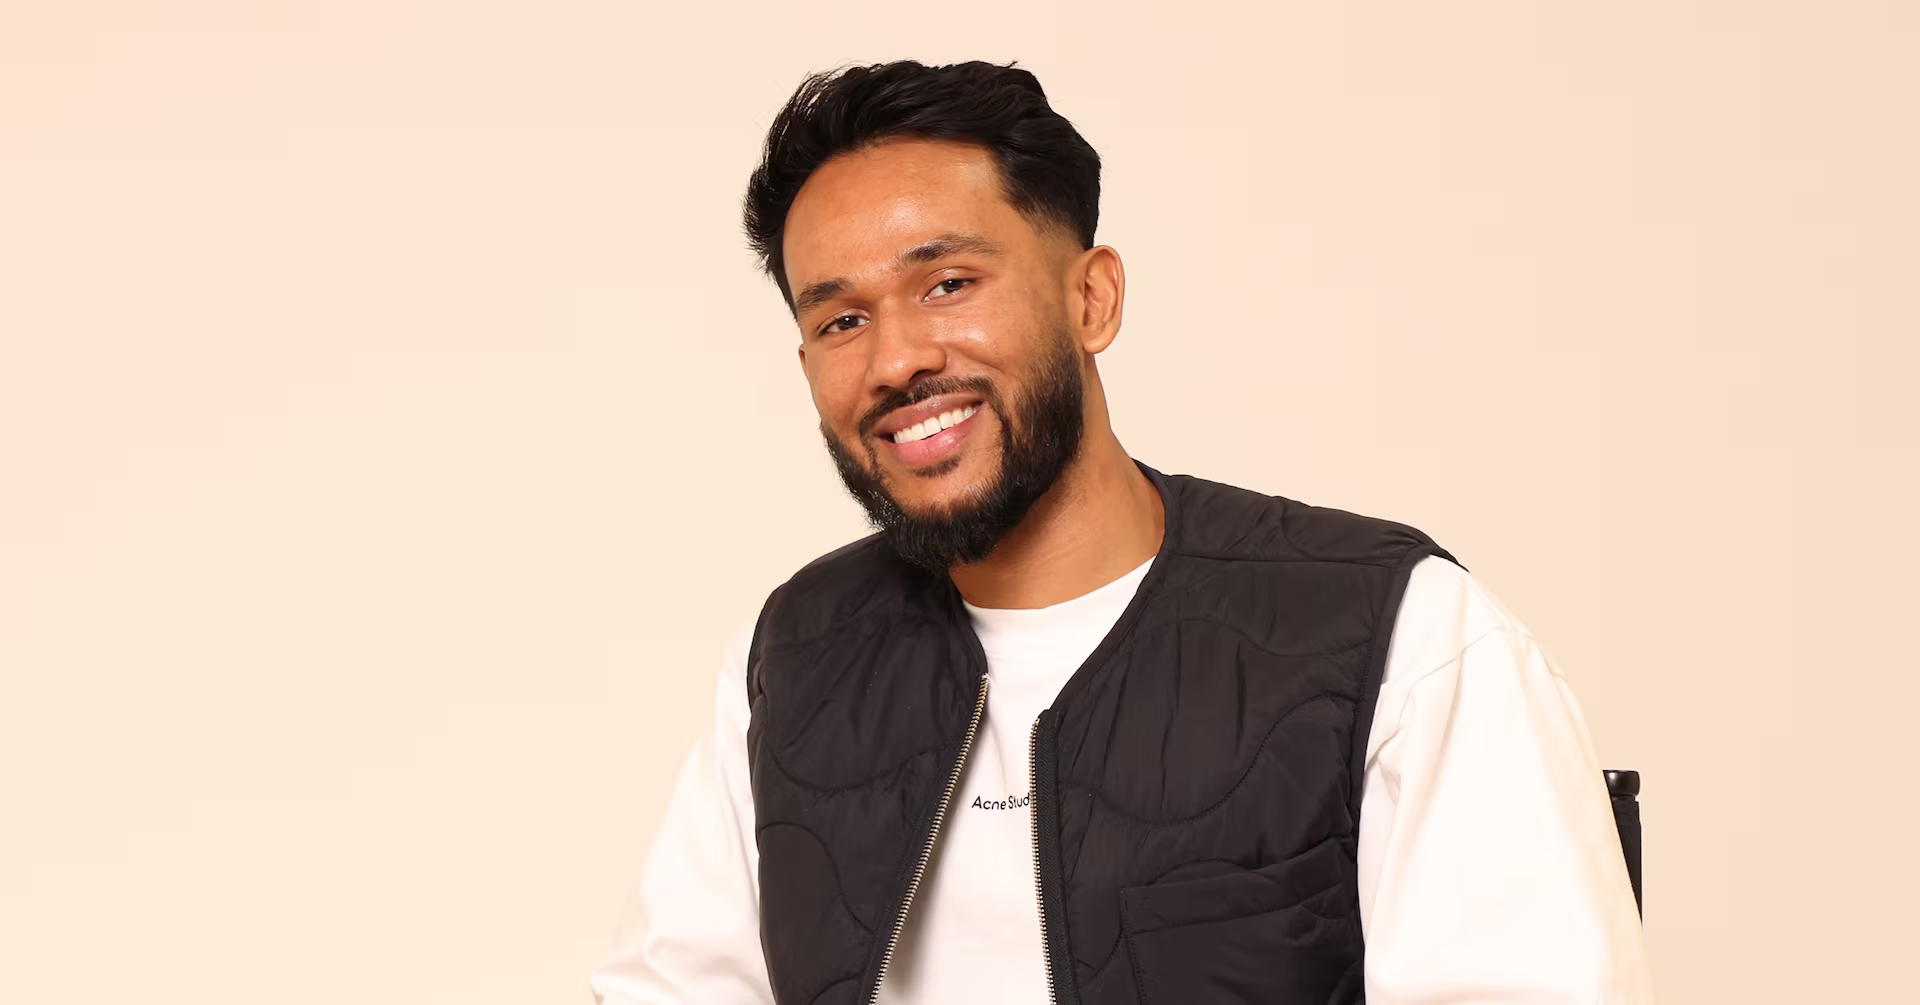
Niaz Azad, co-founder of Millennial Money UK. REUTER/Niaz Azad
A new year usually promises a fresh start. But for many young people, the financial pressures of 2025 have not eased: Cost of living remains high, home ownership feels out of reach, and AI is reshaping job security. Nearly half of millennials and Gen Z say they feel financially insecure, according to a recent Deloitte survey.
For many young professionals, the traditional path of a university degree and a good job no longer guarantees financial security. This frustrating reality inspired 32-year-old Niaz Azad to co-found Millennial Money UK, an online community helping his generation navigate a tough economy. “I think that came from a lack of financial literacy, so we tried to fix that … by building something where people felt like they could learn,” he says.
A man walks past property for sale and rent in Timperley, northern England, REUTERS/Phil Noble
Here are his top tips for young people to take into 2026:
Don’t fall into the trap of social media
High rents continue to stall young people’s efforts to get on the property ladder. For some, it’s a case of most of their income going straight to rent; for others, their savings simply don’t stretch far enough for a deposit. Whatever your situation, Azad says it’s important to remember that everyone’s journey to home ownership is unique — and that many people get help from their parents. “The big problem is the constant feed of comparison,” Azad says, noting that social media can amplify the pressure. “It’s important to just meet yourself where you are rather than trying to run someone else’s race.”
Invest early (and smartly)
Gen Z and millennials are investing more at younger ages compared to previous generations, according to a World Economic Forum study. If you have disposable income and are not in debt, educate yourself on how you can make your money work for you. “Saving your money isn’t going to help you build sustainable wealth,” Azad says. “And I think most people don’t realize that if they’re working, that they are already investing, likely through their pension.”
Avoid buy now, pay later schemes
While using “buy now, pay later” schemes for larger purchases may be tempting, overreliance can risk building bad financial habits. Azad offers a simple rule of thumb: if you need to split a payment into three months, you’re better off saving for three months to buy it outright. “You just have to be really careful and not find yourself in a position where you’re constantly buying things that you can’t actually afford because of the cheap credit,” he says.
Balance experiences and savings
Tourist play on a street near Patong beach in Phuket, Thailand. REUTERS/Athit Perawongmetha
A foreign backpacker sits at a bus stop with his belongings in central Sydney, Australia. REUTERS/David Gray
Should you spend your money traveling in your 20s, or save aggressively and see the world in your 30s? It’s a classic dilemma with no right answer. It’s important to figure out what works for you, Azad says. “There is an opportunity cost, but no one can tell you that… you just have to choose your sacrifice,” he says.
Sign up here.
Editing by Yasmeen Serhan and Lisa Shumaker
Our Standards: The Thomson Reuters Trust Principles., opens new tab