IMF hails UK’s budget deficit improvement
Newsflash: The International Monetary Fund has applauded the UK’s progress in reducing its budget deficit last year.
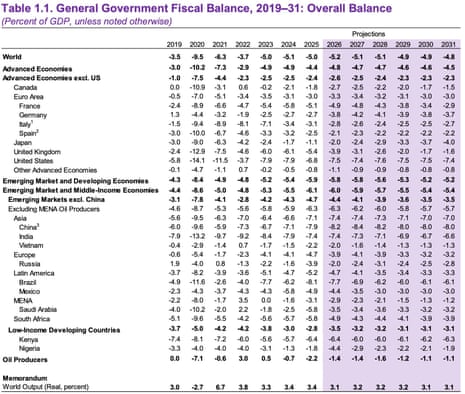
A day after slashing the UK’s growth forecasts, the IMF cited Britain as an example of an major economy which managed to trim its borrowings, after the UK’s deficit fell from 6.1% of GDP in 2024 to 5.4% in 2025.
In its latest Fiscal Monitor report, just released at its spring meeting in Washington, the IMF says:
double quotation markIn 2025, the headline deficit for advanced economies excluding the United States held broadly steady at 2.4% of GDP. The debt-to-GDP ratio for these economies fell only marginally to 95.3%, effectively unchanged from its 2019 level prior to the COVID-19 pandemic.
The United Kingdom recorded a notable improvement, reducing its deficit to 5.4% of GDP, with the change driven by tax increases, tax threshold freezes, and the expiration of temporary measures for energy support.
Canada and Japan also posted gains, reflecting spending restraint. These gains were partly offset by the use of some fiscal space by countries with historically strong fiscal positions, such as Korea and The Netherlands.
The IMF is forecasting that the UK’s annual budget deficit will drop to 3.9% of GDP this year, and continue falling until 2031 when it will be 1.6% of GDP, the second-lowest in the G7 after Canada.
In contrast, the US will need revenue and expenditure measures over the medium term to control its deficit, given “the persistence of primary spending and the scale of projected deficits”, the IMF says.
 Photograph: IMF
The Fund also warns Rachel Reeves not to stray from her fiscal rules, saying:
double quotation markIn the United Kingdom, adhering to established spending envelopes while strengthening the efficiency of value-added and property taxes is key to rebuilding buffers.
Updated at 09.06 EDT
Key events
Show key events only
Please turn on JavaScript to use this feature
Global financial stability seems to be holding for now, Georgieva says (which is slightly comforting…)
ShareIMF calls for countries to economise on energy supplies, and expects more lending programmes
The head of the IMF has predicted that at least a dozen countries, including some in Sub-Saharan Africa, will seek new lending programmes due to surging energy prices and supply chain disruptions caused by the war in the Middle East.
International Monetary Fund managing director Kristalina Georgieva has repeated her estimate that the war could trigger demand for $20bn to $40bn in lending that could include augmentation of existing programs and new programs.
Georgieva began her press conference in Washington DC (see the top of this blog to watch it) by telling reporters that her hopes and prayers are for the Middle East ceasefire to lead to a durable peace.
Georgieva also warned countries against taking untargeted actions such as broad energy subsidies to offset the impact of higher prices, saying they would only “prolong the pain of high prices.”
She warned that there are shortages of oil and gas, naptha, helium and other products in Asia, and expressed concerns about the risk of higher food price inflation unless fertilizer delivery at reasonable prices resume soon.
As flagged earlier (here), the IMF is also encouraging countries to economize energy use, through measures such as free public transport.
Georgieva argues that the energy shock will incentivize measures to reduce demand.
Updated at 10.56 EDT
On the threat to inflation, Georgieva says that short term inflation expectations are moving up in Europe and in the US.
But long-term inflation expectations remain “well anchored”, she adds.
Q: What should central banks do about the crisis, to keep inflation under control?
IMF chief Kristalina Georgieva says that central banks with high credibility should signal that their priority is price stability, but not take action straight away.
However, she warns that central banks without credibility may need to move more quickly.
Updated at 10.58 EDT
March was a tough month for the global economy, but April is likely to be tougher, Georgieva adds.
That’s because the oil tankers that left the Gulf at the end of February have now reached their destination, and there aren’t more following (yet).
Updated at 10.40 EDT
Georgieva: Countries should consider economising energy, or encouraging WFH
IMF chief Kristalina Georgieva is taking questions now at a press conference at the IMF’s Spring Meeting – you can watch it online at the top of this blog.
Asked about the impact of the Iran war on the global economy, Georgieva says the IMF is “concerned about the physical breakdown in supply chains”.
She points out that the disruption caused by the conflict will not be resolved straight away once it is over.
She points out that tankers are slow-moving vessels, saying:
double quotation markIt will take 40 days to get all the way to Fiji [from the Middle East].
As such, countries should consider various steps, such as:
Using measures to economise energy – such as making public transport free.
Encourging people to work from home – Georgieva point out that “we did it though Covid”.
Encouraging a switch to less energy-intensive activities over time.
 IMF Managing Director holds a news conference on Global Policy Agenda – watch liveShare
Updated at 10.37 EDT
Finance ministers call for swift end to Iran war
A group of 11 finance ministers, including UK chancellor Rachel Reeves, are calling for a swift and lasting negotiated resolution to the conflict in the Middle East.
In a joint statement, finance ministers from the United Kingdom, Australia, Japan, Sweden, the Netherlands, Finland, Spain, Norway, Ireland, Poland and New Zealand warn that the Iran war will continue to weigh on global growth, inflation and financial markets even once it is durably resolved.
The group of finance chiefs are calling on all parties to implement the ceasefire in full, saying:
double quotation markThe past weeks have brought unacceptable loss of life and significant disruption to the global economy and financial markets, and the ceasefire will be crucial to protecting civilian populations and the security of the region.
They also call for a swift and lasting negotiated resolution to the conflict, and a return to free and safe transit through the Strait of Hormuz.
The group also call for an end to protectionist actions in hydrocarbon and other supply chains, adding “We commit to promoting cooperation and integration to support regional and global stability.”
And they conclude by reaffirming “unwavering support for Ukraine” and pledge to maintain economic pressure on Russia, saying:
double quotation markRussia’s war in Ukraine, now in its fifth year, continues to negatively impact the global economy. Russia must not benefit from this conflict, and as market conditions allow to avoid exacerbating disruptions to supply chains and energy prices, we will continue collaborating on ways to increase pressure. We remain committed to upholding the rules based international system.
ShareRevealed: How Donald Trump drives up geopolitical risk
Donald Trump has added to geopolitical risk today by threatening to row back on the trade deal the US signed with the UK last year.
Professor Costas Milas, of the Management School at University of Liverpool, has created a graph showing how Trump can inflame geopolitical risk, for months.
Photograph: Professor Costas Milas
Professor Milas explains:
double quotation markPresident Trump keeps on dominating the news with aggressive, contradicting, and often opaque statements. His latest one? That he might reconsider the US-UK trade deal.
There is no doubt, in my mind, that Trump himself is a big source of geopolitical risk. Why? Consider a Google measure of Trump dominating the news together with global geopolitical risk acts (from the website of Matteo Iacoviello). I collect monthly data from 2015 (first term of Trump as President) and show below how a “shock” to Trump news raises global geopolitical risk acts for as many as nine (9) months.
The impact is statistically significant using a 95% confidence interval. World leaders do take notice!
ShareIMF: Support on energy or food costs should be ‘targeted and temporary’
The IMF is also warning governments to be careful when providing support to citizens through the cost of living pressures created by the Iran war.
In a blog post to accompany today’s Fiscal Monitor, they say:
double quotation markIf governments decide to help companies and families facing higher energy or food costs, this support should be targeted and temporary, focusing on those most exposed and least able to absorb price increases. Many countries built effective social safety nets during the pandemic; these mechanisms can—and should—be used again.
Countries with “narrow fiscal space” should avoid financing support measures with additional borrowing, the Fund argues, saying:
double quotation markA better approach is to reallocate spending within the same limits and prioritize crisis-related spending (which could be more politically feasible).
The alternative is to lock in higher debt and higher interest costs, which will eventually force tougher choices—or worse, destabilize government debt markets and worsen conditions today.
Updated at 09.17 EDT
IMF hails UK’s budget deficit improvement
Newsflash: The International Monetary Fund has applauded the UK’s progress in reducing its budget deficit last year.
A day after slashing the UK’s growth forecasts, the IMF cited Britain as an example of an major economy which managed to trim its borrowings, after the UK’s deficit fell from 6.1% of GDP in 2024 to 5.4% in 2025.
In its latest Fiscal Monitor report, just released at its spring meeting in Washington, the IMF says:
double quotation markIn 2025, the headline deficit for advanced economies excluding the United States held broadly steady at 2.4% of GDP. The debt-to-GDP ratio for these economies fell only marginally to 95.3%, effectively unchanged from its 2019 level prior to the COVID-19 pandemic.
The United Kingdom recorded a notable improvement, reducing its deficit to 5.4% of GDP, with the change driven by tax increases, tax threshold freezes, and the expiration of temporary measures for energy support.
Canada and Japan also posted gains, reflecting spending restraint. These gains were partly offset by the use of some fiscal space by countries with historically strong fiscal positions, such as Korea and The Netherlands.
The IMF is forecasting that the UK’s annual budget deficit will drop to 3.9% of GDP this year, and continue falling until 2031 when it will be 1.6% of GDP, the second-lowest in the G7 after Canada.
In contrast, the US will need revenue and expenditure measures over the medium term to control its deficit, given “the persistence of primary spending and the scale of projected deficits”, the IMF says.
Photograph: IMF
The Fund also warns Rachel Reeves not to stray from her fiscal rules, saying:
double quotation markIn the United Kingdom, adhering to established spending envelopes while strengthening the efficiency of value-added and property taxes is key to rebuilding buffers.
Updated at 09.06 EDT
IMF: Global debt still on track to hit 100% of GDP by 2029
Newsflash: The International Monetary Fund is warning that the war in the Middle East has added a new source of fiscal pressure to the global economy.
In its latest Fiscal Monitor report, just released, the IMF points out that global public debt dynamics did not improve in any material way in 2025, even before the Iran conflict drove up the oil price.
It says:
double quotation markThe conflict has material global reach, disrupting energy supplies, tightening financial conditions, and forcing governments to choose between shielding their populations from price spikes and preserving fiscal space.
The IMF also warns that the fiscal picture has worsened coompared with a year ago – when Donald Trump’s trade wars were causing instability.
Global gross government debt rose to nearly 94% of GDP in 2025, and is on track to reach 100% by 2029, for the first time since the aftermath of the second world war (as the IMF also warned last October).
The IMF says the the projected increase in global debt largely reflects the increase in debt in the world’s two largest economies, China and the US, explaining:
double quotation markThe United States is running a general government deficit of 7 percent to 8 percent of GDP despite operating near full capacity, with no debt consolidation plan in sight, and its gross debt is projected to reach 142 percent of GDP by 2031.
China’s near-term fiscal expansion, aimed at supporting domestic demand amid deflationary pressures, has widened the country’s overall deficit to nearly 8 percent of GDP, and persistent large deficits are expected to push its debt toward 127 percent of GDP by 2031.
Updated at 09.16 EDT
Bessent: US will avoid long-term inflation hit from Iran war Richard Partington
The US Treasury Secretary Scott Bessent says the economic shock from the Iran war will pass without driving up long-term inflation in the US, my colleague Richard Partington reports from Washington DC.
“This war will end. I don’t know if it’s 3 days, 3 weeks, 3 months, but we will get on the other side of this,” Bessent said.
double quotation mark“There’s always a catch-up, there’s pent-up demand.”
Speaking at the CNBC Invest in America conference in Washington on Wednesday, Bessent also said the US Fed was in danger of being caught out by falling inflation.
double quotation mark“I understand why they’re doing it [holding on rates]. It wouldn’t be necessarily my base case. I ‘d at least be ready to cut and I’d have an open mind that they may need to cut more because they’ve waited longer.”