
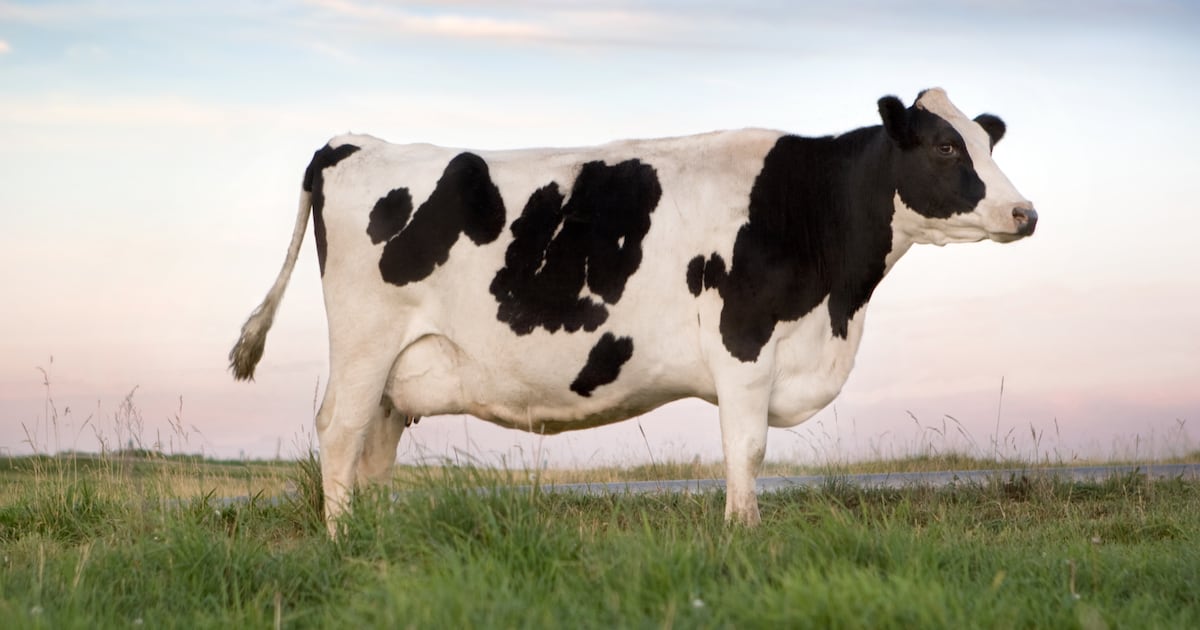
Key takeawaysFeed constraints may limit dairy herd growth despite high milk prices.Fertiliser uncertainty could pressure feed availability and crop yields.Strong demand for dairy protein is helping keep markets tight.
First, it was beef. Global beef prices have reached elevated levels as supply constraints have collided with strong consumer demand.
Prices have been climbing steadily since the pandemic, with high feed costs and recurring droughts forcing producers to reduce herd numbers. According to the OECD-FAO, global beef reference prices reached a four-decade high in 2025, with limited animal inventories and the slow process of herd rebuilding expected to keep prices high in the near term.
Upstream, feed availability and cost have been major drivers of this dynamic. Feed markets have remained exposed to successive supply shocks, from pandemic-era processing disruptions and the war in Ukraine to the geopolitical tensions of 2026, which have upended energy, fertiliser and trade flows.
Fertiliser uncertainty is now feeding into planning for the 2027 crop season, with the International Fertilizer Association warning that a prolonged disruption could lead to rationing and lower crop production.
For dairy, there could be major consequences.
“Typically, dairy prices are considered the most mean-reverting of all prices,” said Brian Quinn, chief product officer at Quoreka, a commodity trade and risk management software provider.
This is because when prices rise, producers are incentivised to increase their herds and deliver more milk, with stocks of powders and other finished products also easing to address demand.
But the state of the feed market today may be disrupting that cyclicality. While high prices and a resilient demand support strong production, feed availability and affordability – themselves dependent on fertiliser flows and crop yields – may in effect constrain cow numbers.
“If you can’t feed the cows, you can’t bring more cows online,” said Quinn.
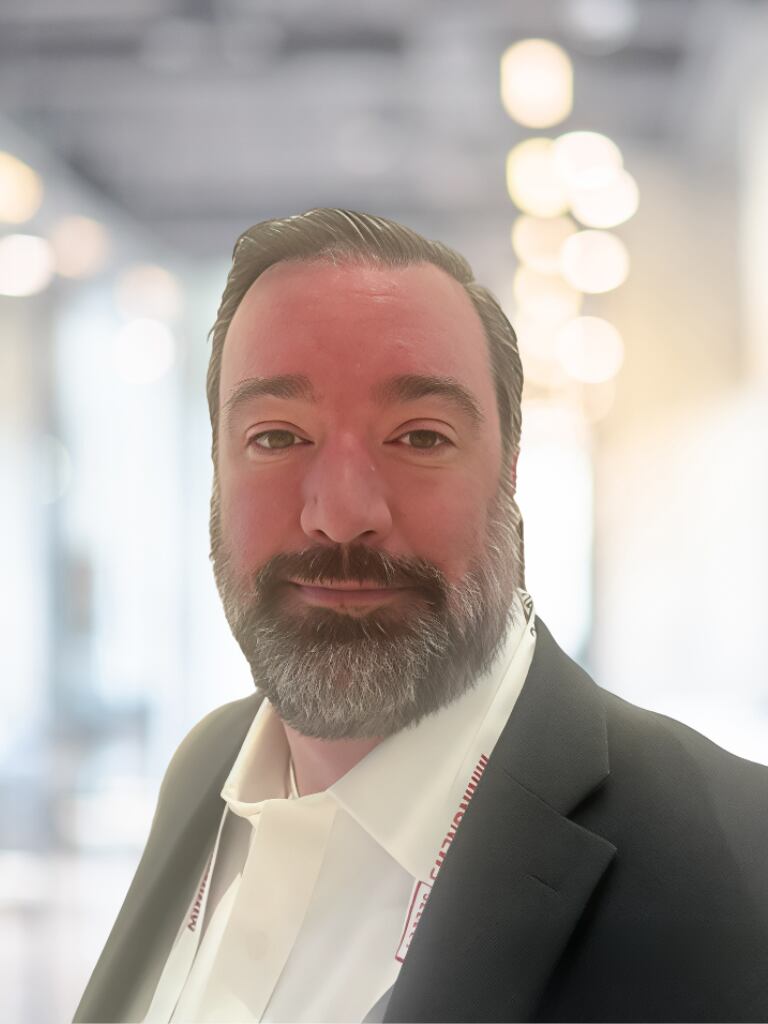 Brian Quinn of Quoreka (Quoreka)
And crop prospects have already been affected across key markets including Europe and North America, though Brazil’s bumper year is offsetting some of the global pressure.
Nevertheless, pressures in the feed space may keep dairy prices tight for longer.
“Demand is staying up and supply is not coming up,” said Quinn. “The cost and availability of feed is making it difficult to produce more.”
These dynamics are compounded by the strong demand for dairy protein. In the US, the rise of GLP-1 weight-loss medications and the broader shift towards high-protein diets are supporting demand for whey protein.
But that creates another complication: producing whey means producing other dairy commodities.
“If we are able to increase milk production, I think you’d see the rest of the dairy complex relax a little bit,” he said.
He points to oil production, where refineries cannot increase crude oil production just to meet demand for diesel without also producing other by-products.
And usually, the additional supply would eventually help ease prices.
But the uncertainty now is whether constraints upstream would disrupt that cycle – and cost producers more until prices reach equilibrium.