September 29, 2026 — 4:00pm
Save
You have reached your maximum number of saved items.
Remove items from your saved list to add more.
AAA
I’ve come into an inheritance and am anxious about what I should do with the money. I’ve never really had this much money to manage in the first place. I have a fully paid off home. I’ve also never worked with financial professionals, so I don’t know how to go about that. I worry about being taken advantage of. I don’t want to squander the money, but I don’t know how to make good use of it. How should I go about this?
It’s easy to spend a lifetime thinking that “if only I had more money,” your financial stress would disappear. However, it’s not the money alone that solves the stresses, it’s your confidence in your ability to manage the money you have. So, what’s the way forward?
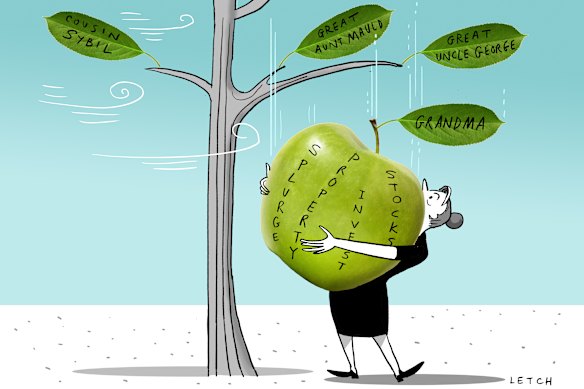 It can be difficult to work out what to do with a large inheritance.Simon LetchTake the pressure off yourself to figure out what to do
Sitting on a lump sum of cash can be far more anxiety inducing than people expect. There might be a nagging anxiety to “do something” with the money, but you don’t know what.
A lot of less-than-ideal decisions are made from a desire to alleviate this anxiety, quickly. You want to stop feeling this pressure, so you rush the decision: you sign up with the first financial advisor your friend recommends, or follow your uncle’s well-meaning suggestion to buy a property. At least now you’ve decided, now you can move on with your life.
Slow down. Give yourself permission to take some time to figure out how to make a decision that you feel confident and comfortable with.
However, often that anxiety just gets deferred. Before, you were anxious about doing something with the money. Now, you’re anxious about whether you made the right decision.
So, slow down. Give yourself permission to take some time to figure out how to make a decision that you feel confident and comfortable with.
Get clarity on your current financial position
I get my clients to create a “balance sheet” – a list of all their assets and liabilities, categorised into the different asset classes (e.g. cash accounts like savings, investment accounts, property and so on). This is going to give you a one-page snapshot of your financial situation.
Related Article Think about your wealth in three portions
You have a home, your investments (inside and outside superannuation), and your savings. You’ve already got a fully paid off house, which is great. So the focus for you will be on your savings and investments. You will want to get some clarity on how much you intend to keep in cash (i.e. savings) versus how much you intend to invest. My general rule of thumb is: don’t invest money you think you’ll need to spend in the next three to five years. For example, if you’re going on a world tour next year don’t invest that money.
So, think about how much money you need for regular expenses, as well as how much you might want to put towards any bigger expenses in the next couple of years. You now have a rough idea of how much to keep in cash versus how much you can put towards investments.
A two-fold investment: inside versus outside super
The main advantage of investing inside superannuation is that it is possible to save a lot of money on taxes by investing through your super fund. The main drawbacks of superannuation is that the money in super will not be accessible to you until you’re at least 60 to 65.
So, you want to ask yourself: “Of the money I have available to invest, how much am I okay to not access until I’m in my 60s versus how much would I like to have available to me before then?” This is going to help you clarify how much to invest inside versus outside superannuation.
Start to learn about how investments work
Now, it’s up to you how far down this rabbit hole you go. The goal isn’t to necessarily DIY your own investments. You may be happy to pay a little extra to have someone do that for you.
Related Article
However, even if that is the case, having some foundational knowledge of how investing works will help you feel more confident in your ability to hire and manage the relationship with a financial professional. Investing is a big world, but a good starting point is learning how index funds and ETFs work. What do terms like “asset allocation” and “diversification” and “dollar cost averaging” mean, and how should one change one’s asset allocation over time?
This is roughly the same process anyone can go through. Whether you have $10,000 or $100,000 or $1 million in the bank, it doesn’t really change the foundational steps required to build financial confidence and capability. Just like, whether you’re sitting in a BMW or a Toyota, the steps required to learn how to drive are the same.
Paridhi Jain is a money and mindset coach who combines practical strategies with mindset transformation to help clients create more freedom and fulfilment in wealth, work and life. Find Paridhi at: skilledsmart.com.au.
Advice given in this article is general in nature and is not intended to influence readers’ decisions about investing or financial products. They should always seek their own professional advice that takes into account their own personal circumstances before making any financial decisions.
Expert tips on how to save, invest and make the most of your money delivered to your inbox every Sunday. Sign up for our Real Money newsletter.
Save
You have reached your maximum number of saved items.
Remove items from your saved list to add more.
 Paridhi Jain is a money and mindset coach who combines practical strategies with mindset transformation to help clients create more freedom and fulfillment in wealth, work, and life.From our partners