
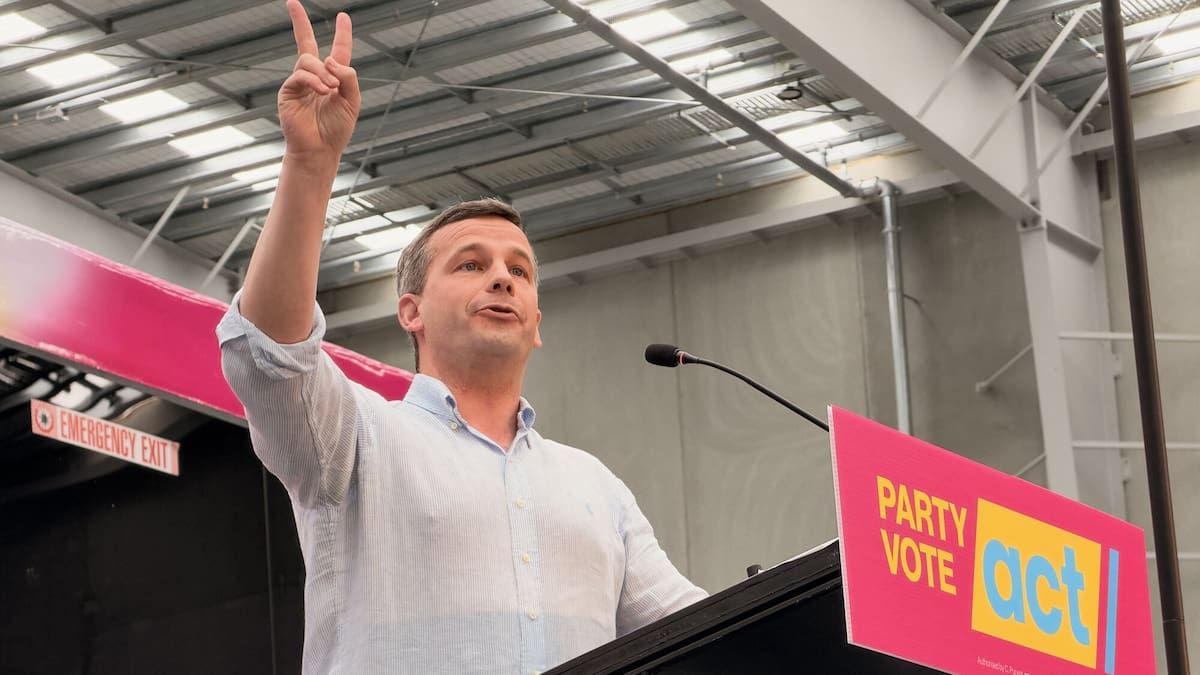
Act leader David Seymour announced the policy at the party’s campaign launch on Sunday. “Other parties want to force your money into KiwiSaver, then tax you,” he said.
Act puts the net cost at $2,396,000,000 (almost $2.4 billion) over the four years to 2030/31.
That is $4,082,000,000 for removing tax on KiwiSaver earnings and $904 million for non-KiwiSaver super (less $2.59b saved by ending the subsidies).
The party says a 20-year-old builder on $60,000 would have an extra $209,486 at 65. A 50-year-old office manager on $80,000 would have an extra $20,878. Both assume the average KiwiSaver balance for their age.
What do people say about it?
The policy has generally been received well by those in the financial investment sector who want to see New Zealand boost its overall savings rate.
Tax adviser Terry Baucher told RNZ that the policy would boost superannuation savings.
But he has warned that it would be more beneficial to higher earners and people with bigger KiwiSaver balances.
So on that basis, it doesn’t address the equity issues that other parties are seeking to address with compulsion and higher employer contributions.
Act is opposed to compulsory savings regimes, so this is an ideologically consistent way for the party to get on board the KiwiSaver reform bandwagon.
How does it compare with other parties’ policies?
National, New Zealand First, Labour and the Opportunity Party are all proposing to boost KiwiSaver by increasing the minimum contributions and by making it compulsory to join.
National would make KiwiSaver compulsory from July 1, 2028 and lift employee and employer contributions to 6% each by 2032. Babies would get a $1500 starting payment.
Labour would only make the employer contribution compulsory and lift it to 6%, while the employee rate rises progressively to 6% by 2032. Employers would have to keep contributing if a worker pauses their own contributions. It would also ban “total remuneration” contracts that absorb the employer contribution into salary.
New Zealand First wants every newborn citizen automatically enrolled with a $1000 payment and higher minimum contributions of up to 10%.
The Opportunity Party proposes a compulsory “KiwiSaver 2.0” with 6% contributions from employers and workers.
Is it likely to happen?
It seems unlikely Act would get this through coalition talks. Both National and NZ First (Act’s likely coalition partners) have policies which push compulsory savings, boost contributions and introduce a new government kickstart.
Those policies are well aligned, so the weight of numbers in any centre-right coalition talks would be against Act.
That said it is not impossible and a lot would depend on the final vote count and the various other policy trade-offs to be made.
The bottom line – would it be good for New Zealand?
Economist (and a prominent proponent of KiwiSaver reform) Leonard Hong says the policy would boost private household savings and support capital accumulation in the economy.
On balance, it would be good for New Zealand, he says.
But Hong much prefers Labour and National’s approach overall.
“Act have never liked KiwiSaver for time immemorial and this is an attempt to make themselves relevant to the discussion,” he says.
“I’d emphasise that this will further worsen inequality for the poor if it should remain voluntary, becoming a tax cut for the rich, who have massive accumulation of capital via KiwiSaver funds already.”
But more broadly, Hong is pleased to see another party looking to boost savings.
“It’s fantastic that most political parties have their own version of KiwiSaver policies,” he says.
“Act’s tax tweaks go further than what I was recommending but if something like a switch to [a tax-exempt] model is feasible in the next Government, everyone in the country will benefit.”
Liam Dann is business editor-at-large for the New Zealand Herald. He is a senior writer and columnist, and also presents and produces videos and podcasts. He joined the Herald in 2003.