
Back in August, Counterpoint Research estimated a total of 35 million smartphone shipments in Europe during the April – June period (Q2). We now get a more detailed breakdown of the shipment figures and their share between retailers and carriers. While shipments by open market (retailers) saw a slump of 11% compared to Q2 2025, the operator channel (carriers) only experienced a 4% decrease for the same period.
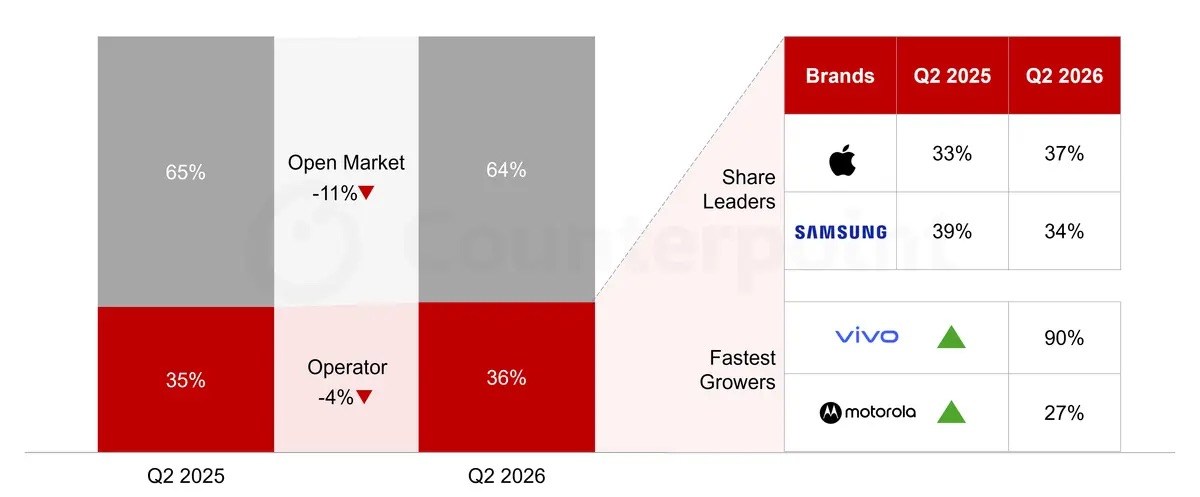
Europe Smartphone Sales Share by Channel (Counterpoint Research Europe Channel Share Tracker)
As Counterpoint analysts explain, carriers usually move higher-end devices compared to retailers. The ongoing slump in the budget segment due to the memory chip crisis diminished shipments for entry-level devices, which were mostly driven by independent retailers.
Apple actually overtook Samsung as the leading brand by carrier shipments in Europe with its 37% share. Samsung came in second with 33% while vivo and Motorola were the faster growers in the segment. Looking ahead, Counterpoint analysts expect the trend of carrier shipments to continue their upward trajectory compared to retailers.