
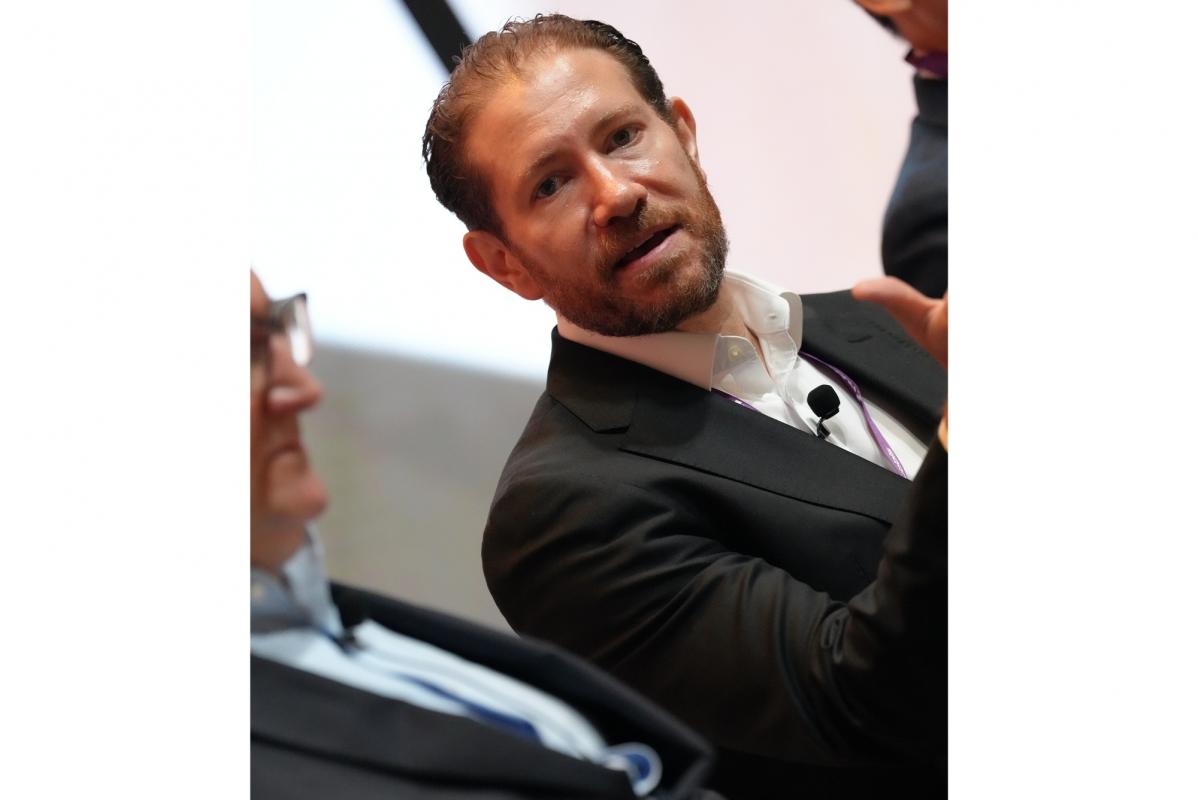
For large universal banks operating in Asia’s private wealth market, the challenge of differentiation is shaped less by any single capability than by the range of what the platform can offer and the discipline required to match that range to what each client actually needs. As competition for high-net-worth and ultra-high-net-worth clients intensifies across private banks and independents alike, Bregman argued that understanding individual client priorities is central to delivering value.
At the Hubbis Investment Forum Singapore 2026, held at the JW Marriott South Beach on 17 September, the opening panel explored how private banks and independent wealth managers are seeking to prove their value in an increasingly crowded market. The discussion, chaired by Michael Stanhope, Founder and Chief Executive Officer of Hubbis, brought together leaders from across the wealth management spectrum. Garth Bregman, Head of Wealth Management Singapore and Southeast Asia at BNP Paribas Wealth Management, drew on 14 years in the region to describe how the firm’s universal banking model serves clients with different priorities, why open architecture has become the industry norm, and how the bank is investing in generative AI and philanthropy to meet emerging demand.
Key Takeaways
Discretionary portfolio management penetration in Asia remains low relative to other regions, and Bregman noted that what firms believe clients should prioritise may sit quite low on a given client’s actual list of needs.
The universal banking model allows BNP Paribas to serve clients across a wide range of needs, from investment management and complex structured finance to balance sheet lending and access to the investment bank.
Open architecture is now established across the private banking industry, and the bank measures client satisfaction in part through the proportion of net new cash that comes from existing clients increasing their allocation.
Next-generation clients span a wide age range and cannot be retained through parental loyalty alone, requiring relationship managers to demonstrate value independently of the existing family relationship.
A dedicated AI Centre of Excellence and the launch of BNP Paribas Bridge Foundation, a donor-advised fund were identified by Bregman as the two most significant initiatives of the past twelve months.
Understanding What Clients Actually Need
Bregman opened by describing how his own perspective has evolved since arriving in Asia 14 years ago as head of discretionary portfolio management. His starting point, rooted in his asset management background, was that the most important thing for clients was to establish a strategic asset allocation, build the right risk-return profile and compound risk premia over many years.
“Selling long-term strategic asset allocation was pivotal to me in those early years, and we have grown our DPM penetration rate in assets every year,” Bregman said. But he acknowledged that DPM penetration rates in Asia remain lower than other regions, linking this partly to the fact that clients do not necessarily place the same priority on long-term risk-adjusted returns that investment professionals might. “What we think our clients’ priorities should be, which is perhaps generating fantastic risk adjusted returns, might be quite low on their priority list.”
As a universal bank, BNP Paribas attracts clients for a variety of reasons. Some come for the investment platform, which is also a reason external asset managers choose the bank as a custodian. Others are drawn by the strength of the balance sheet and the ability to lend not only against a private banking portfolio but also to operating companies, or to arrange collar financing on listed equity and other complex forms of structured finance through the investment bank. “There’s no client that uses the whole platform,” Bregman noted. “It’s too broad, too deep.”
The bank’s priority, he said, is to understand what each client is looking for and to ensure the firm is delivering accordingly, whether that means portfolio-based advisory, philanthropy, different forms of credit, or trading. BNP Paribas launched a donor-advised fund earlier this year to serve clients with a growing interest in structured giving.
Open Architecture and Measuring Client Satisfaction
During a broader panel exchange about whether private banks can genuinely act in the best interests of their clients, Bregman addressed the question directly. He said private banker are commercial businesses, and the industry should be open about that. In his view, the real test is whether being commercially successful and serving clients well go together.
The more relevant measure, he argued, is client behaviour. Around 50 per cent of the firm’s net new cash each year comes from existing clients who are increasing their allocation to the bank. “You can only raise new cash from clients who are happy,” he said, describing share of wallet growth as a practical indicator of whether the firm is meeting client needs.
On the question of product distribution, Bregman was clear that the industry’s shift to open architecture is substantive. He pointed to the number of counterparties the bank works with across mutual funds, hedge funds, private assets, and structured products, as evidence that proprietary product distribution is no longer the operating model. “We should give up the idea that we are just selling bank products,” he said. “Those days are long gone, probably more than 10 years ago.”
Engaging the Next Generation
On the subject of intergenerational wealth transfer, Bregman cautioned against treating the next generation as a single demographic. “The next gen may be in their 60s,” he said. “They can range from their teens to their 60s, because every family manages their handover differently.” In some families, a patriarch or matriarch in their nineties still holds the reins, while in others, children in their twenties are already being brought into the family business or wealth management arrangements.
The common challenge, Bregman said, is that no firm can rely on the parental relationship to secure the loyalty of the next generation. Many of these clients attended leading universities around the world and count private bankers at competitor institutions among their personal networks. “You have to create value for them. It’s no different from their parents. They have to see you as not just someone that their parents bank with, but someone who can add value to them.”
Bregman acknowledged that not every next-generation client will stay. “We will not be able to retain all of them or all of the wealth when they get it, but we want to be able to retain a lot of them.”
Generative AI and Philanthropy
Asked to identify the most significant initiatives of the past twelve months, Bregman pointed to two. The first is the creation of a AI Centre of Excellence within BNP Paribas Wealth Management in Asia. The centre has a dedicated team researching generative AI applications and implementing them across the private bank, covering areas from client onboarding to augmenting the capabilities of relationship managers. Bregman described it as a concerted and high-profile effort with dedicated resources.
The second is the donor-advised fund launched earlier in the year, the second such fund in Asia. Bregman said the bank is seeing considerable interest from clients, noting that it addresses a need “which you can’t really meet unless you’re a larger organization or institution.”
Growth and Its Constraints
Bregman framed the outlook for the industry around a single overriding fact: the wealth pool across the region continues to expand. “The pie continues to grow,” he said. “Whether it’s mass affluent all the way up to ultra high net worth or large family offices, we’re all able to grow because the pie is growing.” He noted that most private banks, as well as many external asset managers and independents, have grown in recent years, driven by underlying wealth creation rather than market performance alone.
He was equally direct about the principal risk. If wealth creation were to slow materially, whether through a significant recession or otherwise, the competitive pressure across the industry would intensify considerably. “You will really see pressure on the entire wealth management industry more broadly,” he said, while adding that the near-term outlook remains supportive. “We continue to anticipate good growth rates in wealth.”