
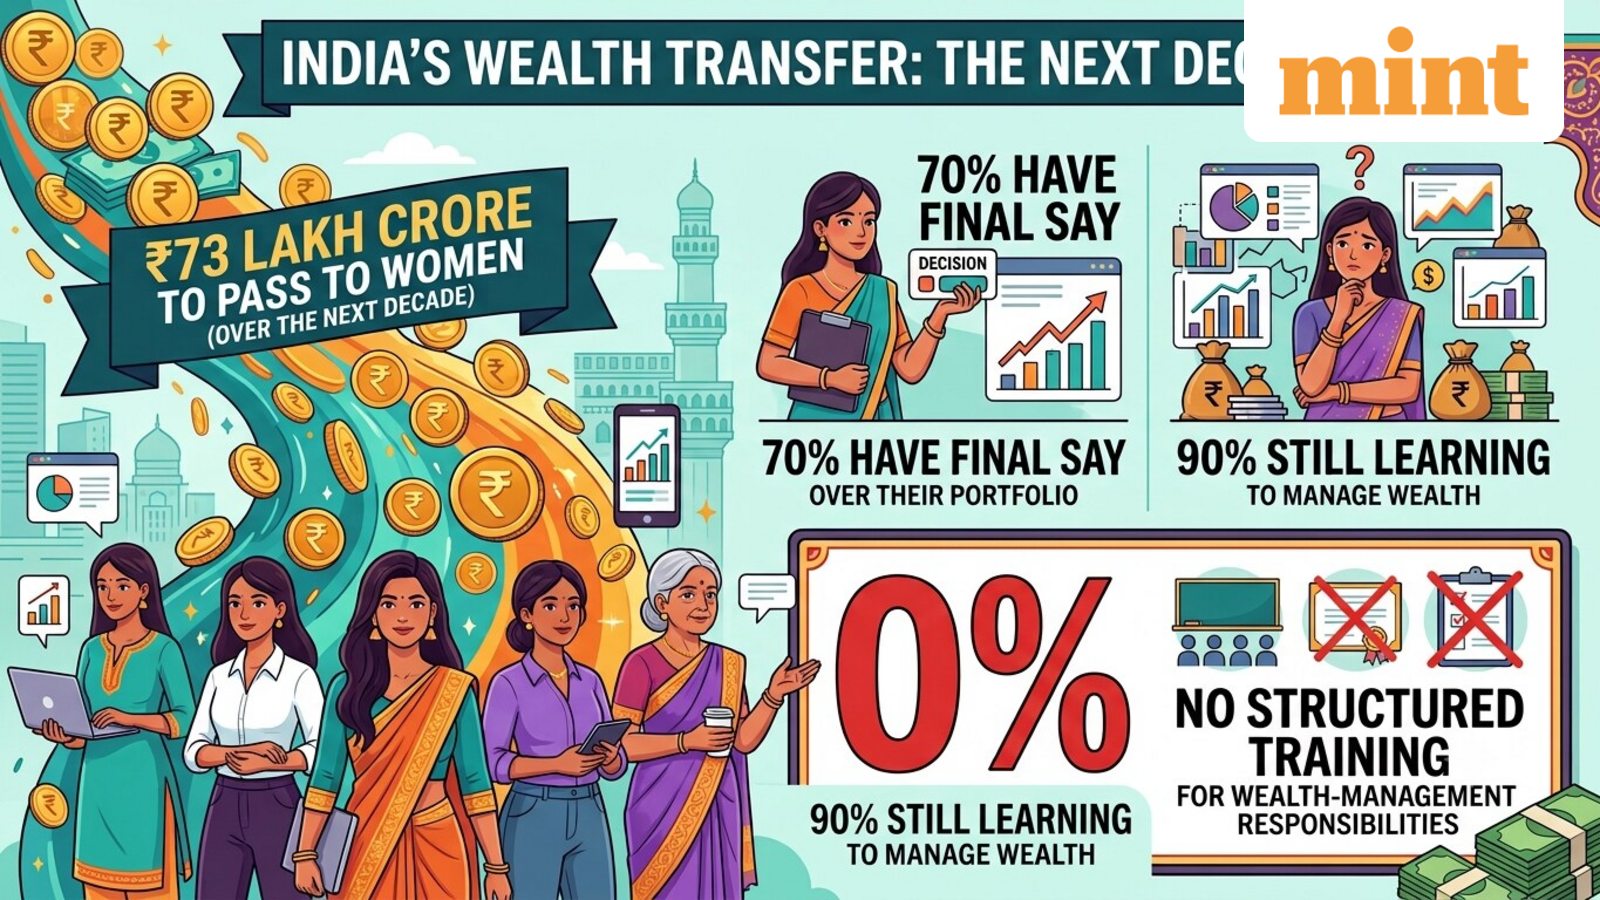
A majority of women investors, who lead their families’ wealth decisions, are still learning and did not receive structured, financial training, which exposes a gap in wealth succession for the demographic, according to a report by Equirus Wealth.
The ‘Shakti & Capital: Next-Generation Women and the Future of Indian Family Wealth’ study found that four in 10 women interviewed by Equirus Wealth assumed responsibility for wealth decisions following a significant life event, including bereavement, separation, capital loss or inheritance, rather than through a planned introduction to family finances.
It noted that a key challenge thus is that financial responsibility can arrive before individuals acquire the knowledge and experience needed to exercise it confidently.
Also Read | 8th pay commission: Constituted in November 2025—Key updates almost a year later
“Approximately ₹73 lakh crore could pass to women in Indian families over the next decade. But the larger question is whether the knowledge and decision-making capability needed to manage this wealth will pass on with it. Families devote considerable attention to building and preserving wealth, but preparing the next generation to manage it deserves equal attention,” according to Nitesh Arora, Managing Partner at Equirus Family Office.
Primary objectives: Financial independence, peace of mind
According to women investors and inheritors served by Equirus Family Office,
70% have the final say over a portfolio, while 90% say they are still learning to manage wealth.0% received structured training for their wealth-management responsibilities.100% participate in family wealth discussions, but only 40% are directly involved in capital allocation or investment origination.40% of respondents entered wealth decision-making following a significant life event,Only 30% were introduced to these responsibilities by family members.Also Read | DA news: Himachal Pradesh to release dearness allowance installment for DiwaliAnother 30% began their investment journey through their own earnings or employer shares.60% grew up in households that emphasised saving but offered limited investment guidance.50% describe their successors as not yet ready or not yet engaged, while only 30% deliberately prepare the next generation.For 50%, financial independence and peace of mind are the primary objectives, reflecting a desire for security, personal choice and the freedom to pursue life on their own terms.Another 30% view wealth primarily as a platform for the next generation to build upon,While 20% identify giving as its principal purpose.Also Read | Mutual funds stop bulk gold ETF subscriptions — Here’s what has changedWhen it comes to significant decision-making responsibilities, financial education remains largely experiential.While 70% of respondents report having the final say over a portfolio, 90% acknowledge that they are still learning — pointing to a gap between the authority women exercise and the structured financial training available to support them.From wealth transfer to capability transfer
“The findings point to a clear agenda for families, family offices and advisors — give the transfer of capability the same deliberate attention as the transfer of assets,” the report added. It listed five actions can help make that shift:
Open the books before an event does
Begin family wealth conversations before a health event, bereavement, separation or succession deadline makes them urgent. Establish a regular forum for discussing assets, responsibilities and family objectives.
Give successors responsibility, not just information
Bring the next generation into portfolio reviews, explain the reasoning behind decisions and, where appropriate, introduce a supervised investment mandate with defined limits and accountability.
Also Read | 8th pay commission: Check salary hike for fitment factor of 1.83, 2, 2.57, 3.83
Move from participation to decision-making
Clarify who can raise investment ideas, evaluate opportunities and make allocation decisions. Where capital is pooled, define women’s decision rights—including their role in significant and less liquid investments.
Plan the whole balance sheet
Review investments alongside tax, insurance, liquidity, retirement cash flow, estate documents and planned giving. Ensure that wills, nominations and ownership structures are considered together, with specialist advice where needed.
Earn the next generation’s trust separately
Build a direct relationship with successors before a handover. Understand their objectives, invite their questions and give them the opportunity to assess the advisor relationship for themselves.
Preparing for a family wealth review: Guideline
The report suggests building the successor relationship before the handover. Give the next generation direct access, context and a reason to trust the advice—not simply an inherited advisor. “The transfer that matters, is not of assets, but of the ability to understand, direct and steward them,” the Equirus Wealth report noted.
Preparation tool What it contains Family wealth map Principal assets, ownership structures, liabilities and who is responsible for each decision. Estate-planning review Wills, nominations and holding structures reviewed together with appropriate legal and tax professionals. Decision-rights map Who is informed, consulted, authorised to decide and responsible for execution Successor development plan Learning objectives, participation in reviews, supervised responsibilities, and progress milestones Whole-balance-sheet review Investments considered alongside taxes, insurance, liquidity, cash flow, and planned giving Advisor continuity plan Introductions, shared context and a direct relationship that allows the next generation to make informed choices
Disclaimer: This story is for educational purposes only. The views and recommendations made above are those of individual analysts or broking companies, and not of Mint. We advise investors to check with certified experts before making any investment decisions.