
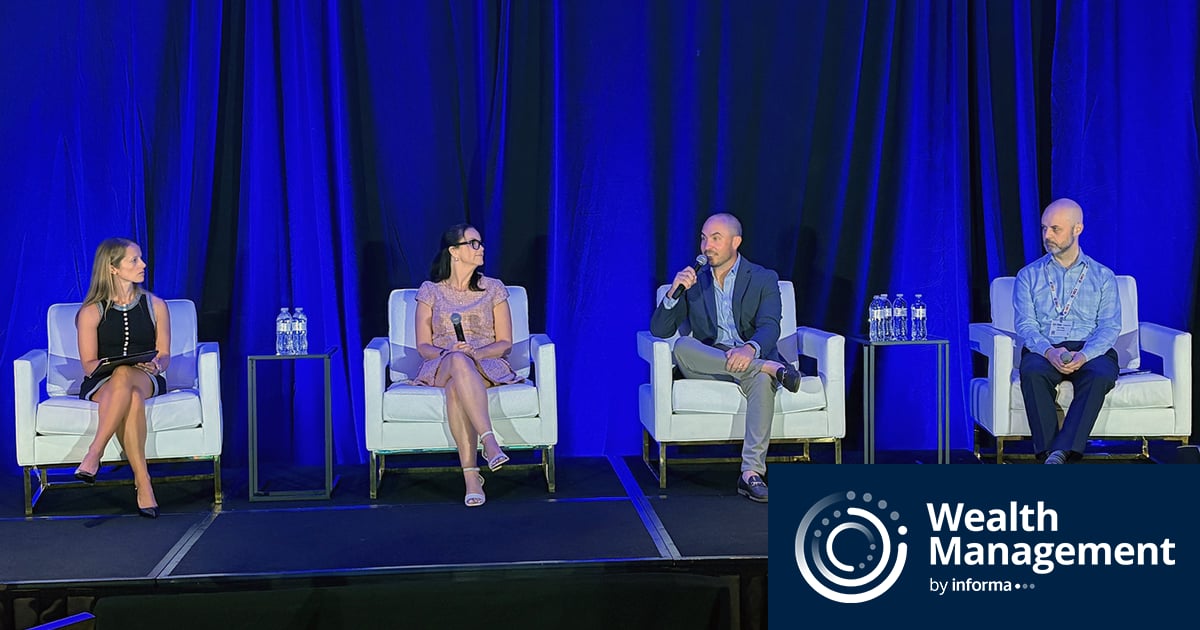
Registered investment advisors have adopted artificial intelligence at a staggering pace over the past couple of years, but most lack a formal business strategy or structure for its use, according to panelists speaking at RIA Edge Orange County on Tuesday.
Recent advisor surveys show that 63% of RIAs are currently using AI, double from back in 2024, but only 1 in 10 firms is using the technology as a fully integrated part of their business strategy, according to moderator Ashley Longabaugh, global head of wealth management at technology consultancy Celent.
“Who is owning the AI, who is building that trust and the governance around it?” Longabaugh asked the RIA audience at the Waldorf Astoria Monarch Beach in Dana Point, Calif. “As AI begins to take action, rather than just give answers, the operating model matters just as much as the technology.”
The panelists said AI use is currently focused on areas such as notetaking, client onboarding and research. But as AI agents become more widely available to work across areas such as customer relationship management, investment management and coaching, firms need to first consider what they seek to accomplish with them.
Tim Foley, head of product and AI at wealth management platform AdvisorEngine, said RIAs should start by considering their goals within their core strategy through the technology, rather than piloting the latest tool.
“Some of these POCs [proof of concepts] are fun and interesting, but they are not going to get you where you need to go,” he said. “Have you thought about how it fits into the existing workflow and how it can meet people where they are?”
Foley described a project in which a firm tested a service chatbot that was not connected to the CRM and service environment it had been operating in, creating inefficiency rather than streamlining.
“In the heat of the moment, if they had a question, they were going to a trusted human chat to get answers rather than to the AI chat,” he said.
Kimberley Raimondo, co-founder and CEO of RIA Brookwood Investment Group, agreed that strategy should lead decisions around AI tools.
“A lot of times we begin with technology in mind, but instead we have to begin with the operational model in mind,” she said. “The key is to really start with what you want the advisor and client experience to be and then work backward…. If you’re not doing that, then you’re just picking technology that is disparate.”
Raimondo, whose RIA has $1.5 billion in assets under management, said she has hired people to lead technology efforts to ensure they are integrated into the broader business plan.
“Failure to launch is a leadership issue; it’s not necessarily a tech issue,” she said. “As leaders, we can pick and choose whatever we want, but if we don’t get to the ‘why’ with our team about its value and why we are using it, it has very little utility.”
Taylor Ciavarra, vice president of Agentic Operations at wealth platform Advisor360, agreed that a firm’s choice of who leads its AI technology effort is crucial to its success. Furthermore, that person doesn’t necessarily need to be an expert in technology.
“They might be the most operationally creative, or they might have great sway internally,” Ciavarra said. “You’ve got to give them the freedom, the latitude, and the agency to pursue how they can make a difference on behalf of the firm.”
Ciavarra also stressed that firms should give AI projects time to work and not abandon them before the impact can be measured.
“When you are using an AI product, I think people are quick to abandon it when they see something that is, well, unintelligent,” he said. “My recommendation from pilot to production is that you have to bear with it so you can actually give it a chance to make a difference.”
RIA CEO Raimondo also mentioned that risk levels vary depending on the AI implementation. A notetaker, for instance, will carry less risk than an AI agent proactively performing tasks, a fact that must be weighed against the overall goals of an RIA.
“The compliance department cannot be the business prevention unit, and the rest of the firm cannot be driving procedures without compliance,” she said. “It’s really important that the two are aligned and that you understand the difference. That is similar to when you are adopting a risk model for the firm, you need to adopt the same risk model for the technology that you are going to be implementing.”