
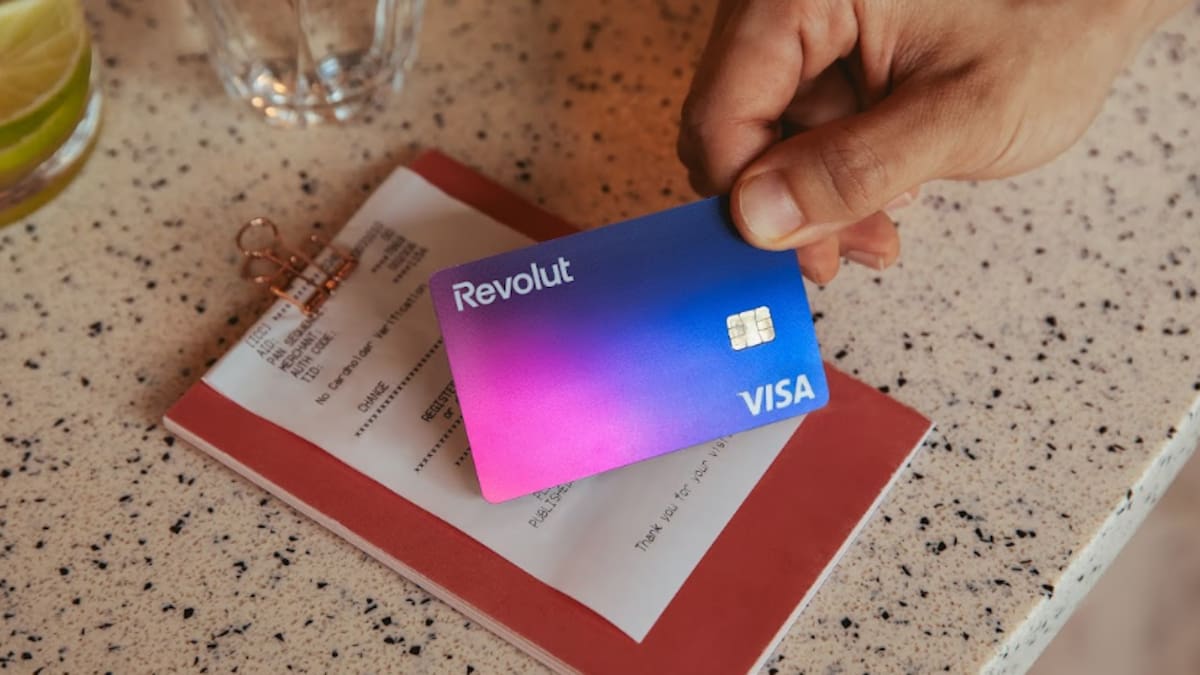
He said it would release a credit card in the coming months, before considering whether to launch other products, like mortgages and KiwiSaver funds.
Having operated in New Zealand since July 2023, Revolut has more than 100,000 mostly personal users.
It offers prepaid Visa debit cards that enable users to switch their money between currencies and shop online using different currencies at low rates.
It also offers travel insurance and various money management and analytical tools for personal and small business users.
Revolut is also an investment platform that gives users access to commodities (gold, silver and platinum) and cryptocurrencies.
Users can opt to use a limited number of products for free or pay monthly subscription fees to access a broader range of offerings.
Brosnahan said the aim of Revolut getting a banking licence was to demonstrate its trustworthiness to help it compete. The idea was for Revolut to eventually be a one-stop money management shop, distinct from traditional banks.
Banks come under much heavier regulation than most other financial services providers, including one of Revolut’s main competitors, Wise.
Revolut had to assure the Reserve Bank it had at least $30 million of capital in New Zealand to begin with, its incorporation and ownership structure was appropriate, and its systems and controls for business risks were adequate.
Revolut will have to continue meeting the Reserve Bank’s capital, liquidity and reporting requirements among other standards, and comply with stricter anti-money laundering rules.
Revolut, which got an Australian banking licence in July, joins a group of 26 other registered banks in New Zealand.
The Industrial and Commercial Bank of China Limited was the last bank to become registered in 2020. Fintech, Dosh, had its application declined last year.
While Revolut employs about 60 people in New Zealand (up from 10 earlier this year) and has offices in Auckland and Wellington, it will continue operating without physical branches.
It has pledged to invest $120m in New Zealand over the next five years.
The variable interest rates Revolut is currently offering on its personal savings accounts range from 2% to 3% per annum depending on the type of subscription users have.
As for business savings accounts, these rates range from 1.25% to 2.25%.
However, to launch its new savings accounts, Revolut is offering to pay 3.5% for four months on balances up to $50,000.
Revolut’s pitch is that interest is paid daily, there are no penalties for making withdrawals and no minimum balance requirements.
Users can also access their savings instantly. However, they will need to transfer their money to their transaction accounts before using it.
Kiwibank similarly has no restrictions on what savers need to do to earn interest on their savings accounts.
The 2% interest Revolut is offering is on par with other banks. Its 3% rate is only available to those who pay $79.99 per month to be on its Ultra plan.
Revolut isn’t, at this stage, offering Portfolio Investment Entity (PIE) funds, which are more tax efficient than regular savings accounts and term deposits.
The company has more than 80 million customers worldwide, and is registered as a bank in six other countries.
Revolut New Zealand guaranteed by UK business
S&P Global Ratings gave Revolut Bank a BBB+ credit rating with a positive outlook.
This rating is weaker than New Zealand’s major banks to reflect Revolut’s “start-up nature”.
It does, however, align with Revolut’s UK-registered company, which is guaranteeing all the New Zealand entity’s liabilities for now.
S&P said the UK entity would have “strong visibility of any impending liquidity issues” experienced by the New Zealand entity, and “would be prepared to facilitate timely payment, if required, under the guarantee”.
It said the Revolut group planned to build its capital buffers over the next two years to help it absorb any losses.
S&P said Revolut would likely grow rapidly in New Zealand off its small base.
It noted the brand had grown in several global markets, using its technological platform to differentiate itself from traditional banks.
S&P expected Revolut to compete on its bank account and credit card offerings. However, it expected the company to remain a small lender in the New Zealand market.
It expected Revolut to continue benefiting from the group’s technology, treasury capabilities, and other shared services.
S&P said it would likely lower Revolut’s credit rating “by multiple categories” if the guarantee provided by its UK entity expired and wasn’t replaced.
On the flip side, it would likely raise the rating if the group enhanced its loss-absorbing capital buffers.
Jenée Tibshraeny is the Herald’s Wellington business editor, based in the parliamentary press gallery. She specialises in government and Reserve Bank policymaking, economics and banking.
Stay ahead with the latest market moves, corporate updates, and economic insights by subscribing to our Business newsletter – your essential weekly round-up of all the business news you need.