
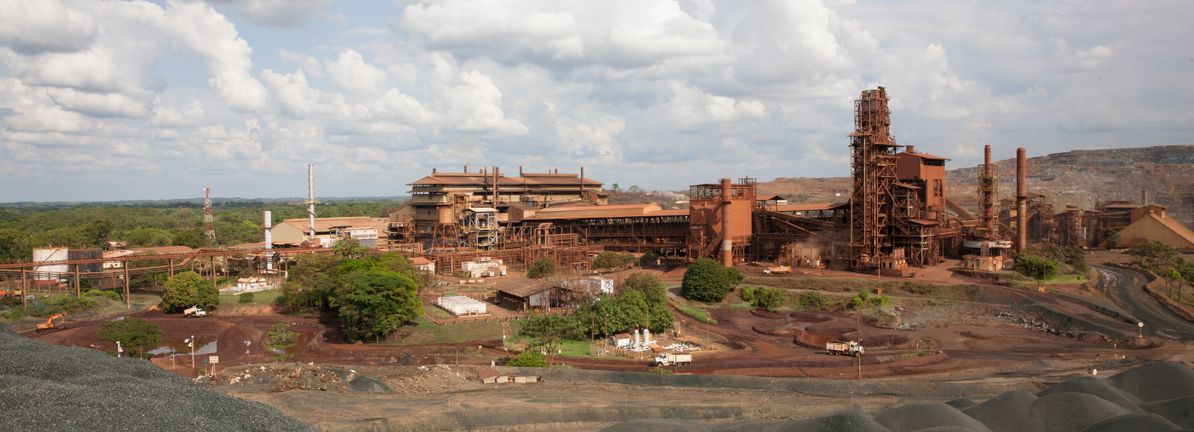
Recently, South32 offered Japanese buyers record-high premiums for third-quarter aluminum shipments, reportedly more than US$100 per ton above its prior quarter deals, as supply tightened following conflict-related disruptions in the Middle East. This sharp premium increase at the key Main Japanese Port benchmark underscores how regional supply constraints can rapidly shift pricing power for aluminum producers serving East Asia. We’ll now examine how South32’s record Japan aluminum premiums, amid tighter supply conditions, may influence the company’s broader investment narrative.
Find 8 companies with promising cash flow potential yet trading below their fair value.
South32 Investment Narrative Recap
To own South32, you need to believe in its role as a diversified producer of aluminum, base metals and manganese that are central to industrial supply chains and the energy transition. The recent record Japan aluminum premiums highlight how regional supply tightness can briefly lift pricing, but they do not remove the near term dependence on reliable, affordable power for Hillside and Mozal or the execution risk in large growth projects such as Hermosa.
The company’s April 2026 update on the Taylor project at Hermosa, which extended ore body life to around 33 years and lifted reserves and resources, is particularly relevant here. It underlines how South32 is trying to rebalance toward higher margin base metals even as short term aluminum pricing swings grab headlines, making project delivery, capital discipline and future cash generation key catalysts to watch beside the current aluminum premium spike.
Yet, while higher Japanese premiums may look reassuring, investors should be aware of how exposed South32 remains to power contract uncertainty at…
Read the full narrative on South32 (it’s free!)
South32’s narrative projects $6.8 billion revenue and $1.2 billion earnings by 2029. This requires 4.9% yearly revenue growth and an earnings increase of about $800 million from $394.0 million today.
Uncover how South32’s forecasts yield a A$4.63 fair value, a 4% downside to its current price.
Exploring Other Perspectives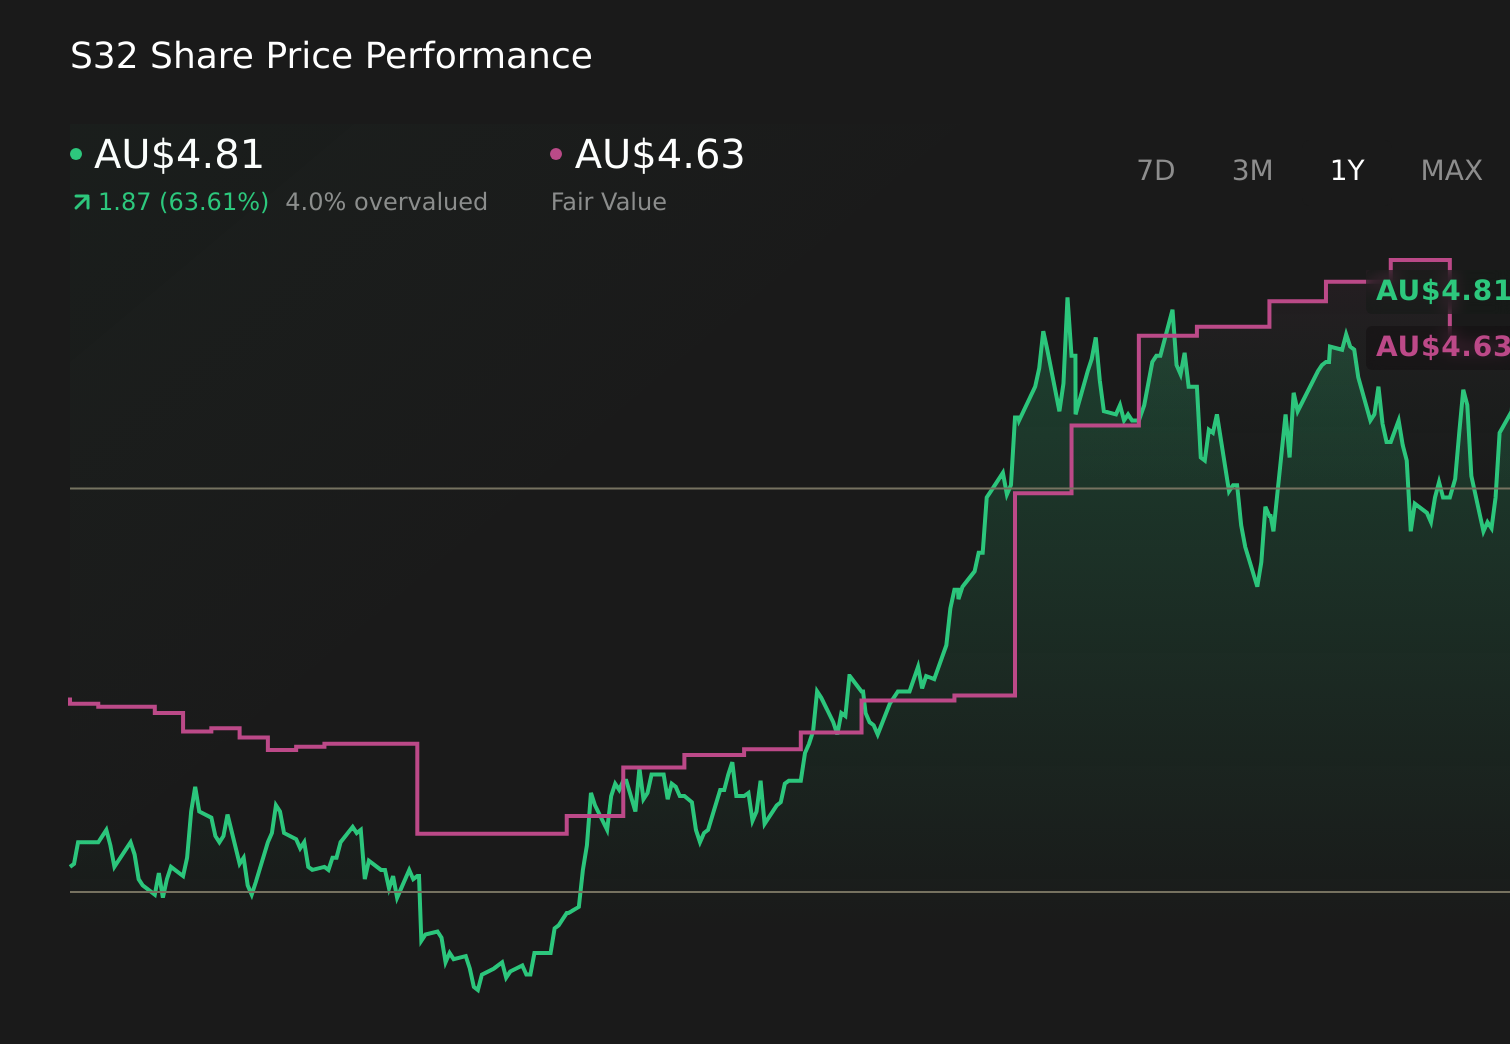 ASX:S32 1-Year Stock Price Chart
Before this premium spike, the most optimistic analysts were assuming revenue could reach about US$9.0 billion and earnings US$1.4 billion, so compared with consensus they were painting a far more optimistic picture of South32’s upside even as they flagged power and project execution risks that this latest aluminum pricing surprise might eventually force you to reassess.
Explore 5 other fair value estimates on South32 – why the stock might be worth 41% less than the current price!
Form Your Own Verdict
Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.
Curious About Other Options?
Early movers are already taking notice. See the stocks they’re targeting before they’ve flown the coop:
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com