
Dar es Salaam. Despite the rapid expansion of financial services in Tanzania, two out of every three Tanzanians still face difficulties managing their day-to-day expenses, highlighting a gap between access to financial services and the ability to use them effectively.
The challenge has prompted efforts to integrate financial literacy into higher education, technical education and vocational training to equip young people with skills to manage income, expenditure, savings, debt and investments before they enter the workforce.
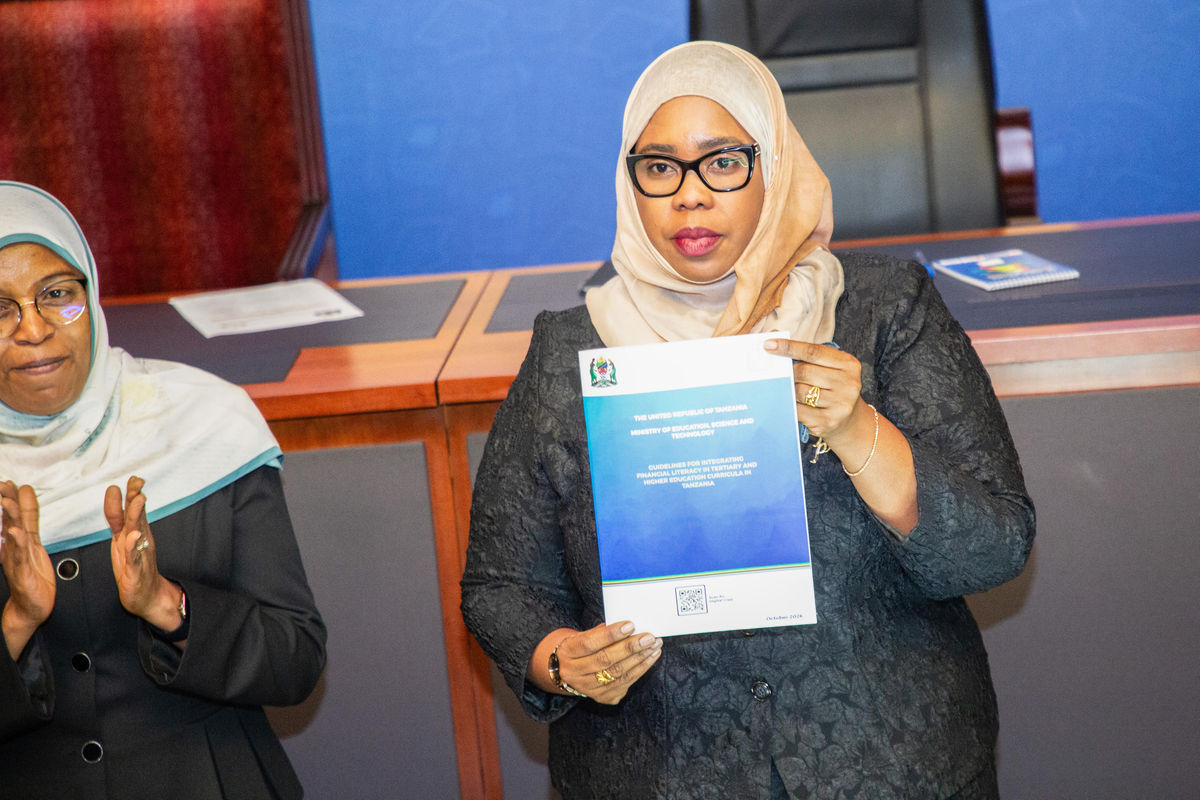
The issue was highlighted yesterday, October 2, 2026, during the launch of a guideline for integrating financial literacy into the curricula of higher education, technical education and vocational training.
Speaking at the launch, Bank of Tanzania (BoT) Director of Financial Inclusion and Development Services Kennedy Komba said access to financial services had increased significantly, from 11 percent in 2006 to 76 percent in 2023.
However, he said greater access had not necessarily translated into the ability of citizens to make sound financial decisions.
The 2023 FinScope Survey shows that two out of every three Tanzanians faced challenges in managing their day-to-day expenses.
“Financial literacy is not only about increasing knowledge, but also about enabling households and individuals to plan their expenditure, save, manage debt, withstand financial shocks and make decisions that protect their well-being,” Mr Komba said.
He said access to financial products alone was not enough if users did not understand the costs, risks and obligations associated with them.
“Accessing a loan is not the same as understanding the interest rate, costs, terms and repayment capacity. Having investment opportunities is not the same as being able to assess the returns, risks and legitimacy of an investment,” he said.
Mr Komba said the gap was becoming more important as technology increasingly allowed people to borrow, save and conduct transactions through mobile phones without visiting financial institutions.
“In such an environment, financial literacy aims to help people understand not only how to access services, but also their costs, potential risks and how to use money in line with their financial capacity,” he said.
He said the new guideline was being introduced in higher education institutions because students already faced financial decisions involving education loans, accommodation and daily expenses.
Some students, he added, were also engaged in businesses and other income-generating activities.
“After graduation, they encounter other responsibilities involving salaries, loans, investments, savings and the use of financial services. Therefore, the guideline aims to ensure that knowledge of financial management does not depend on experience that a young person gains only after encountering challenges, but instead begins to be developed while they are still within the education system,” Mr Komba said.
BoT Deputy Governor Sauda Msemo said financial literacy was a foundation for building a strong, safe and inclusive financial system, particularly as technological advances continued to introduce a wider range of financial products.
She said the products could not deliver their intended benefits unless users understood how they worked.
“The new guideline aims to complete that chain by bringing financial literacy into higher and technical education, where young people are preparing to use their skills in employment, business and other productive activities,” Ms Msemo said.
Deputy Minister for Education, Science and Technology Wanu Hafidhi Ameir said the guideline was in line with the National Development Vision 2050, which seeks to build a competitive and productive economy supported by a skilled workforce.
She said Tanzania needed graduates who were not only holders of academic certificates but also capable of applying their knowledge to address challenges facing society and contribute to national development.
“Education institutions should ensure that students are equipped with the ability to plan and manage income and expenditure, save, borrow responsibly, understand investment opportunities and risks, identify financial fraud and protect their personal information,” she said.