
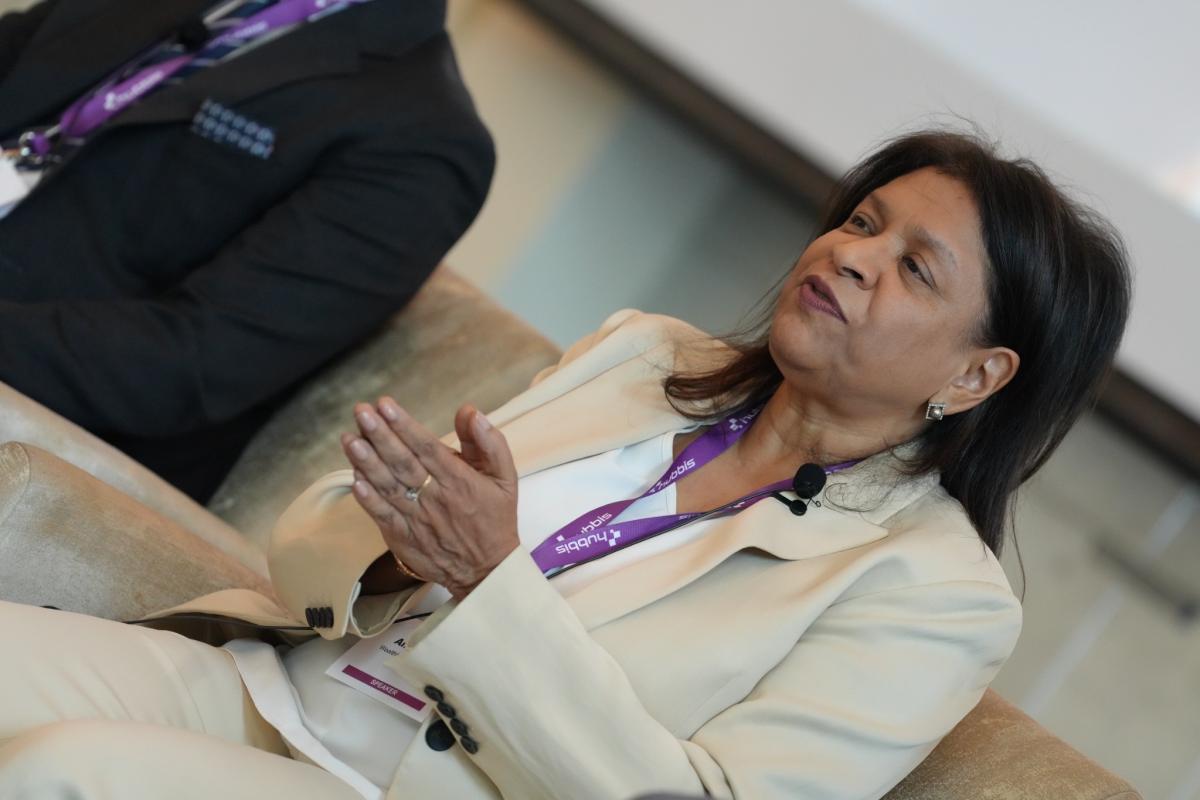
For independent wealth management firms operating in the Gulf without the balance sheet or branch network of a regional bank, the question of how to compete is a practical one. Anita Gupta, Chief Investment Officer at Wealthbrix Capital Partners, addressed that question directly at the recent Middle East Private Capital Forum 2026, drawing on her experience of moving from a large regional banking institution to a smaller, dedicated wealth management firm in the DIFC.
The panel, hosted by Hubbis at the Shangri-La Dubai and chaired by Damian Hitchen, Chief Executive Officer for MENA at Saxo, explored the strategic forces reshaping the region’s private wealth landscape, from the growing influence of AI on client behaviour to the structural challenge of building differentiated investment propositions in an era of converging product platforms. Gupta’s contribution focused on the operational realities of operating within a smaller, independent wealth management firm, and on the generational shift she has observed in client behaviour over the past five years.
Key Takeaways
The core disciplines of wealth management remain consistent across firm size, with risk profiling, capital preservation and asset allocation following similar frameworks regardless of whether the platform sits within a large bank or an independent firm.
Smaller firms trade balance sheet depth for operational focus, with fewer administrative layers and potentially fewer legacy constraints on product selection.
The generational wealth transfer is already visible in client meetings, with clients in their fifties to seventies bringing their children into portfolio discussions and those children increasingly managing their own allocations.
Next-generation clients are seeking greater exposure to private equity, private credit and direct investment opportunities, including pre-IPO allocations, while still maintaining an emphasis on capital preservation.
Younger investors ask about technology and AI capability but do not want a robo-advisory model, according to Gupta.
Similarities and Differences Across Scale
Gupta described her move from a major regional bank to Wealthbrix Capital Partners as one that revealed both continuities and contrasts. On the advisory fundamentals, she said, the approach is broadly the same. The way a firm assesses client risk appetite, structures portfolios around capital preservation and builds asset allocation models ranging from conservative to more aggressive profiles follows similar principles regardless of institutional scale.
“We are looking at clients in a very similar way,” Gupta said. Setting up product lines and risk profiles, she added, is “very much the same” at a smaller firm as it is at a larger one.
The differences, Gupta explained, are structural. A large bank benefits from multiple sources of income and, in the case of a regional institution, from branches across several markets. “We are just a pure wealth management firm,” she said. A smaller enterprise does not have a large balance sheet to fall back on, and it lacks the geographic distribution that a banking group can draw upon.
But Gupta identified corresponding advantages. Without the administrative burden and legacy product relationships that accumulate within a larger institution, a smaller firm can direct more of its attention towards clients. “In a smaller enterprise, you can be more focused. You can be more client focused,” she said. “You don’t have all the administrative tasks that you have on the outside.”
That freedom, Gupta said, extends to product selection. She noted that large banks often carry legacy commitments that shape the products they offer. A firm making a fresh start faces no such constraints. “If you’re a large bank, it comes to a lot of legacy,” she said. “When we can make a fresh start, you’re able to give your clients what you think is best suited for them.” She described this as a best-of-breed approach, one in which the firm selects solutions on merit rather than defaulting to existing arrangements.
A Generational Shift Already Under Way
Gupta described a change in client demographics that she has observed over more than five years in the region. Historically, she said, the primary holders of wealth management relationships tended to be individuals aged fifty and above. That profile has shifted.
“Today we are seeing a lot of clients who are like in the 50 to 70, and they’re also bringing in their children along with them,” Gupta said. In many cases, she noted, those children are already running businesses or operating independently, but the parents want them involved in the investment process and aware of the family’s financial position.
“They want their children to be cognisant of where the portfolio is,” she said. What has changed more recently is that those children are no longer simply observing. They are now running their own portfolios alongside the family’s legacy holdings, and their investment preferences differ from those of the older generation.
Different Appetites, Different Questions
Gupta identified two principal differences between the generations. The first is willingness to take risk and interest in new investment opportunities. While capital preservation remains a shared priority across both cohorts, the younger generation is willing to take more risk and is drawn to asset classes and sectors that the older generation has typically been less engaged with.
“The younger generation is definitely looking at more private equity opportunities, private credit,” Gupta said. “They are more on the technology side. They are definitely more cognisant of the newer industries.” She added that younger clients are actively seeking direct investment opportunities, including what she described as Silicon Valley pre-IPOs, and are willing to accept the risk that comes with them. “They’re willing to take that risk, and they say, do you offer that?” she reported.
The question itself is telling. It suggests that next-generation clients arrive at meetings with specific expectations about the range of opportunities a firm should be able to provide, and that firms which cannot answer that question credibly may struggle to retain the attention of the emerging client base.
The second difference relates to technology. Gupta said that younger clients consistently ask about the firm’s use of technology and AI in the investment process. “They also always ask, what is the tech overlay? Are you using AI?” she said. However, she drew a clear distinction between that expectation and a desire for full automation. “They don’t want a robo-advising platform,” she said. A participant on the panel observed separately that robo-advisory models have been available for some time without displacing human-led advice, noting that clients continue to value the expertise and judgement that a human adviser provides.
Gupta summarised the generational shift in direct terms. “These are the two changes that we have seen,” she said. “The younger generation is definitely willing to take more risk, and secondly, they will look at more exciting investment opportunities.”
A Platform Built on Focus
Gupta’s account described a firm that competes not through scale or brand recognition but through focus, product selectivity and the absence of institutional legacy. Whether that model proves durable as competition in the Gulf’s wealth management market intensifies remains to be seen, but her remarks offered a clear account of how one independent firm is positioning itself, and of the client-driven shifts that are shaping that positioning in practice.