Matt Goodson, managing director of Salt Funds Management, said there had been a general backdrop of data-centre and neocloud stocks being hard hit.
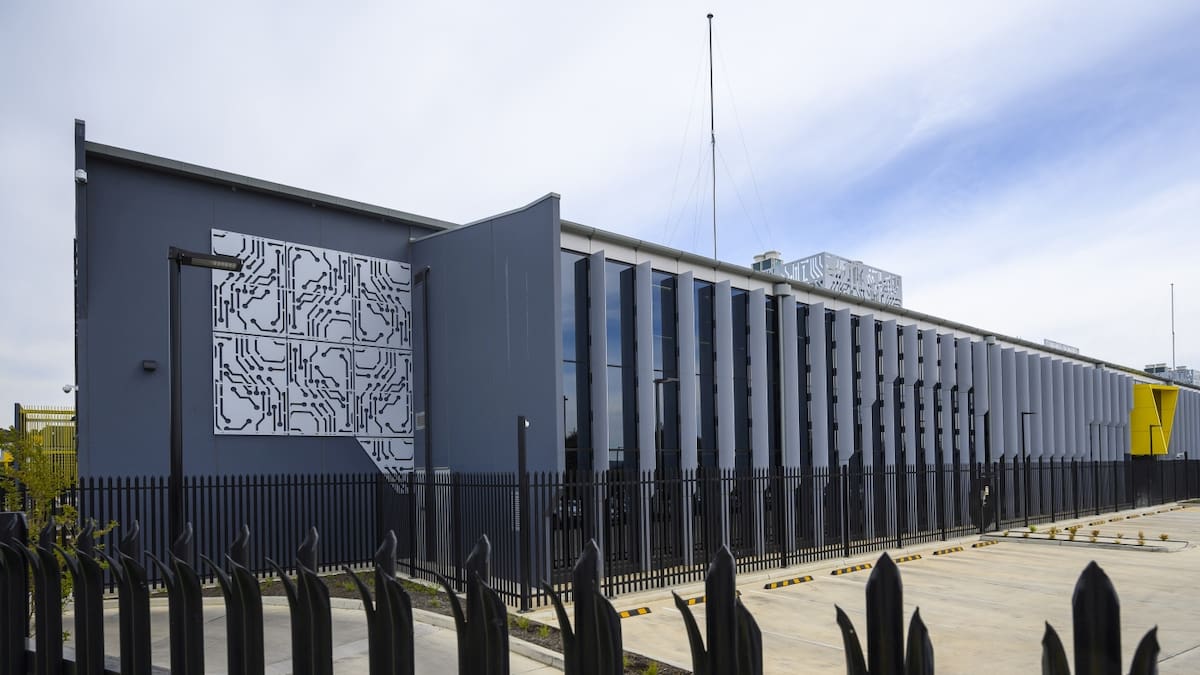
He said Australian data-centre operator NextDC went into a trading halt because of the difficulty of confirming power to its new M3 centre in Melbourne.
“Investors were asking: is it merely a delay, is it the price, or will the client walk away – I understand it’s one of the hyperscalers.”
Nscale was seeking to list in the US at full valuation and Microsoft has walked away from the partnership amid delays in securing power.
Goodson said the data-centre sector had suddenly been in the sin bin in the last few days and this led to questions about the growth outlook for the sector.
“There’s been nothing specific involving Infratil, and CDC is in a better position than most with very long contracts with hyperscalers. And they tend to build centres in industrial sites and not near residential areas,” he said.
Across the Tasman, the S&P/ASX 200 Index was up 0.31% to 8834.4 points at 6pm NZ time, and further afield the Japanese Nikkei 225 was down 0.65%, the South Korean Kospi bounced back to a gain of 0.55%, and the Hong Kong Hang Seng Index was up 0.52%.
The US Philadelphia Semiconductor Index fell for an eighth consecutive session over the weekend, its longest losing streak since 2008. The sustained weakness in US chip stocks has put pressure on Asian semiconductor companies and related businesses, one commentator said.
Local stocks
Back home, ASB is forecasting a 0.8% increase in the September Consumers Price Index (CPI), to be released on Thursday, and an annual inflation rate of 3.9%.
The major contributors are expected to be sizeable increases in local authority rates, airfares, a “stirring” in construction costs and higher food prices. But there would be sharp falls for vehicle fuels and annual dwelling rental inflation at around record lows, ASB said.
“It’s looking ahead to the fourth quarter – we now expect 4.5% year-on-year inflation – which has us unnerved and increasingly concerned around the upside risks to inflation and the official cash rate outlook (OCR).
“At this current juncture, the risks are meaningfully skewed to an OCR above 3.25% in 2027.”
ANZ is expecting the inflation rate to slow to 3.8% (from 4.1%) – “a touch stronger than our previous forecast of 3.7%, but weaker than the September monetary policy statement forecast of 3.9%”.
“The lower NZ dollar and higher oil prices since September have materially changed the outlook. In our view, that keeps an October OCR hike firmly on the table,” ANZ said.
Brent Crude oil was trading at US$107.8 a barrel after falling from nearly $110 on Friday and the oil is still testing the high of $114 in early May.
At home, Mainfreight declined $1.69 or 2.47% to $66.69; Meridian Energy decreased 8c to $5.51; Ebos shed 47c or 2.3% to $19.93; and Chorus dropped 25c or 3.05% to $7.96.
Goodson said there was broker concern that the Commerce Commission might lower the rate of return for Chorus in the next 2029 regulatory period.
Colonial Motor was down 20c or 2.72% to $7.15; Eroad fell 3.5c or 3.43% to 98.5c; Napier Port decreased 7c or 1.9% to $3.62; and Metro Performance Glass shed 1.5c or 1.78% to 83c.
In the property sector, Stride was up 2c or 1.9% to $1.07, and Kiwi was down 1.5c to 90c.
Fisher & Paykel Healthcare gained 18c to $48.79; Freightways was up 22c to $12.38; and Fonterra Co-operative increased 13c or 2.4% to $5.55.
Hallenstein Glasson hit a new high after gaining 16c to $15.28; a2 Milk added 11c to $8.50; T&G Global increased 6c or 2.73% to $2.26; and Winton Land was up 2c or 1.75% to $1.16.
The dual-listed banking groups had a strong day, with ANZ up 81c or 1.7% to $48.59, and Westpac adding 74c or 1.71% to $44.12.
Stay ahead with the latest market moves, corporate updates, and economic insights by subscribing to our Business newsletter – your essential weekly round-up of all the business news you need.