
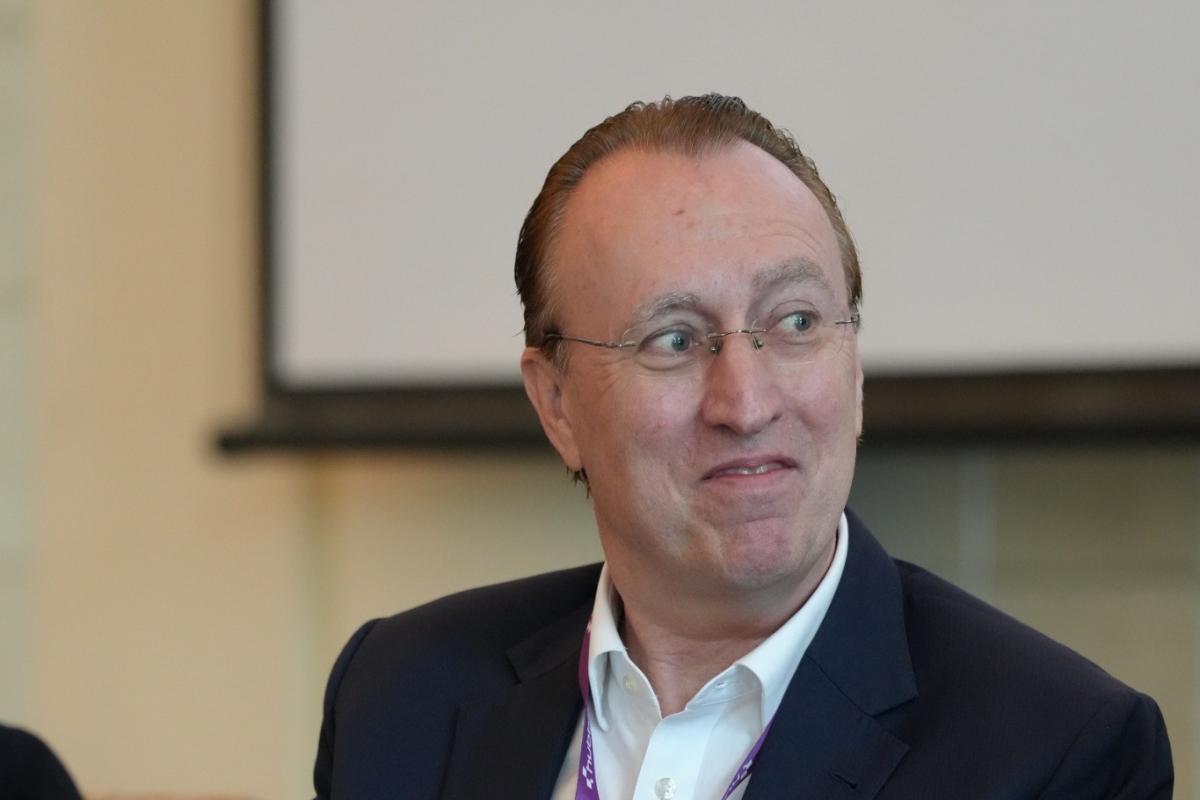
The role of a chief investment officer demands expertise across every asset class and every market development at any given moment. Gary Dugan, Chief Executive Officer of The Global CIO Office, told the recent Middle East Private Capital Forum 2026 that AI has brought him closer to meeting that standard than at any previous point in his career, while cautioning that the technology creates new obligations around verification, trust and regulatory accountability that the industry has not yet fully resolved.
The panel, hosted by Hubbis at the Shangri-La Dubai and chaired by Michael Stanhope, Founder and Chief Executive Officer of Hubbis, examined how private wealth firms in the Gulf are deploying AI in practice. Dugan’s contribution drew on his experience running an outsourced CIO services business to describe how AI is changing the speed and breadth of investment research, why the human element remains essential to client relationships, and where regulatory scrutiny is likely to intensify.
Key Takeaways
AI has expanded the range of topics a CIO can engage with meaningfully, according to Dugan, replacing the slower process of working through individual sources with rapid, curated access to perspectives on unfamiliar developments.
The technology functions as a research accelerator rather than a decision-maker, with Dugan describing it as “a super library” whose output must still be checked and interrogated by an experienced professional.
Client trust depends on the adviser not simply relaying machine output, and reading the emotional dynamics of a meeting remains something AI cannot replicate.
Verification of AI-generated content is not optional, with Dugan warning that numerical errors and unchecked conclusions represent a tangible risk in everyday use.
Regulatory attention is likely to focus on data security, input quality and due diligence processes, with Dugan predicting a significant compliance burden as AI becomes embedded in advisory workflows.
A Super Library, Not a Replacement
Dugan framed AI’s value in terms that were practical rather than transformational. As someone running an outsourced CIO business, the breadth of knowledge required on any given day is substantial. Before AI, keeping pace meant working through Bloomberg terminals, newspapers and online resources one by one. That approach, he said, was “not the right answer.”
AI has changed the economics of that process. “Probably for the first time in my career, I can be” a genuine generalist, Dugan said, “because the AI is enabling you to go on top of the topic that can be moving around. It’s becoming noisy, and you can get a perspective very quickly.”
His characterisation of the technology was measured. “I just see it as a super library that’s been well curated to give you the answers, and then I have to go in there and check that the answer is valid,” he said.
That checking, Dugan made clear, is not a formality. He noted that AI-generated content tends to adopt a generic tone that strips out the personality and judgement an adviser is expected to bring. “It will go and tie in an AI voice, and you have to go back there and put your personality back in there,” he said. “That’s the one old world thing that I’m still doing.”
When asked how AI has improved the quality of his own output, Dugan pointed to the speed at which supporting material can now be assembled. “When I’m writing some kind of paper on something I’m interested in, absolutely data points and absolutely often, what are the kind of professors out there saying about this at the moment. I can get all that to my desktop in 10 minutes,” he said. Previously, that process would have required searching through individual sources or visiting a library. “The amount of information that gets distilled is definitely going to improve the quality, I think, of the analysis and hopefully of the decision and the guidance that you’re giving by using it,” he said.
Trust and the Limits of Listening
When the discussion turned to whether clients might trust an adviser less if they perceive that AI is doing much of the work, Dugan’s response centred on the elements of client engagement that technology cannot capture.
“You sit down with a client in a room, and the way that person interacts with you may be very different from the last conversation you had,” he said. “You understand the mood. You understand what worries them, but they can’t articulate it.” AI, he argued, can process the words a client uses but cannot register the emotional dynamics of a meeting. “If AI is just, in a sense, talking to your client and just hearing the words, wanting the emotional thing and sitting with the client, that is very, very important,” he said.
The trust question, in Dugan’s framing, is not about whether AI is used, but about whether the adviser is adding something beyond what the machine produces. “How do we keep the trust in this and the trust in ourselves that we’re not just regurgitating a machine output,” he said. The answer, he argued, lies in what the adviser brings to the process: personality, experience and the willingness to interrogate what AI returns rather than accepting it at face value.
“That’s the kind of the input you put in, which is obviously your personality, your experiences, interrogating AI to come back with an answer,” he said.
The Obligation to Check
Dugan was candid about the temptation to use AI output without adequate review. He acknowledged that the speed of the technology makes it easy to take a generated response and send it directly to a client. But he was explicit that doing so carries real risk.
“You really do need to read it,” he said. “I know it’s just sometimes very rustic. I’m just going to put it out, send it through an email. But you need to read it.” He gave a specific example of the kind of error that can slip through. “You need to ensure that the number in there that says above 12 is probably right, and not one that says 37,” he said. “These are the things that have got to get checked through.”
His assessment of where the industry stands on this was direct. “I don’t think we’ve got to a point where we don’t, we have to stop checking,” he said. The implication was that human review of AI-generated material is not a transitional requirement but an ongoing necessity, at least for the foreseeable future.
A Regulatory Burden in the Making
Dugan offered the panel’s most detailed comments on the regulatory dimension of AI adoption. He predicted that regulatory attention will coalesce around three areas: data security, the quality of inputs used to generate advice and the rigour of AI-assisted due diligence processes.
“I think it’s going to be about data security. I think it’s going to be about the inputs that we’re taking and where we’re getting them from,” he said. “There’s actually probably a pending big burden on the industry.”
He raised concerns about the potential misuse of AI in gathering information about individuals, noting the risk that firms might rely on AI-sourced profiles without adequate verification. “God forbid that people think they could just take a picture of someone and get the download on the individual,” he said.
Dugan described using AI to generate preliminary due diligence questions from lengthy investment documents, while emphasising that such analysis requires independent human review.
His conclusion was framed as a statement of professional accountability. “You’ve got to take ownership of the output,” he said. The phrase captured a broader principle that ran through his remarks: AI can accelerate and broaden the work an adviser does, but it does not transfer the responsibility for the result.