
Tech continued to lead stocks down last week, as it had all month. Of the 11 sectors, all but information technology and communications services were up last week – the latter two were down 1.8% and 8.5%, respectively. Those are also the only two sectors that closed the month down.
Fundstrat Head of Research Tom Lee sees the long-term thesis for the AI trade as intact, and the main macroeconomic event this week supports a near-term constructive view on tech for him as well. We’re speaking here of the Federal Open Market Committee meeting that ended on Wednesday afternoon.
The FOMC rates kept steady as most expected, nudging more attention toward the post-meeting press conference. Federal Reserve Chair Kevin Warsh once again reiterated the central bank’s commitment to achieving 2% inflation – and specifically not just “some inflation target somewhere in the twos” like 2.1%. Yet there was a less hawkish (or, using a different semantic approach, more dovish) angle to his remarks. For example, though he stressed that it was too soon to reach a “firm conclusion,” he spoke of being “encouraged by the progress we’ve made in a short period of time” on the Fed’s inflation mandate, and he mentioned the committee’s view that actions taken thus far “are starting to work some.”
Fundstrat Head of Research Tom Lee highlighted Warsh’s response to a question about the possibility that AI-driven demand growth was adding to inflation: “Is the economy running too hot? […] That isn’t the judgment of most of my colleagues. My judgment is we’ve seen an improvement in productivity.”
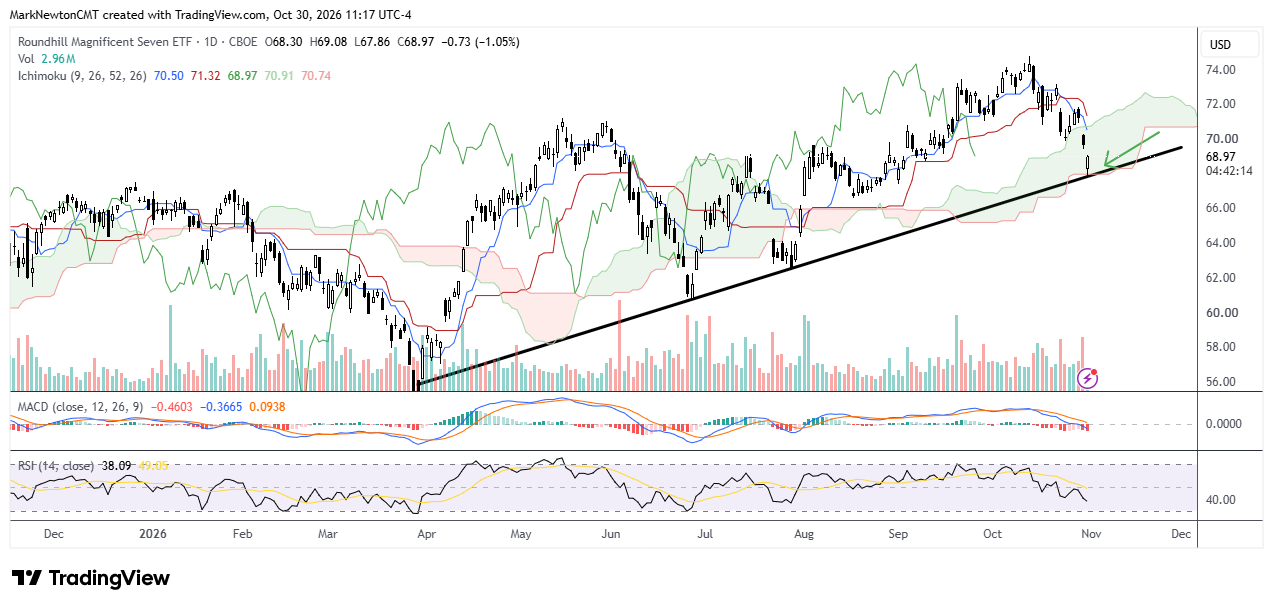
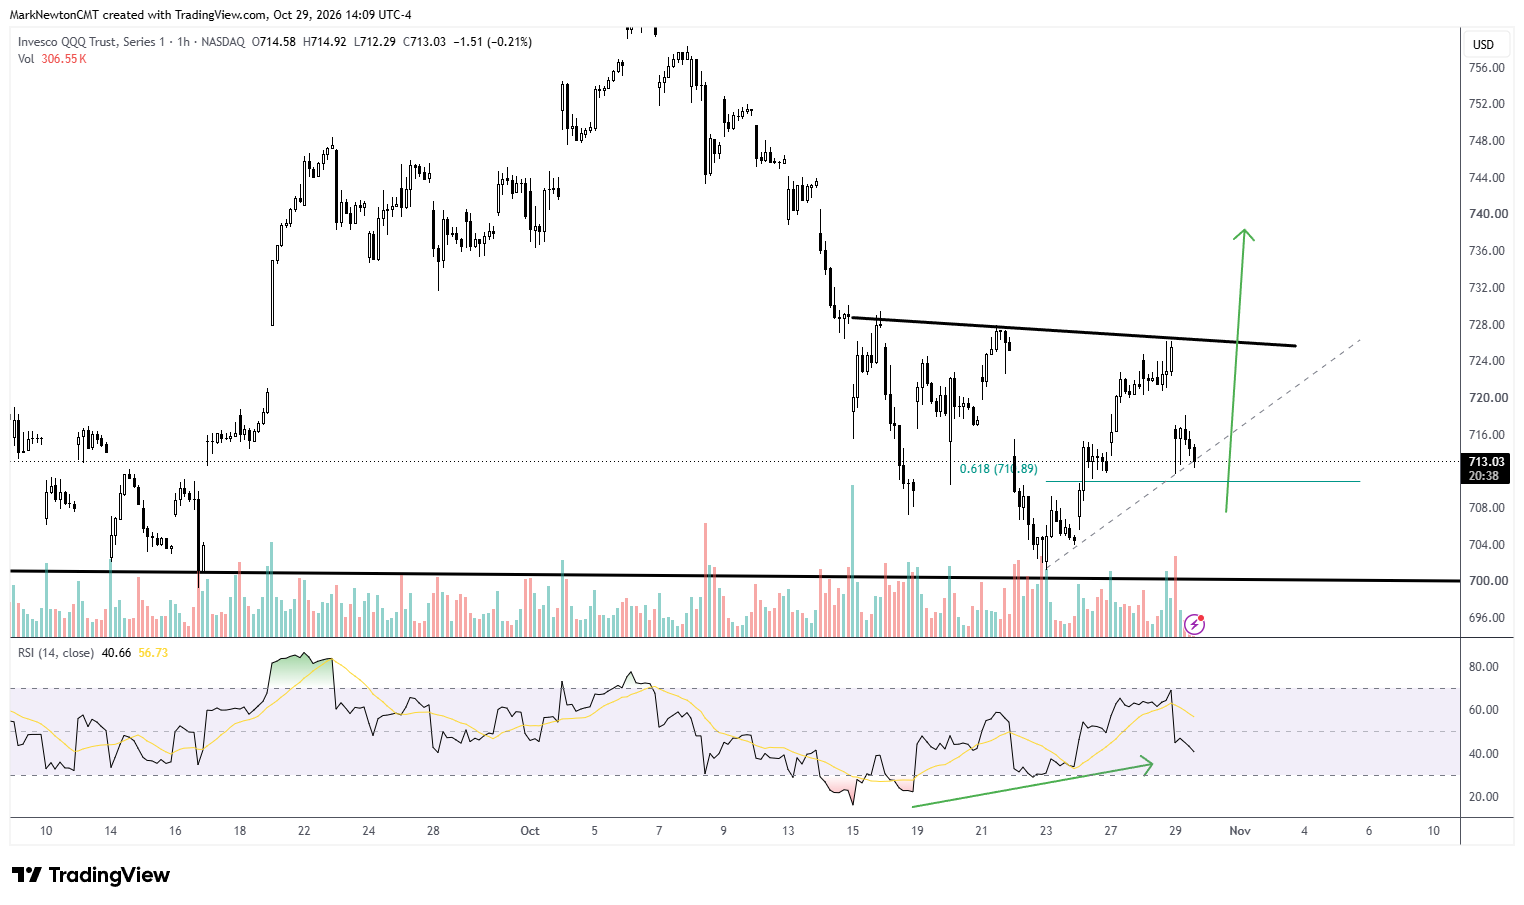
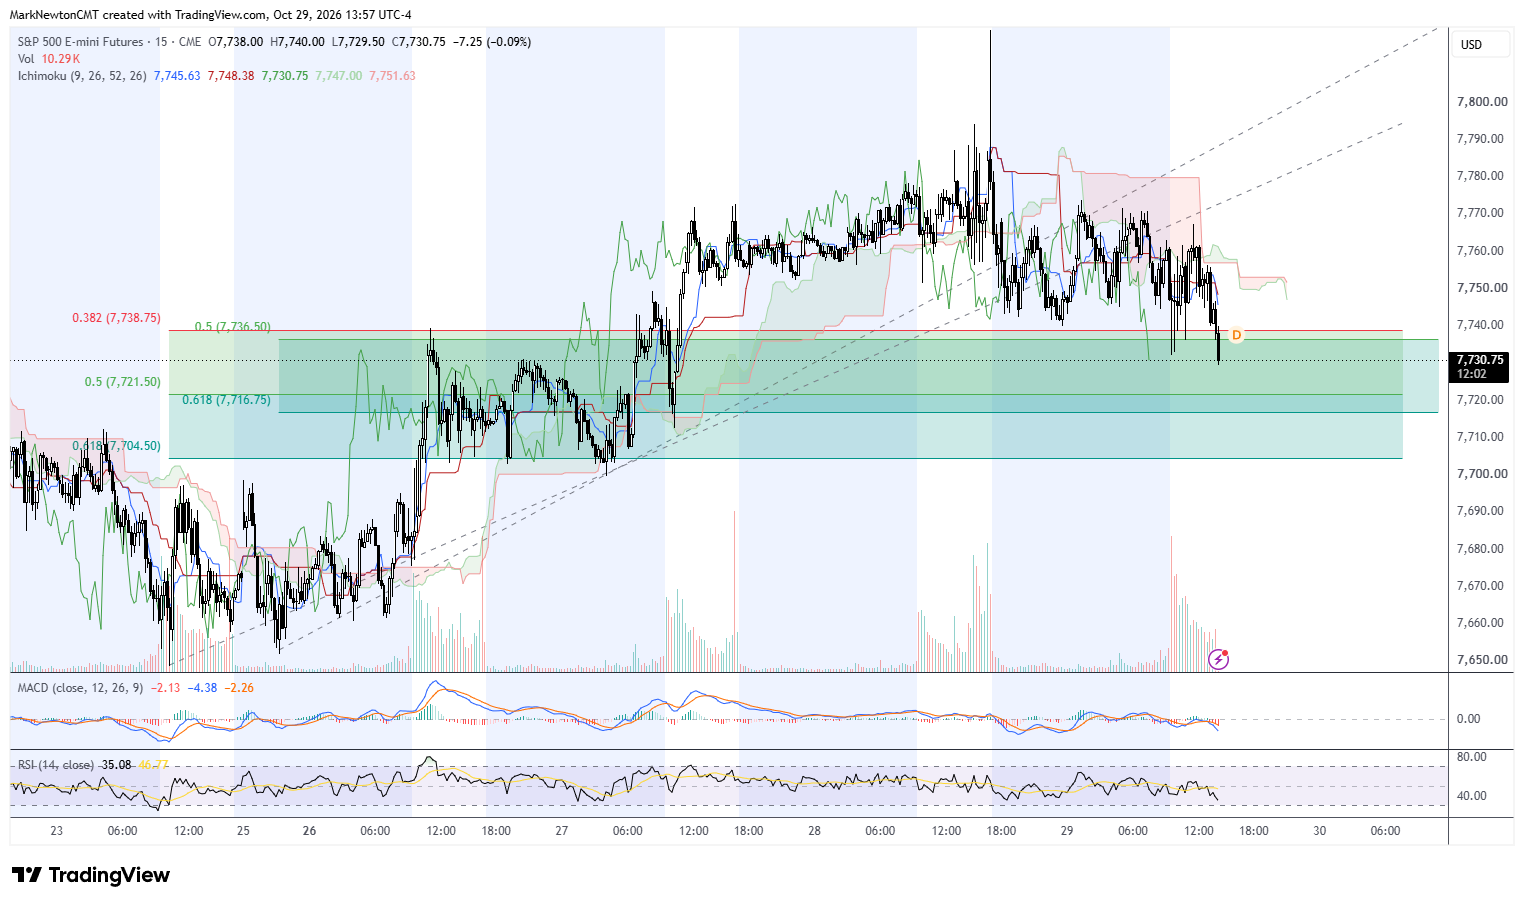
The recent weeks of tech declines have dragged the broader indices lower, making it feel like this might be a bear market. But is it?
That’s a question that was put to Head of Technical Strategy Mark Newton during our weekly research huddle. Here’s his response: “Is this a bear market? The key takeaway for me is that the stock market honestly is in much better shape than what many expect and how it has felt recently. The broader market has really begun to rally, and I think that is sort of the key. In the last month you’ve seen tremendous gains out of almost every sector.”
One remaining source of uncertainty will likely be resolved next week, as the midterm elections decide which party controls the two chambers of Congress. Yet historical precedent suggests that while control of Congress certainly matters for the U.S. and the rest of the world in many ways, matters less for investors. “We looked at the stats since 1950 regarding midterm elections, and in 19 of 19 cases markets were higher by an average of 15% six months after the midterms.”
Chart of the Week
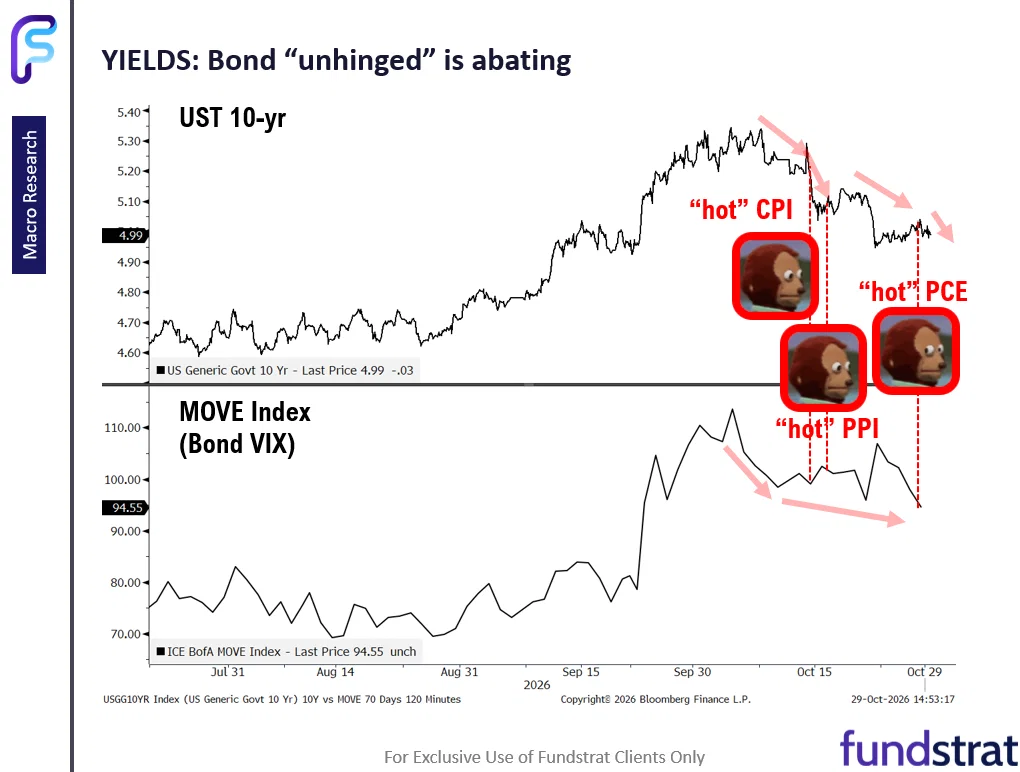
It could be argued that markets saw last week’s FOMC meeting as less hawkish or more dovish. Two-year yields, generally seen as the market’s view of where Fed policy is headed, retreated from their weekly highs on Wednesday around 4.78% to about 4.59% at Friday close. Also supporting this argument are a concurrent retreat in the 10-year yield and the MOVE Index (a measure of bond-market volatility), as seen in our Chart of the Week.
Recent ⚡ FlashInsights
Fundstrat Direct Video: Weekly Highlight
Key incoming data
10/26 8:30 AM ET: Sep Chicago Fed Nat Activity Index Tame
10/26 10:30 AM ET: Oct Dallas Fed Manuf. Activity Survey Tame
10/27 8:30 AM ET: Sep P Durable Goods Orders Tame
10/27 9:00 AM ET: Aug S&P Cotality CS 20-City MoM SA Tame
10/27 10:00 AM ET: Sep New Home Sales Tame
10/27 10:00 AM ET: Oct Richmond Fed Manufacturing Survey Tame
10/27 10:00 AM ET: Oct Conference Board Consumer Confidence Tame
10/28 2:00 PM ET: Oct FOMC Decision Dovish
10/29 8:30 AM ET: 3Q A GDP Tame
10/29 8:30 AM ET: Sep PCE Deflator Tame
10/30 8:30 AM ET: 3Q Employment Cost Index Tame
11/2 Mon 9:45 AM ET: Oct F S&P Global Manufacturing PMI
11/2 Mon 10:00 AM ET: Oct ISM Manufacturing PMI
11/3 Tue 10:00 AM ET: Sep JOLTS Job Openings
11/3 Tue 10:00 AM ET: Sep F Durable Goods Orders MoM
11/3 Tue: US Midterm Election
11/4 Wed 8:30 AM ET: Sep Trade Balance
11/4 Wed 9:45 AM ET: Oct F S&P Global Services PMI
11/4 Wed 10:00 AM ET: Oct ISM Services PMI
11/5 Thu 8:30 AM ET: 3Q P Nonfarm Productivity QoQ
11/5 Thu 8:30 AM ET: 3Q P Unit Labor Costs
11/6 Fri 8:30 AM ET: Oct Non-farm Payrolls
11/6 Fri 10:00 AM ET: Nov P U. Mich. 1yr Inf Exp
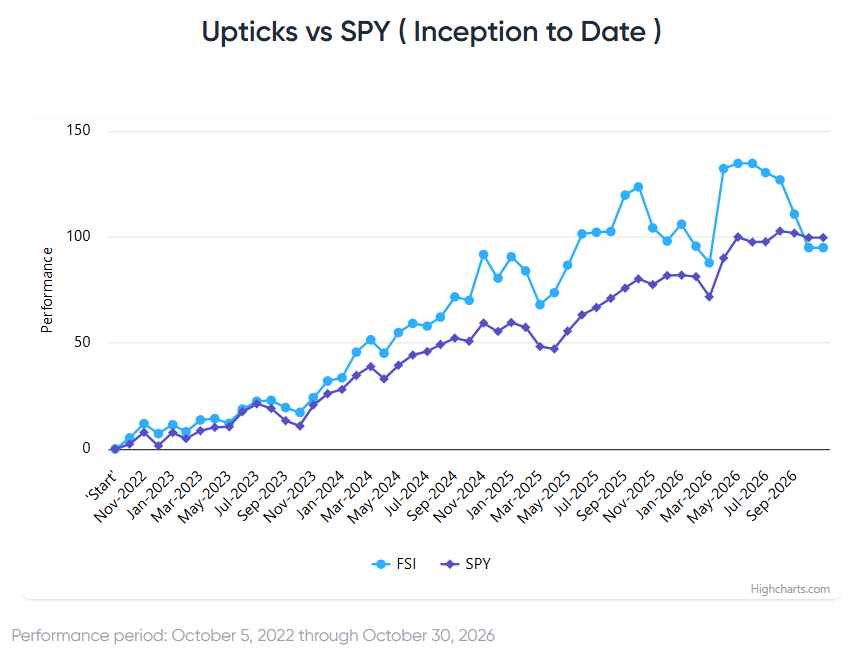
Stock List Performance
In the News
Bitcoin falls below $82,000 as investors retreat from risk assets
Oct 22, 2026

Dow Is Powered Higher by an Everything Rally
Oct 19, 2026
Why Micron stock’s drop is triggering ‘buy the dip’ calls
Oct 15, 2026