
Introduction: Asian stocks rise and oil price slips amid hopes of US-Iran peace deal
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
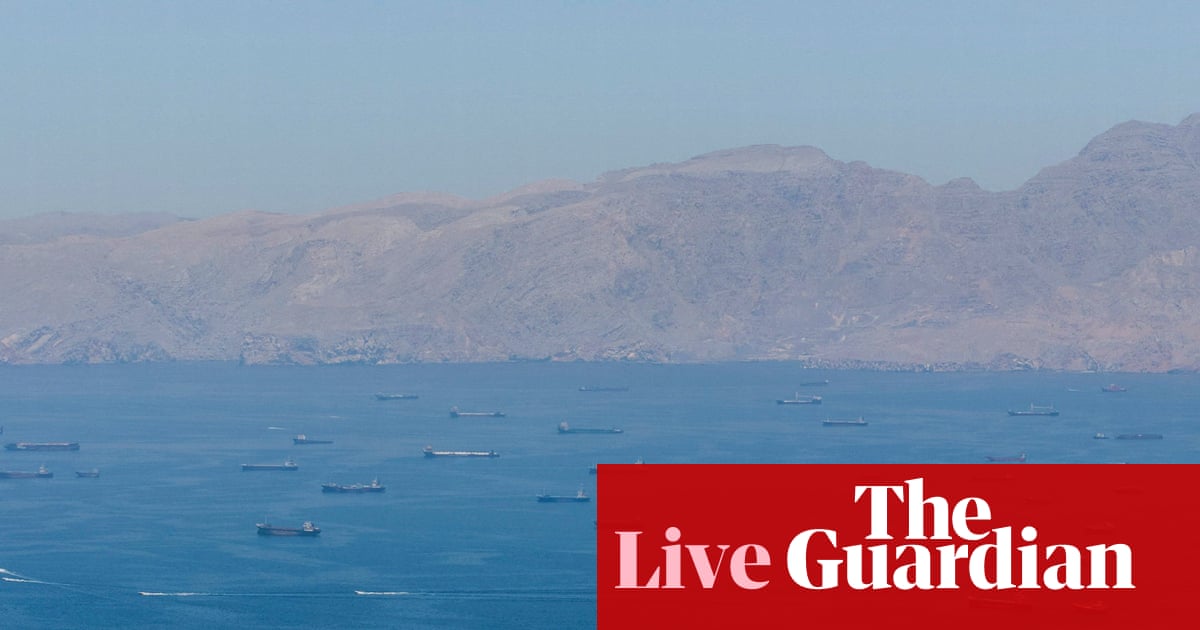
Asian stocks are rising today amid hopes of a US-Iran peace deal and the re-opening of the strait of Hormuz.
US president Donald Trump has circulated a draft peace agreement for the war with Iran among allies including Israel.
The draft is similar to the one that has been circulating around the Middle East, under which the strait of Hormuz would be opened to commercial shipping, the US blockade of Iranian ports would be lifted and Iran would be given access to as much as $12bn (£9bn) in frozen assets.
The aim would be for commercial shipping in the strait to return to pre-war levels within 30 days. Negotiations are expected to last as long as 60 days on the future of Iran’s nuclear programme.
Stocks are rising strongly in Asia, with the Japanese Nikkei up 2.65%, Hong Kong’s Hang Seng up 0.9% and the South Korean Kospi up 3.6%.
Some of the rally in Asia is being supported by enthusiasm for AI – shares in the chip making giant TSMC are up 2.6%, while Samsung Electronics and SK Hynix are up 6% and 0.6%, respectively.
The oil price has also slipped this morning. Brent crude, the international benchmark, is down by about 1% to $93.02 a barrel as investors weigh the impact of the potential reopening of the strait of Hormuz.
The agenda
7.45am BST: French inflation report
8.am BST: Spanish inflation report
9.20am BST: Andrew Bailey speech at the Reykjavik 2026 economic conference
1pm BST: Germany inflation report
1.30pm BST: Canadian Q1 2026 GDP
Key events
Show key events only
Please turn on JavaScript to use this feature
Above target inflation ‘appropriate’ given Middle East uncertainty, BoE governor saysBank of England Governor Andrew Bailey speaks during the Monetary Policy Report Press Conference at the Bank of England in London, Britain, April 30, 2026 Photograph: Kirsty Wigglesworth/Reuters
The governor of the Bank of England has said the bank is “tolerating temporarily above target inflation” to support the economy given the impact of the conflict in the Middle East.
Andrew Bailey, in the text of a speech he is due to deliver at the Reykjavik 2026 economic conference, said:
double quotation markGiven the context of softness in the real economy and uncertainty around the scale and duration of the shock, tolerating temporarily above target inflation to provide some support for the real economy is an appropriate way to approach the trade-off.
But that tolerance would weaken if signs of second-round effects begin to emerge.
The BoE’s monetary policy committee (MPC) last kept interest rates on hold on 30 April.
Bailey also reiterated his comments that the BoE had tightened monetary policy by taking expected rate cuts off the table “and that is already affecting the economy.”
double quotation markKey quoted rates on mortgages have increased since the onset of the conflict. The decision to hold reflected a judgement that continued weakness in the UK activity and the labour market is likely to lessen the strength of second-round effects from higher energy prices, while recognising that these effects are likely to be stronger, the larger and more persistent is the rise in global energy prices.
…We have to monitor the situation in the Middle East and how it affects the UK economy and inflation very closely and adjust policy as required.
The market is now pricing in one quarter-point rate hike by the Bank of England in November.
Updated at 05.36 EDT
Retailer shares fall after Deutsche Bank downgrades
Shares in some of the UK’s biggest retailers, including Dunelm and Wickes, are falling this morning after analysts at Deutsche Bank cut their ratings on the stocks.
The bank’s analysts are warning that demand could dry up from lower-income consumers amid higher inflation, especially on big ticket purchases.
They note that UK GDP forecasts have been consistently cut for the past two years, and that economists now expect real UK GDP growth of just 0.9% in 2026.
They said:
double quotation markThe UK is relatively exposed to energy shocks given its limited domestic supply and reliance on natural gas in heating and electricity generation. CPI is expected to average 3.1% over the year (from 2.1% previously) as higher commodity prices impact imports and second round pressures feed through supply chains and the wider economy.
With the ‘cost of living crisis’ still relatively fresh in consumers minds (especially as the majority of price increases never actually reversed) this will likely lead to a contraction in spending. In the short term many consumers will have benefited from an April pay rise hitting the bank accounts but this will erode as the year progresses and price increases follow a different cadence from income increases.
The bank has downgraded its view on B&M and Wickes to “sell”, and Currys and Dunelm to “hold”. The shares are down 1.5%, 2.3%m 2.1% and 3.4% respectively.
ShareInflation in France rises at fastest pace since 2024
Inflation in France accelerated at the fastest pace level in two years in May, feeding expectations that the European Central Bank could raise interest rates.
Consumer prices rose 2.8% from a year ago in May. Claus Vistesen, chief eurozone economist at Pantheon Macroeconomics, noted that French energy prices rose by 16.8% , following a 14.3% rise in April. He said:
double quotation markOverall, these data highlight that consumers in France are now exposed to a much more severe inflation shock than elsewhere in the major EZ economies, depressing consumer sentiment.
…Elsewhere in France, consumers’ spending slipped at the start of Q2, and GDP growth for Q1 was revised down by 0.1pp, to -0.1%, adding to the recent negative shift in the French macro data, highlighted by the May surveys.
The fall in consumers’ spending, ex-services, was brought down by a plunge in energy consumption. Spending on diesel and petrol was pulled lower by higher prices, depressing volumes, while spending on electricity consumption remained subdued due to exceptionally warm weather.
Core spending, meanwhile, was stronger, rising by 0.2% after a 1.7% increase in March. Rising spending on clothing and in “other goods” offset declines in durables, including autos.
Meanwhile in Spain, the inflation reading for May came in at 3.6%, broadly in line with what economists had been expecting but also ahead of the ECB’s 2% target.
There will be more economic data out of Europe later today, as the ECB weighs how much the conflict in the Middle East is affecting inflation.
ShareOcado software to be used in Asda home deliveries from next yearAn Ocado delivery van seen driving in Hatfield Photograph: Matthew Childs/Reuters
Closer to home this morning, Asda has secured a deal with Ocado to use the company’s software for all home deliveries starting next year.
Ocado software will be used in the supermarket’s deliveries from stores and “dark stores” – smaller warehouses that are not open to the public – from early 2027, the companies said in an announcement on Friday.
Asda will also use Ocado’s platform to deliver orders placed through other apps such as Uber Eats, Deliveroo, and Just Eat, and for click and collect orders.
Shares in Ocado are up by about 14% this morning.
Read my colleague Jasper Jolly’s full story here:
Updated at 04.05 EDT
European stock markets open higher
Stock markets in Europe have opened higher this morning, amid cautious optimism that the US and Iran are on the verge of securing a 60-day truce renewal.
The UK’s blue chip FTSE 100 index has opened up about 0.1% higher this morning. The Stoxx Europe 600 is up 0.3%.
Mohit Kumar, of the broker Jefferies, explains that a US-Iran deal could have a greater impact on investors’ expectations for interest rate movements this year than in the stock market.
double quotation markIn terms of market reactions if a deal is agreed upon, we should see another leg higher in risky assets and lower in rates. However, positioning suggest that the rates market should see a greater reaction than equities.
For equities, we are still bullish, but believe that the easy part of the rally is behind us. S&P positioning has reached just above 5, while Eurostoxx is at +2.2. Positioning is not extended yet, but beyond the relief reaction of a deal, we do not see a massive move higher from these levels. European equities can get a boost higher in the near term simply because positioning is much less crowded than in the US.
For rates, positioning is on the short side, with [US Treasuries] positioning just below -4 and Bunds close to -3. The recent rally in rates has led to some short covering in both US and Europe, but we still see more room to go. Our view remains that the front end of Europe, UK and the US are still mispriced. For the ECB, we can see one hike (in June), simply because they have to justify their inflation credibility. However, we do not see a series of rates hikes and maintain our long position at the front end of the curve.
For Fed and the BoE, we maintain the view that the next move would be a cut and not a hike. Markets have repriced in the UK with only 35bp of hikes priced for this year and less than 2 hikes till terminal. Our view remains that the BoE would be taking rates towards 3% by middle of next year and keep our long position at the front end of the curve.
For the Fed, we do not see a Warsh Fed delivering any hikes. For us, the question is when and not if there will be a cut. From a fundamental perspective, we would argue that near term inflation would be high and hence will be difficult for Warsh to deliver a rate cut before mid-terms. But there is a political element, and eventually it would depend on how soon oil prices drop below $80 and central banks start treating the latest oil price shock as a transitory effect on inflation rather than leading to second round effects. Our base case remains one of 2 rate cuts over the next 12 months.
ShareOil on track for one of its biggest monthly drops ever
Brent crude, the international benchmark for oil, is heading towards one of its biggest monthly drops ever as it nears a fall of 17% since the start of May.
The market is hopeful that a US-Iran deal, which would extend the ceasefire by 60 days and reopen the strait of Hormuz, will materialise.
Jim Reid of Deutsche Bank notes that the details will be important, but that “US Treasury Secretary Bessent said that Trump’s three ‘red lines’ for a deal are for Iran to open the Strait of Hormuz, turn over its enriched uranium and end its nuclear program. And Bessent also posted earlier in the day that the US would ‘not tolerate any effort to impose a tolling system in the Strait of Hormuz.’”
double quotation markWhilst the geopolitical headlines provided the main boost to markets yesterday, they got further support after the latest US PCE inflation print was softer than expected, easing concern around the need for rate hikes. The release showed that headline PCE was only up +0.4% in April (vs. +0.5% expected), whilst core PCE was up +0.2% (vs. +0.3% expected). So that led investors to dial back expectations for a Fed rate hike, with the probability of a hike by December down to 59% by the close, having been at 62% the previous day.
Fed officials also didn’t sound in a rush to hike either, with NY Fed President Williams saying that monetary policy “is right where we want it to be”. Admittedly, there was discussion of a hike, with St Louis Fed President Musalem acknowledging there “there is a scenario where the economy might require a rate increase”, but that was still conditional.
ShareIntroduction: Asian stocks rise and oil price slips amid hopes of US-Iran peace deal
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
Asian stocks are rising today amid hopes of a US-Iran peace deal and the re-opening of the strait of Hormuz.
US president Donald Trump has circulated a draft peace agreement for the war with Iran among allies including Israel.
The draft is similar to the one that has been circulating around the Middle East, under which the strait of Hormuz would be opened to commercial shipping, the US blockade of Iranian ports would be lifted and Iran would be given access to as much as $12bn (£9bn) in frozen assets.
The aim would be for commercial shipping in the strait to return to pre-war levels within 30 days. Negotiations are expected to last as long as 60 days on the future of Iran’s nuclear programme.
Stocks are rising strongly in Asia, with the Japanese Nikkei up 2.65%, Hong Kong’s Hang Seng up 0.9% and the South Korean Kospi up 3.6%.
Some of the rally in Asia is being supported by enthusiasm for AI – shares in the chip making giant TSMC are up 2.6%, while Samsung Electronics and SK Hynix are up 6% and 0.6%, respectively.
The oil price has also slipped this morning. Brent crude, the international benchmark, is down by about 1% to $93.02 a barrel as investors weigh the impact of the potential reopening of the strait of Hormuz.
The agenda
7.45am BST: French inflation report
8.am BST: Spanish inflation report
9.20am BST: Andrew Bailey speech at the Reykjavik 2026 economic conference
1pm BST: Germany inflation report
1.30pm BST: Canadian Q1 2026 GDP